


Our Perspectives 2026 survey confirms that secondaries are growing in investor popularity.
Secondaries have quickly moved from the periphery of private credit to the mainstream. Our Perspectives 2026 survey reveals the evidence of this sudden change.
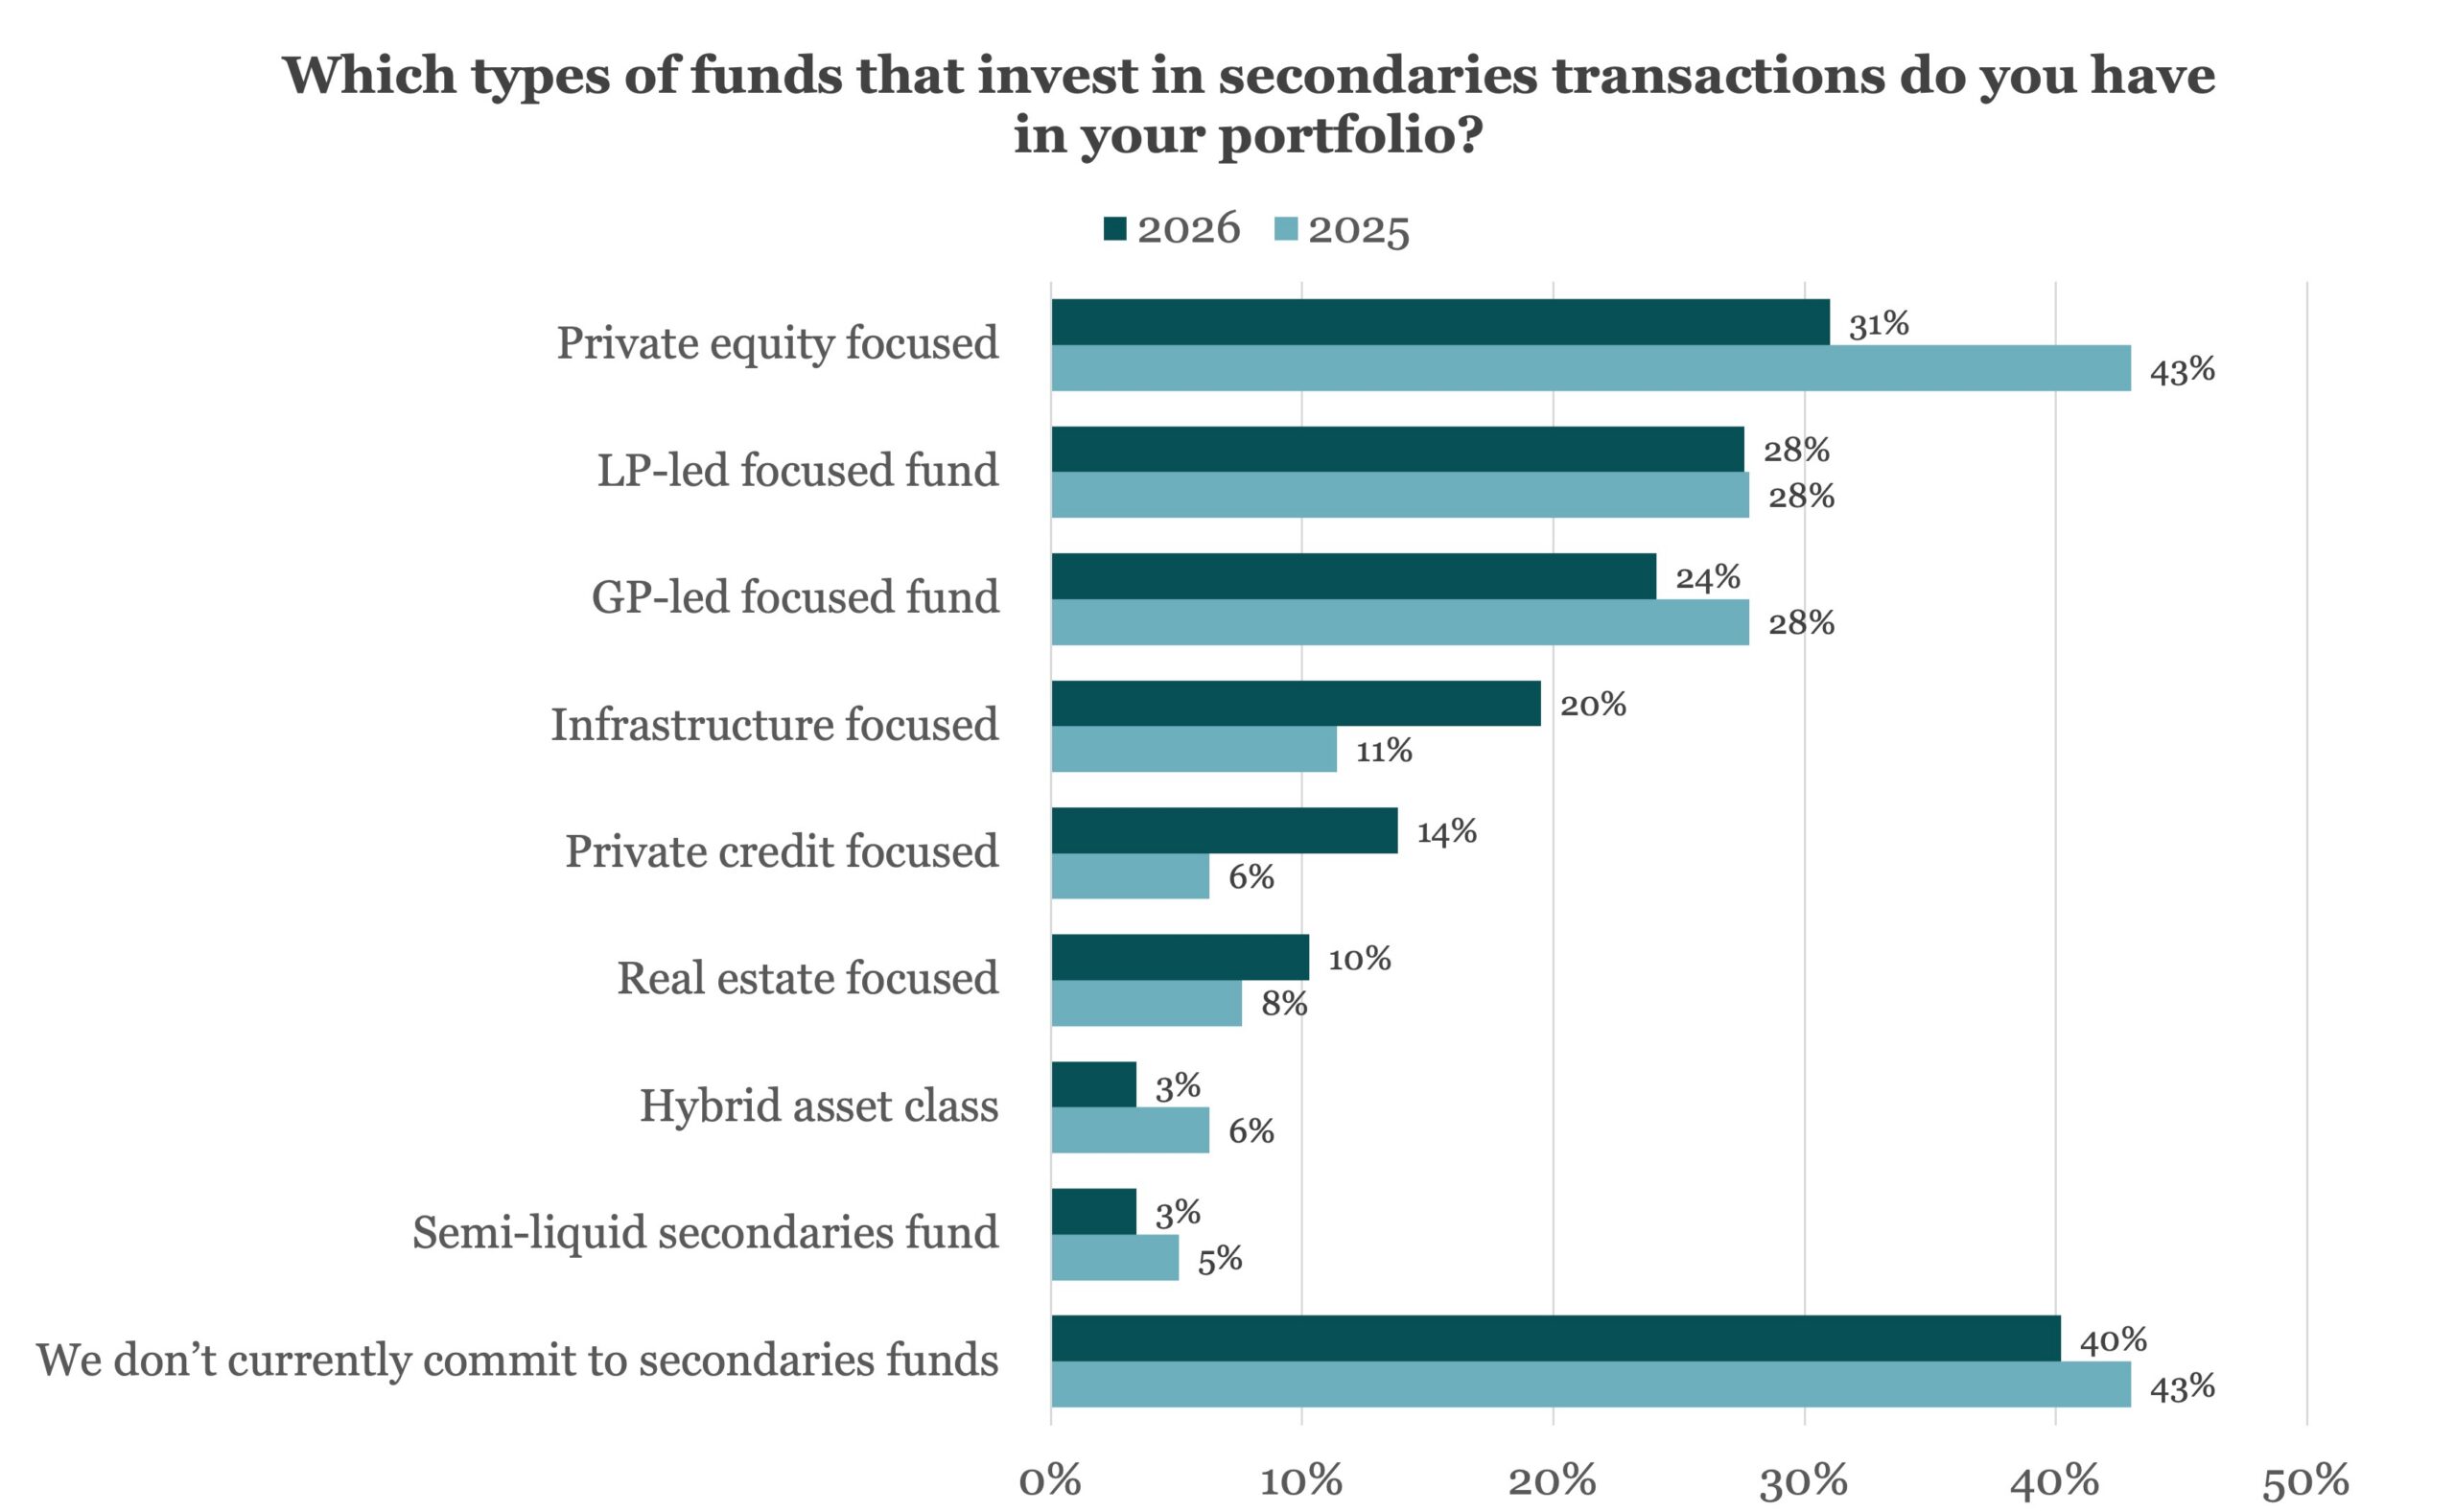
Our LPs were asked what the asset class focus was of secondaries funds they were committed to. Here, private debt has moved more into line with other asset classes with 14 percent saying they had exposure to private credit secondaries. This still lags private equity-focused secondaries funds (31 percent) and infrastructure-focused secondaries funds (20 percent) but is ahead of real estate-focused secondaries funds (10 percent). In the equivalent survey a year ago, private debt secondaries were on just 6 percent.
Moreover, private credit secondaries investor activity is expected to increase over the coming 12 months. In the same survey a year ago, 20 percent of LPs said they were either planning to buy only, sell only or both buy and sell on the private credit secondaries market. In the current survey, that figure has risen to 29 percent.
One relatively new feature of the secondaries landscape – including in private credit – is the continuation vehicle. This year’s survey finds 40 percent of LPs saying that they saw substantially more continuation vehicles over the last year. This compares with an equivalent figure of 35 percent a year ago.
Asked whether they were given enough time to make a decision on committing to a continuation fund – without being forced to roll or sell – only 16 percent said “always” while 41 percent said “sometimes”. More than a fifth of LPs – 21 percent – said they were “rarely” or “never” given enough time.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.