


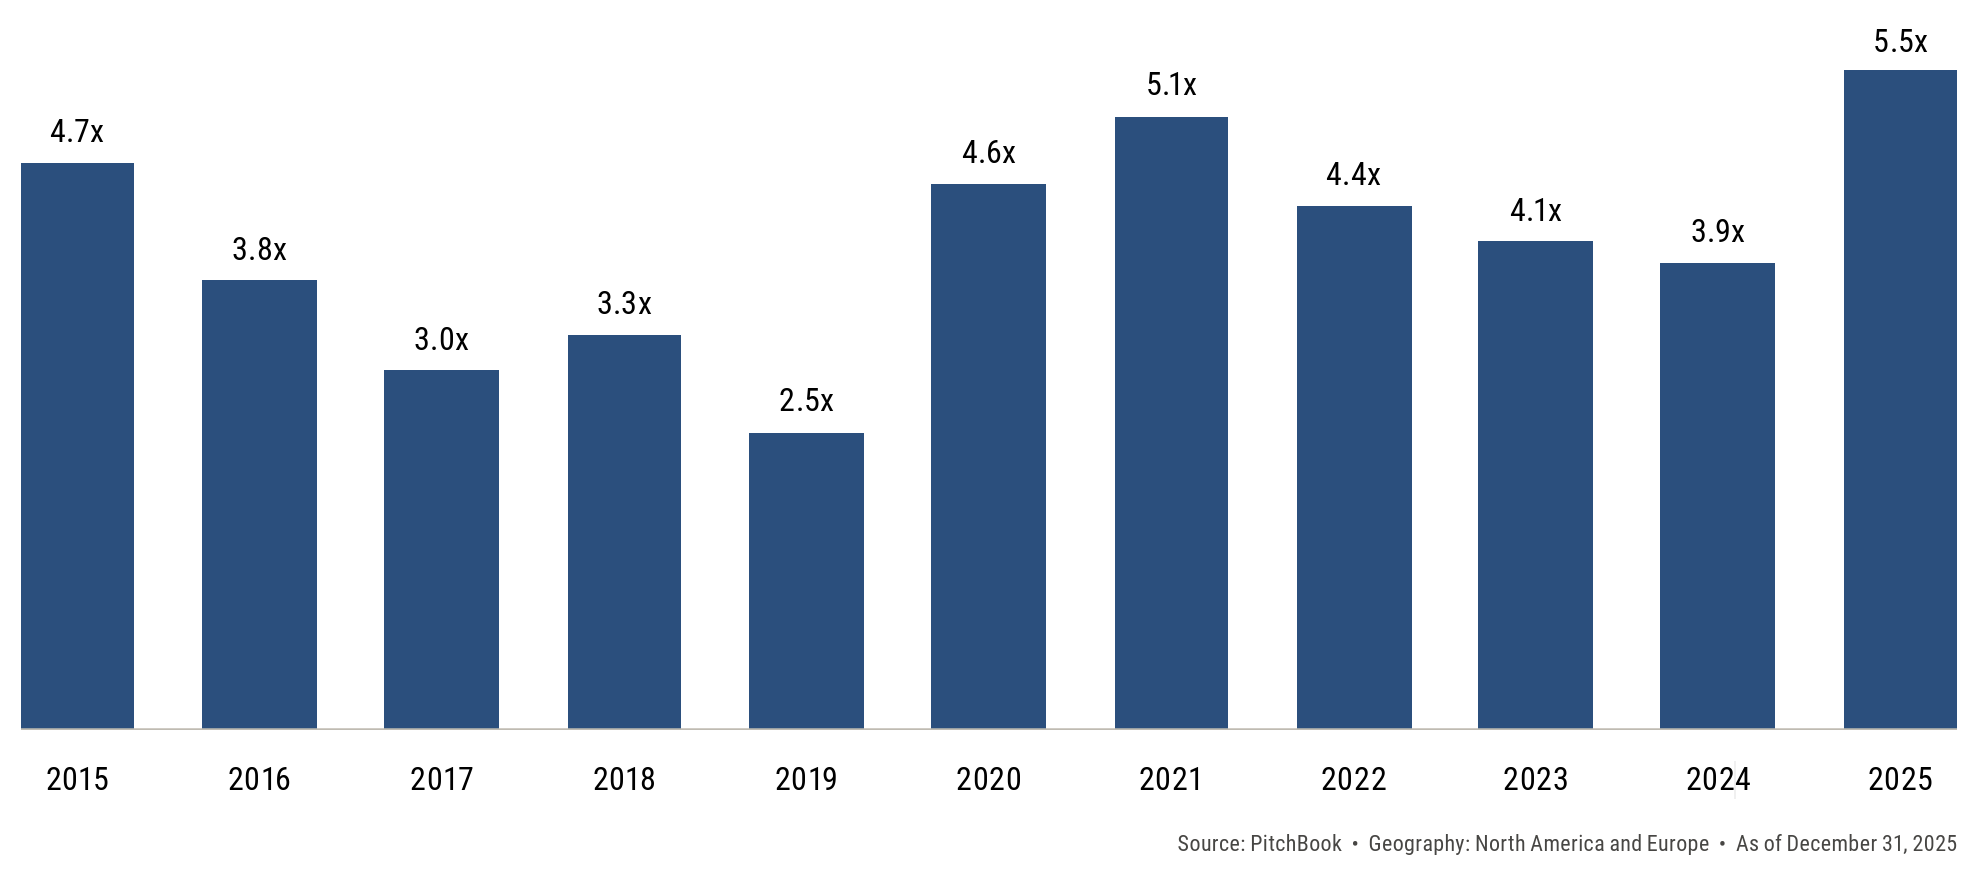
Median enterprise value (EV)/revenue multiples on PE deals of $2.5 billion or more
Download PitchBook’s Report here.
PE buyout valuations were a mixed bag in 2025, with EBITDA and revenue multiples undergoing different trends YoY, but ultimately rebounded from recent lows seen in 2023 to reach the high levels seen in 2021. EV/EBITDA multiples adjusted down from the peak of 12.9x in 2024 to 12.5x in 2025, which is still the second-highest annual median multiple and in line with that of 2021. As for revenue multiples, which were slow to recover from the dip in 2023, they experienced a significant increase in 2025, rising from 2.1x in 2024 to 2.5x. The return to median multiples last seen during the dealmaking frenzy of 2021 reflects a similar fervor underlying the current resurgence in PE deal activity.
(Past performance is no guarantee of future results.)



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.