


“We’re in a credit cycle. People denied it for a while. I don’t think there’s a lot of denial anymore.” That’s how one lender sees things today. And certainly, recession risk is always top of mind for investors. With non-accruals on the rise, that has reignited concerns about where exactly we stand.
Pockets of stress have unquestionably risen – particularly in 2021-vintage loans and certain corners of the software sector. Defaults in software remain contained for now, but there’s real concern about current marks and an approaching maturity wall, with roughly 25% of outstanding software loans coming due by 2028. That said, as we noted in our Dot Calm piece, “The lesson is not that software is broken. Indeed, some would argue today’s best performers are in the software space.” And the data backs this up. S&P’s review of 225 software companies, discussed on our webinar, found 80% grew revenue and 70% grew earnings year-over-year. The magnitude of that growth was strong too, as S&P reported median revenue growth of 13% and EBITDA growth of 24%.
Some software companies will inevitably be disrupted, but it’s far from clear this is a sector-wide issue rather than a handful of idiosyncratic stories. In conversations with many of our sponsors, several continue to point to AI as a genuine tailwind for middle market companies across both software and other sectors.
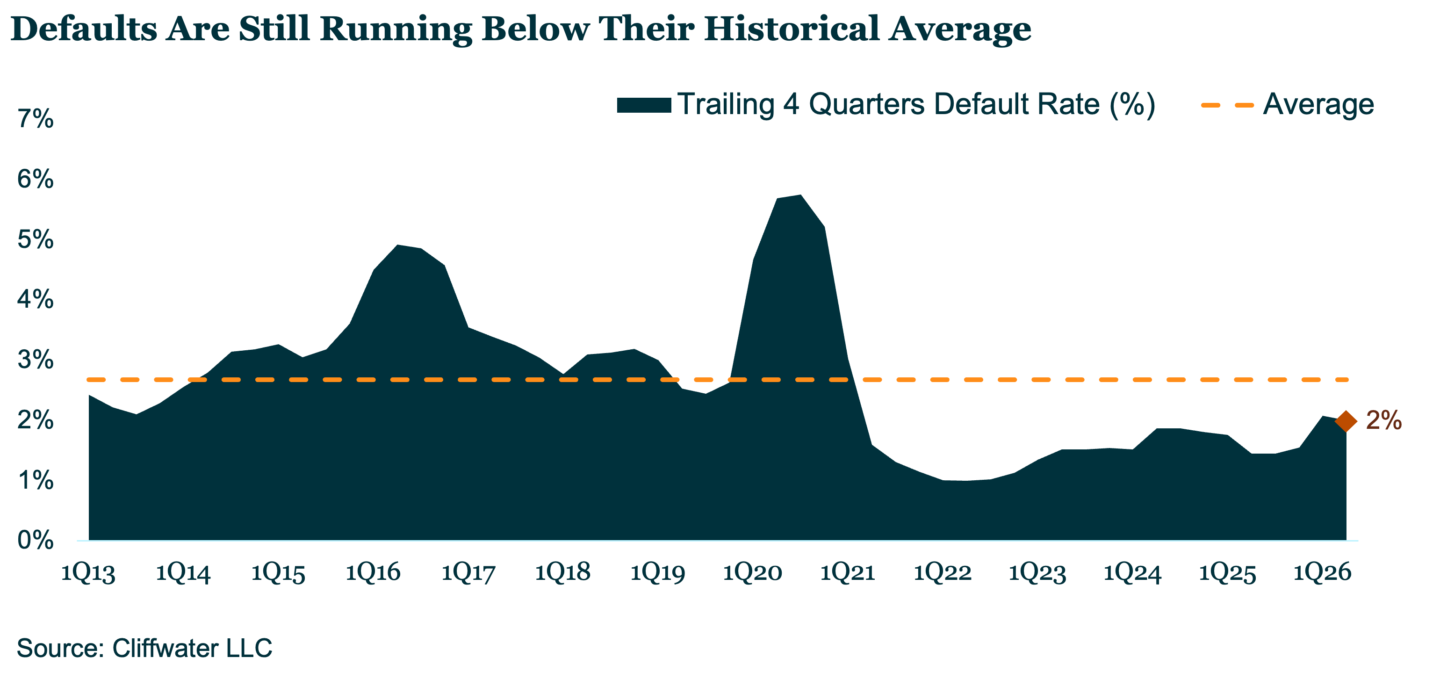
Beyond these pockets of stress, forecasts tell a more measured story. KBRA projects sponsored direct lending defaults will run around 2.25% this year, versus 3.5% for syndicated loans and 2.75% for high yield. Those figures are higher than last year, but context matters. While rising, they’re doing so from a low base, and remain below long-term historical averages (see Chart). That combination looks more like a normalization of credit conditions than the start of a genuine credit cycle.
The fundamentals also back this up. The economy remains in good shape, and end markets for core middle market borrowers are holding up reasonably well, with local business confidence running near its highest level in the last four years. Revenue growth among these companies also continues to outpace the S&P 500 – not what you’d expect in the early stages of a turn in the cycle.
None of this means portfolios don’t need close monitoring. Conditions look fine today, but that can obviously change. The real debate shouldn’t be whether we’re in a cycle. It should be whether what we’re seeing is normalization or deterioration, and right now, things point to normal.


Latest news
Software, technology and consumer sectors lose deal share in 9M’26
The software and technology sector, the second most active sector in 2025 at 17% of total deal activity, slid to fifth place in the first nine months of 2026.


Leveraged loan investors see gains in November
Following a 0.25% decline in October, the Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned 0.60% this month through…