


Please email us if you are interested in the full direct lending analytics report.
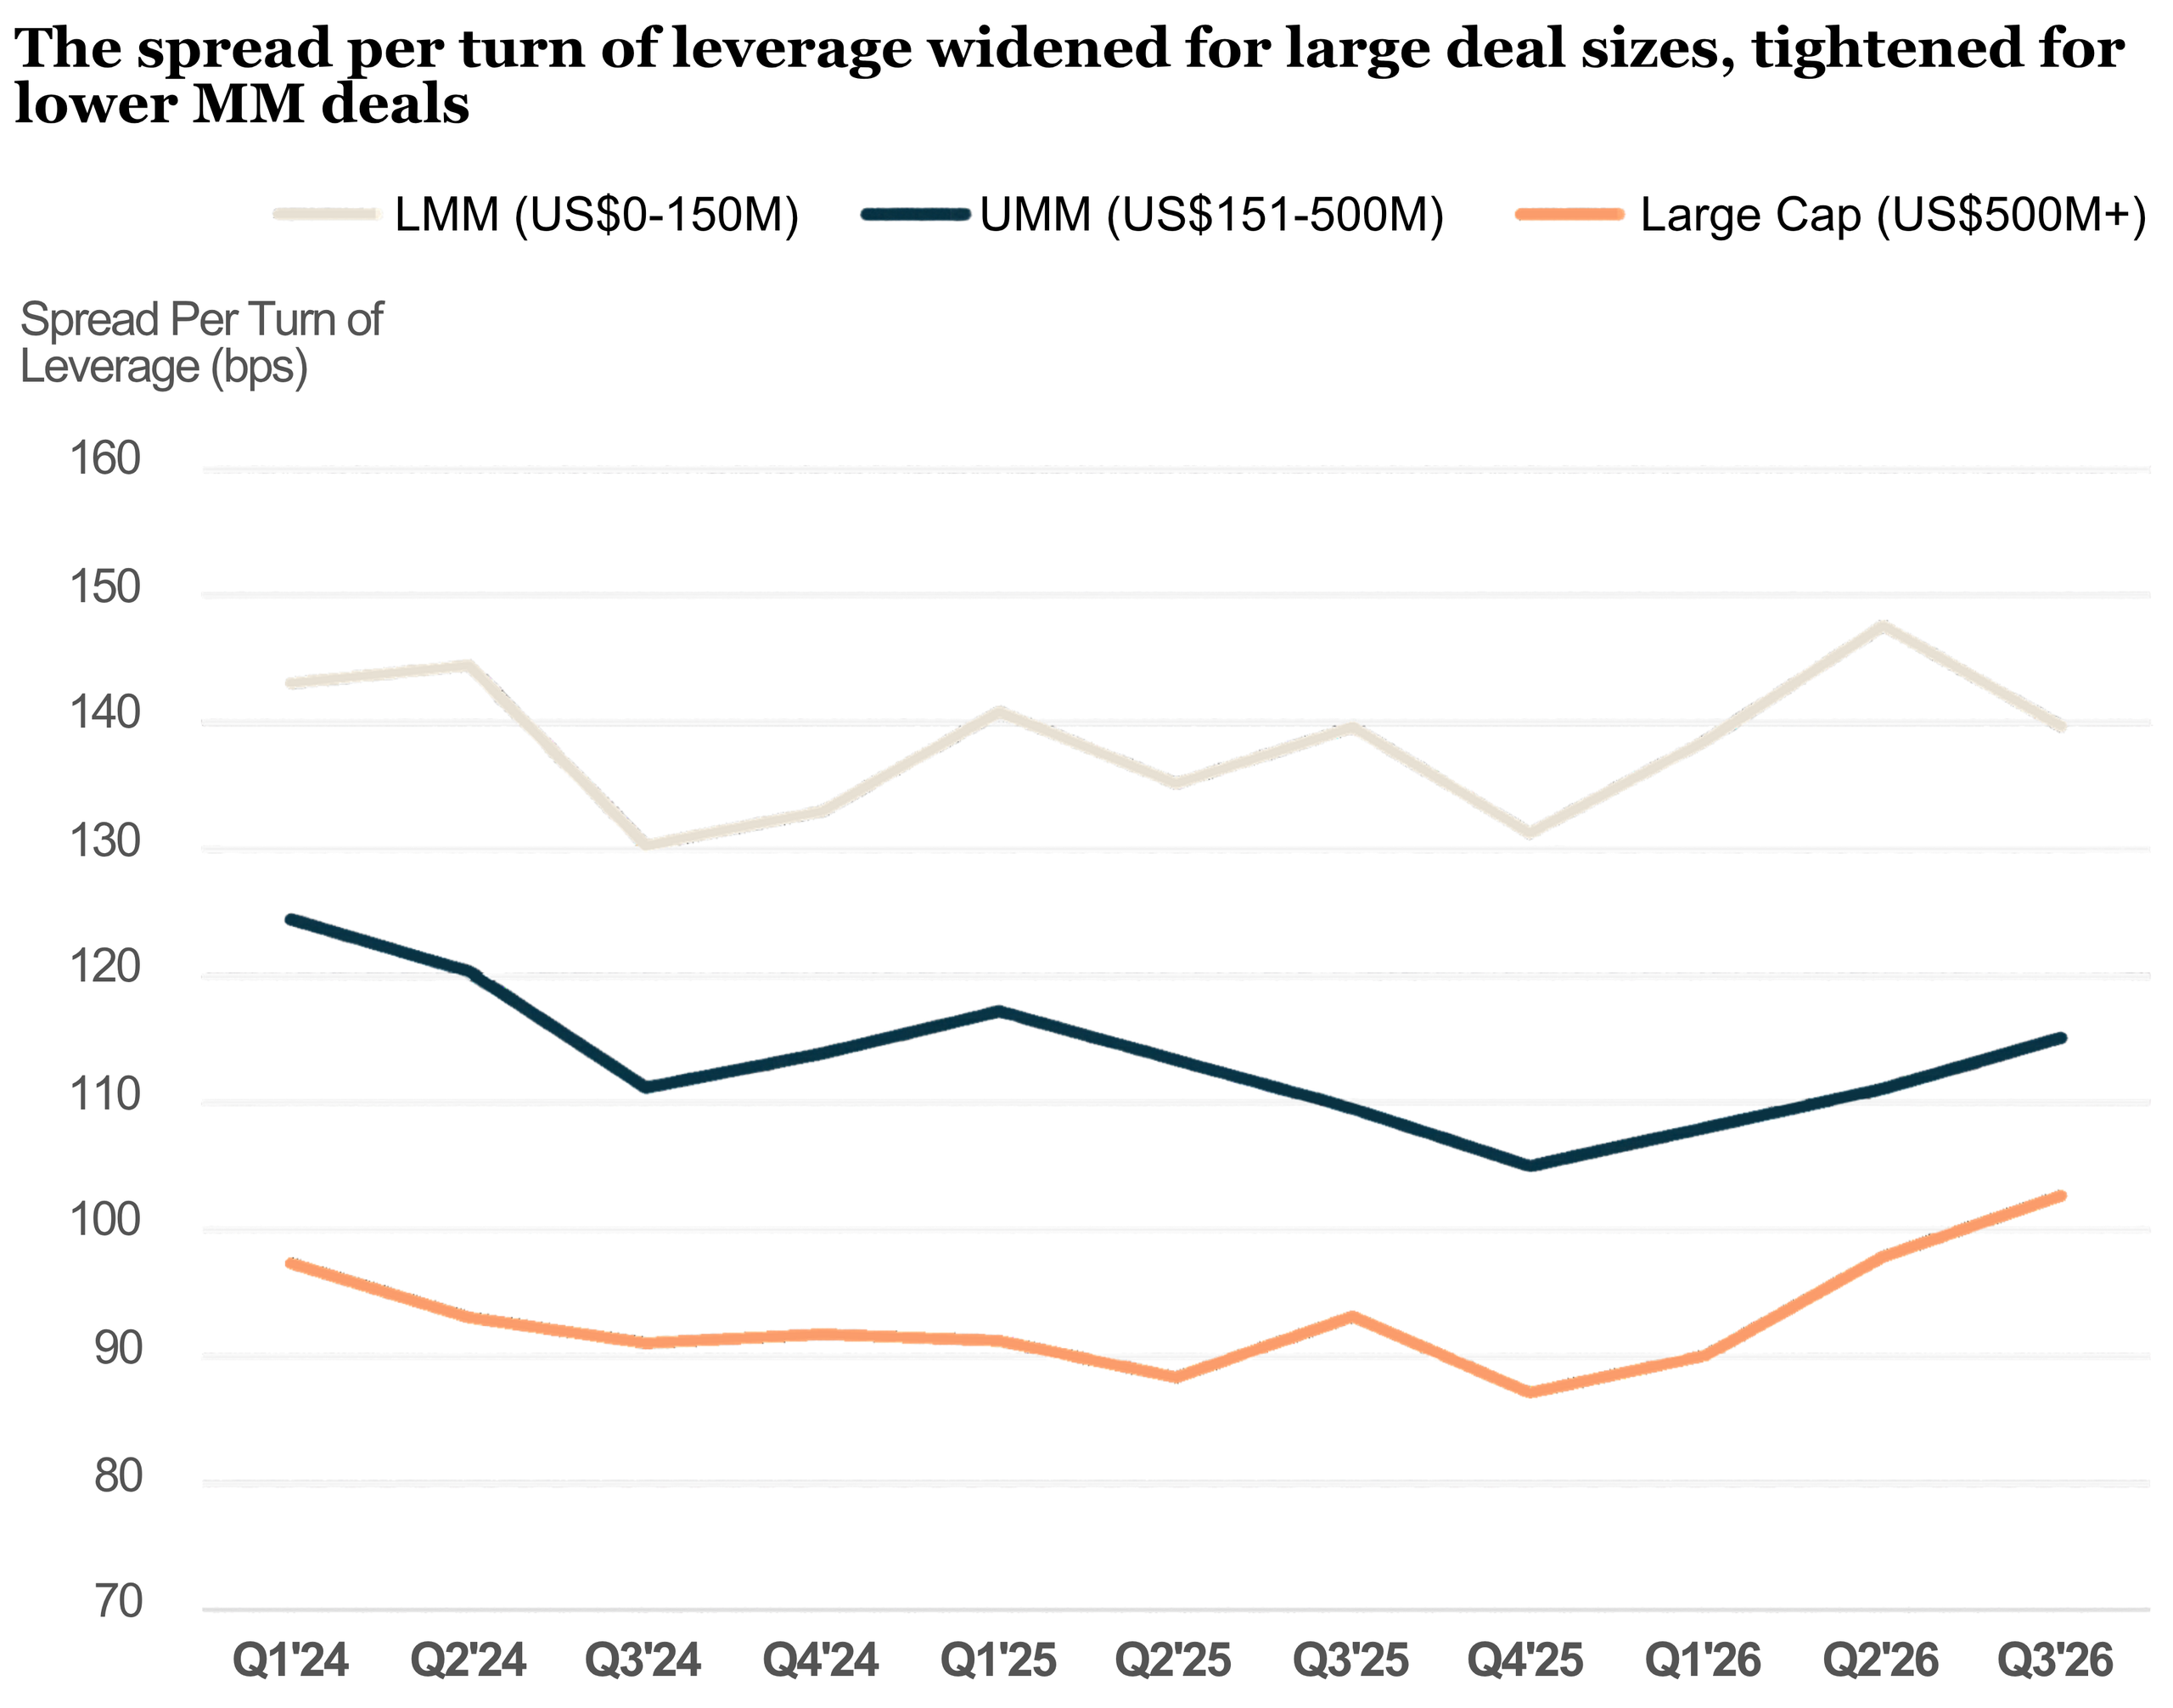
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter. The lower middle market was the exception, as leverage for this market segment widened in the third quarter. In the lower middle market the average spread per unit of leverage decreased 5% quarter over quarter to 140 bps. For larger middle-market credits (with total deal size of $151 million to $500 million), the spread per turn of leverage widened 4% to 115 bps in the third quarter. In the large-cap market it was up by 5% to 103 bps in the third quarter of 2026.




Latest news

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…
Private debt cashflows ($B)
Looking at the wider private markets funds landscape, private debt can be seen as a bright spot—for now—among individual strategies.