
Prince wrote “1999” in 1982, when the year itself sounded like science fiction. It became the New Year’s Eve anthem and landed on Rolling Stone’s list of the greatest songs of all time. Everyone knows the chorus. Fewer know the story behind it. Prince expected “rough times” ahead, but he “wanted to write something that gave hope.” So, Prince wakes up convinced it’s judgment day and decides to party anyway.
Private credit threw its own party in 2021. Rates sat at zero, valuations hit records, and deals closed at a breakneck pace. Then the Fed raised rates 525 basis points between March 2022 and July 2023. Just like Prince, portfolio companies and lenders are now facing their own judgment day.
The cracks are starting to show. Many of those deals closed with more leverage than historical norms and have since added another half-turn. At zero rates, that was manageable. With higher rates and maturities approaching, it’s becoming a problem. Consider the math. For a company levered 6x at today’s base rates, interest alone would eat roughly half of EBITDA. That’s before a dollar goes to capex, working capital, or paying down debt.
As one manager put it, “Vintage 2021–22 funds with high purchase multiples may face refinancing pressure from higher rates and multiple compression. Those challenges could recede if rates and inflation come down, but the direction of rates is unclear right now.”
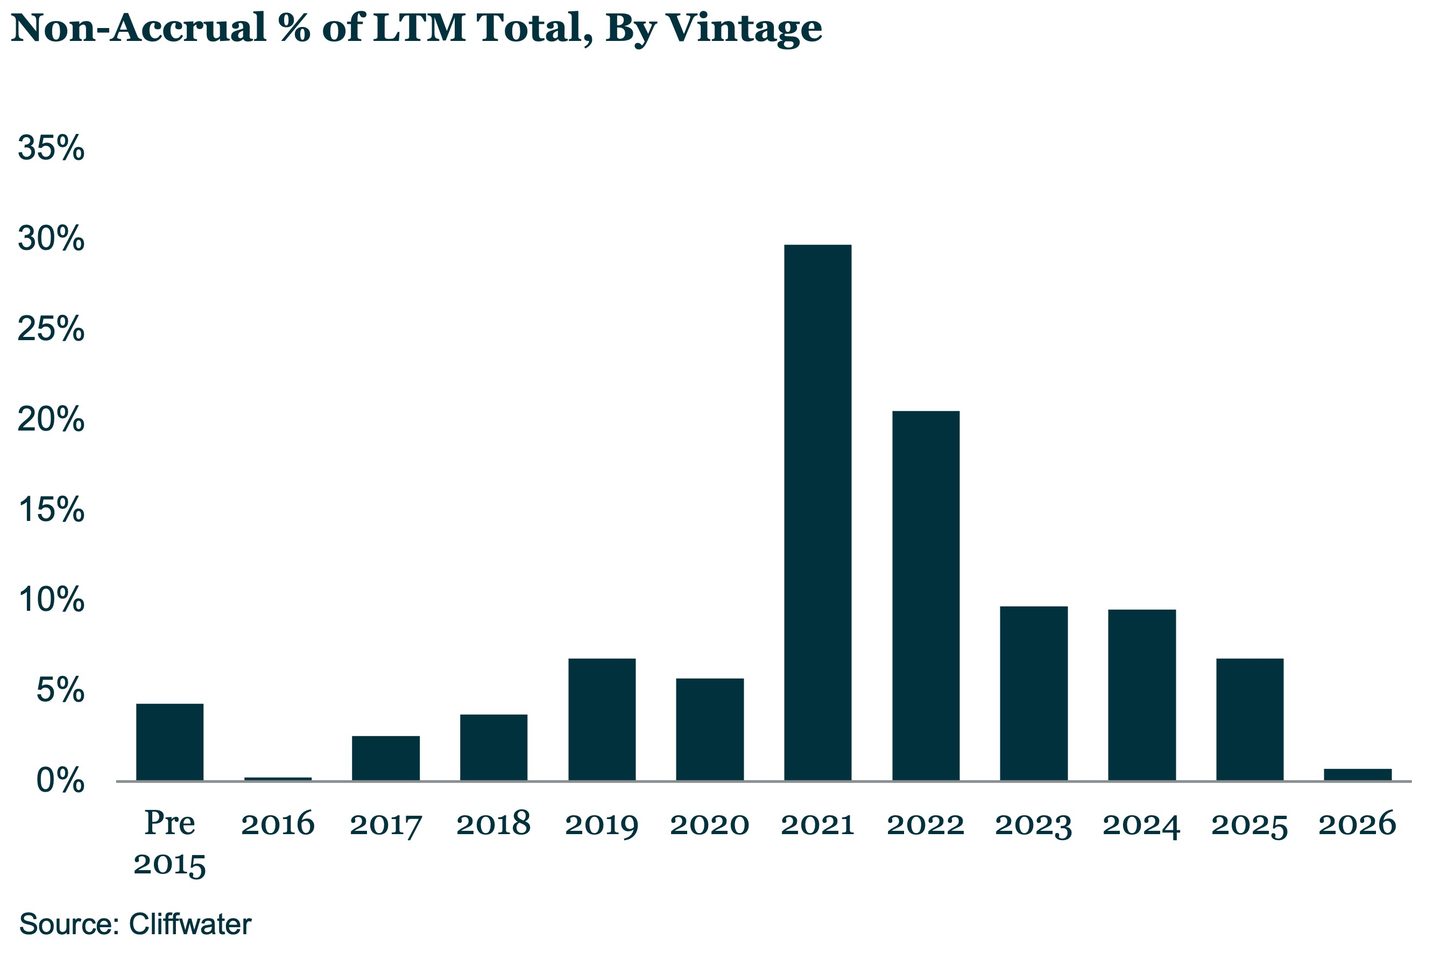
Look at non-accruals. Over the last 12 months, the 2021 vintage accounted for 30% of non-accruals. Add in 2022, and that share climbs to about half (see Chart). Lincoln International also found those same two vintages drove roughly 70% of foreclosed principal in early 2026. Those are the deals where lenders took the keys.
And the worst may still be ahead. Lincoln estimates that about $40 billion of debt maturing through 2027 originated in the 2020 and 2021 vintages, roughly 56% of all the debt coming due.
Then look at the marks. Of the $652.9 billion maturing between 2027 and 2030, $87.2 billion is tied to loans already marked below 90. Only $22.9 billion of that comes due next year. The remaining $64 billion lands over the following three years. That’s not a cliff. It’s a staircase, and every step can mean another year of higher coupons, compounding PIK, and thinner equity cushions.
Remember Y2K? The world spent hundreds of billions of dollars bracing for midnight, and the clocks rolled over without a hiccup. The bill for 2021 won’t be painless. Still, not every company in the 2021 vintage is a bad one. Plenty are good businesses with complex but temporary problems. For the sponsors and borrowers who need a bridge rather than a bankruptcy, capital solutions is the one bringing coffee the morning after.
The party’s over. But like Prince, capital solutions offers reason for hope.
Latest news
Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.
Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.