


Source: Debtwire Par
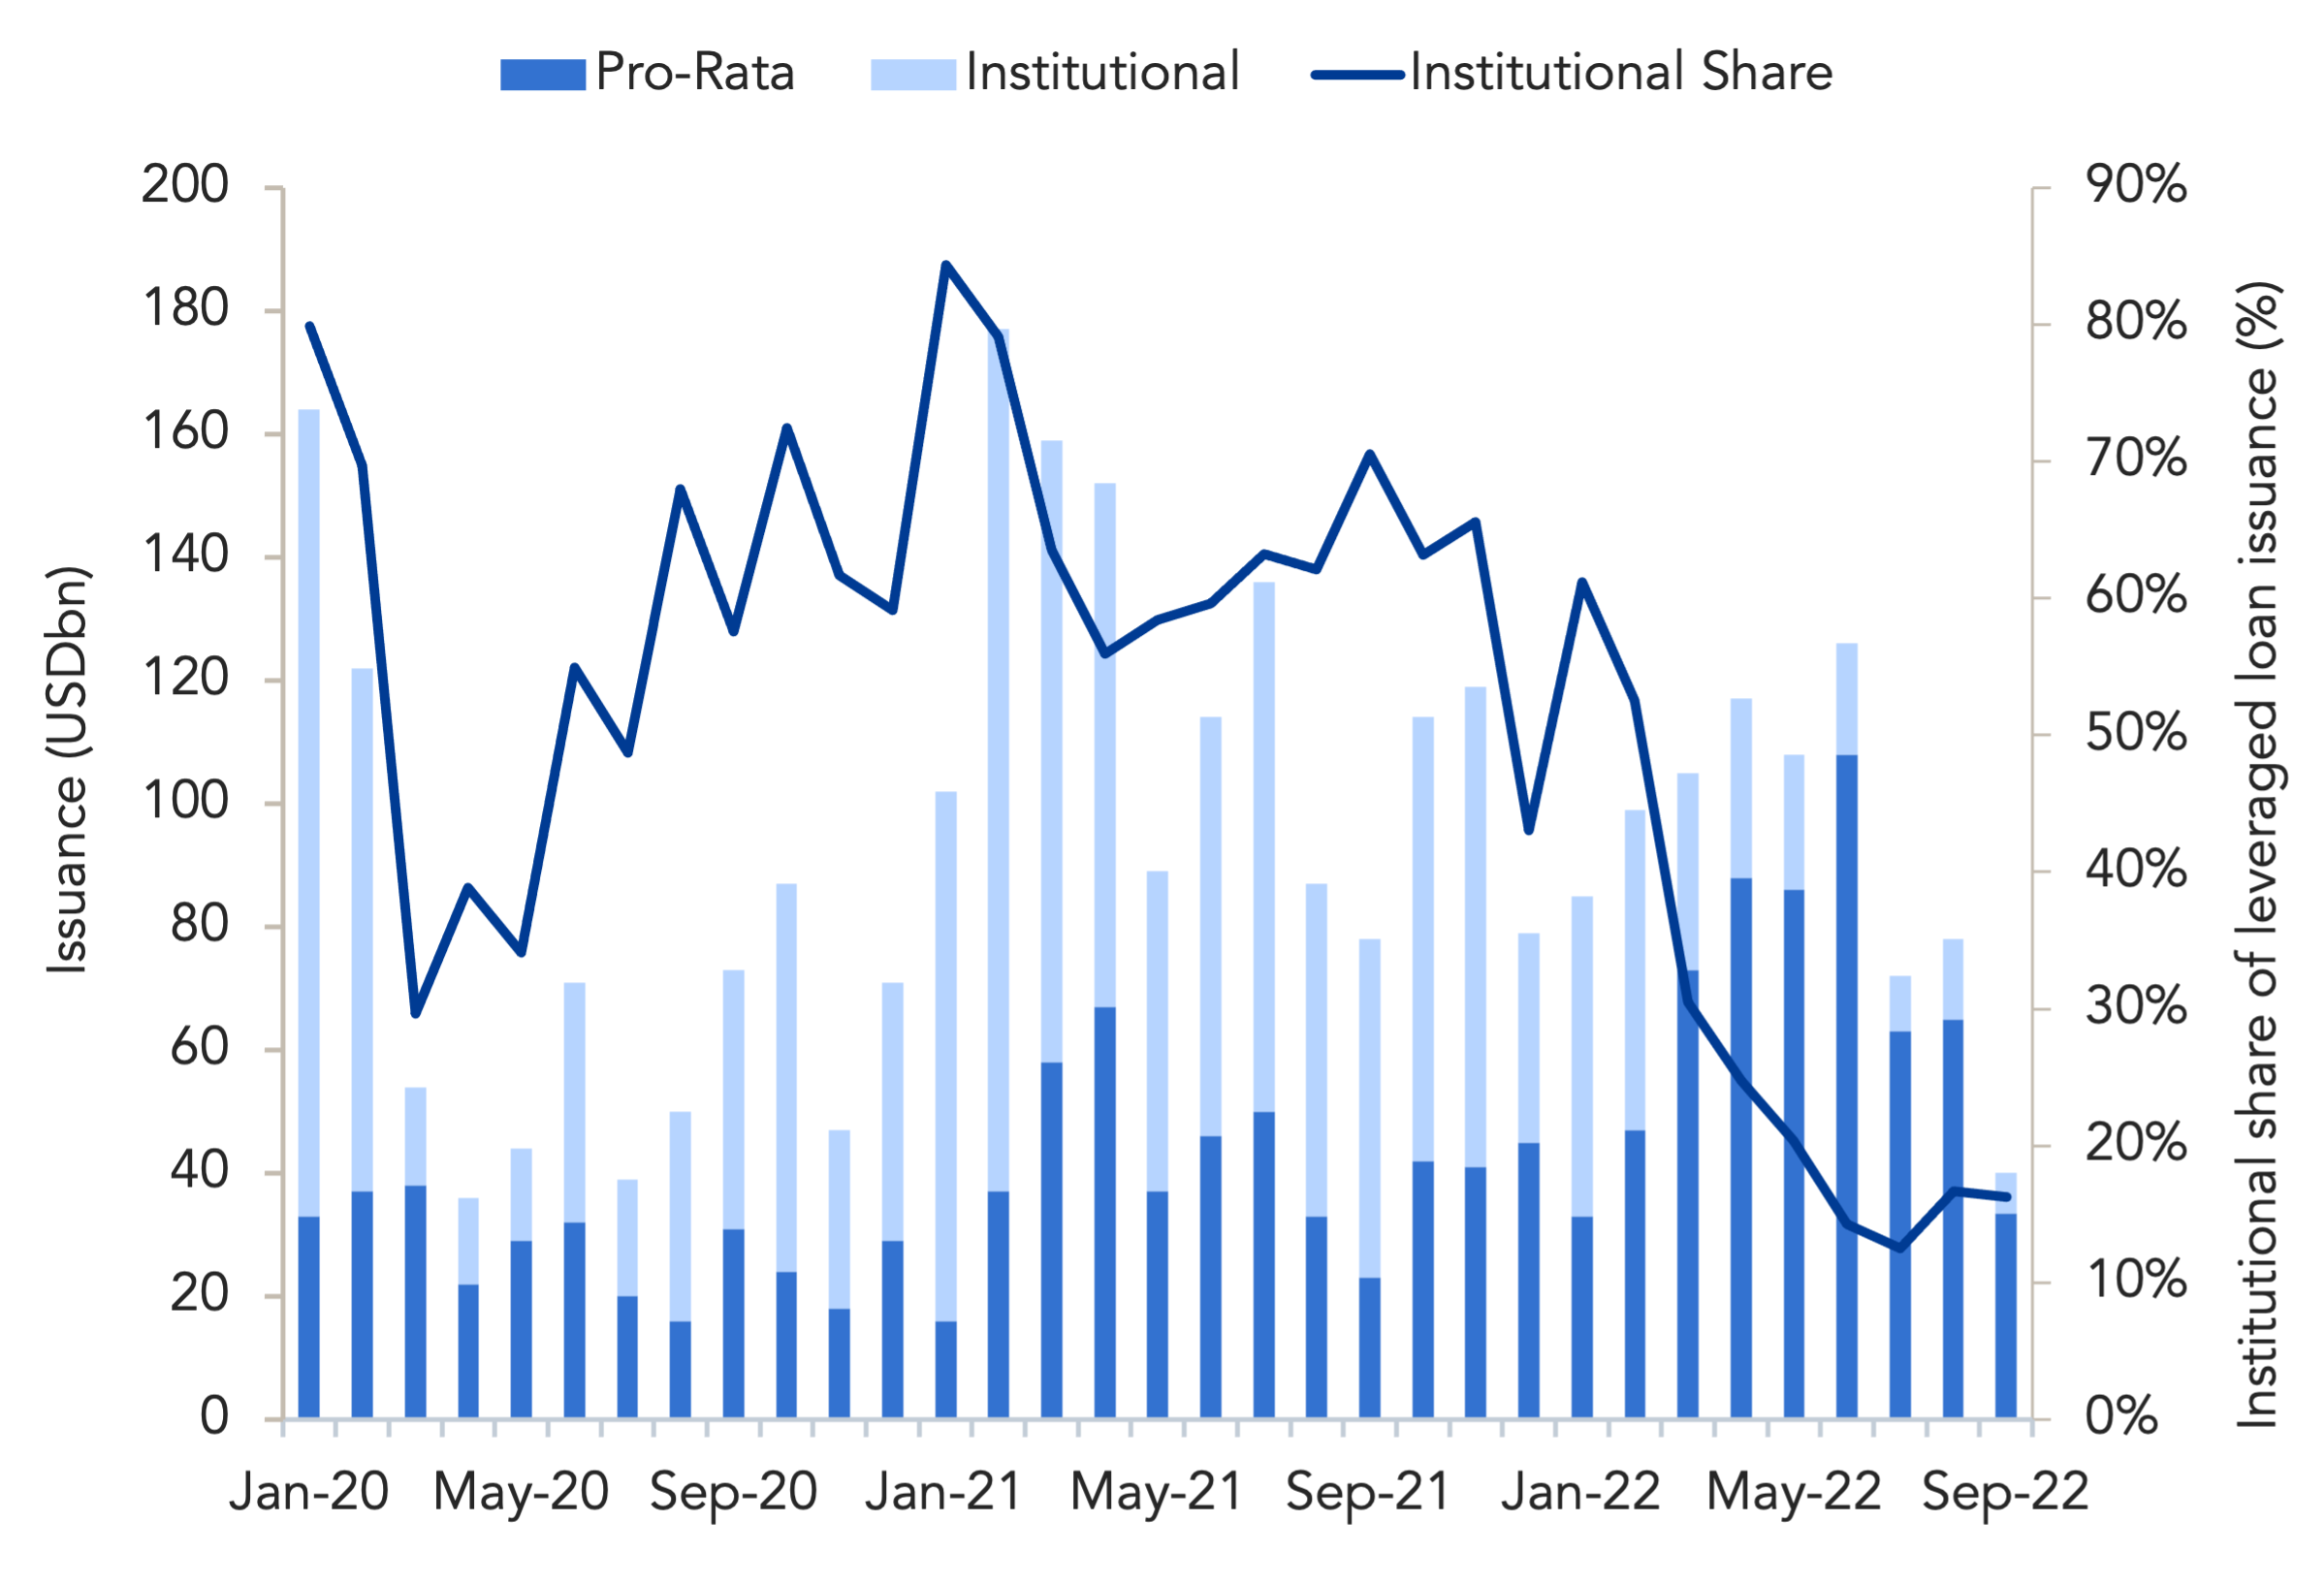
Institutional loan issuance has plummeted to a third of the levels seen last year. During the first nine months of 2022, institutional volume was USD 233.2bn, down 68% from USD 726.9bn in 9M21, and 39% below the USD 384bn seen in 9M20 when COVID-19 first roiled markets. In the secondary market, where lenders offload that debt to investors, bids have tumbled more than seven points this year, amid worries over the Federal Reserve’s aggressive rate hikes to combat inflation and a looming recession. Only 1% of loans currently trade in the par-plus segment of the market. No wonder lenders have shied away from underwriting debt that could, in the current market, remain on their books until investors are willing to take on the risk, often at a significant discount.
The pro-rata loan market, where syndicate bankers typically share risk evenly, has filled the void. Volume there was down just 24% year-on-year to USD 830.5bn in 9M22. Institutional loans made up just 15% of total leveraged loan issuance in 3Q22 – its lowest level in years – down from 67% in 9M21 and 28% for 9M22.
Another sign of the shift in risk tolerance can be seen in the rising volume of asset-based lending. ABL issuance reached USD 83.1bn during 9M22, up 40% year on year. Revolvers, amortizing term loans, and asset-based loans generally avoid some of the cash flow and trading risks of institutional tranches, making them more attractive in the current market climate.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
