


Source: Debtwire Par
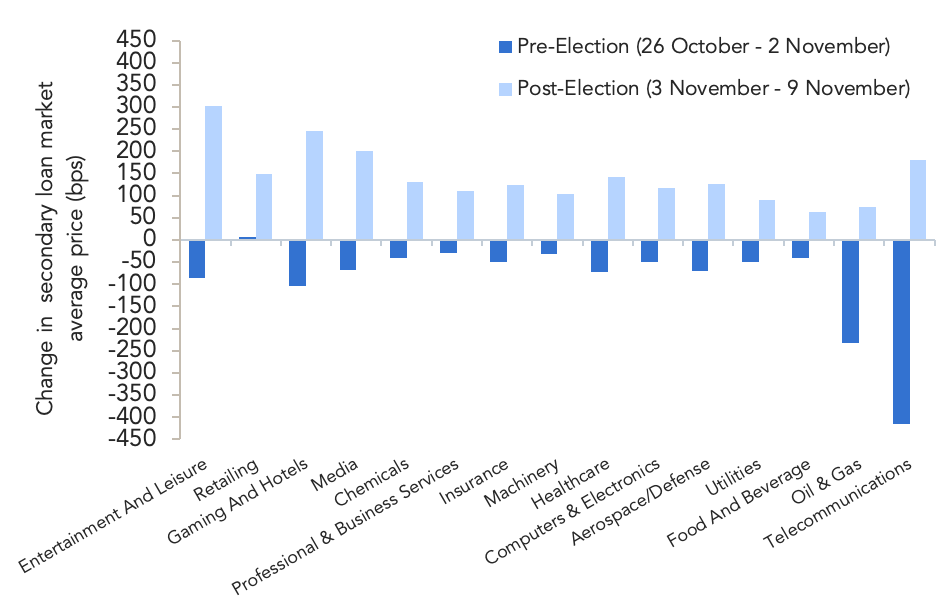
Leveraged loan and high yield bond secondary markets saw an uptick in volatility ahead of the US General Election, with term loans posting a 61bps decline in weighted average bids in the 26 October to 2 November time frame and high yield bonds losing roughly 100bps over the same period.
This trend was reversed as optimism took hold of markets following Election Day in the US, and positive news on a potential coronavirus (COVID-19) vaccine from Pfizer sent equity markets soaring on 9 November, with the Dow Jones ending the day up over 800 points, or approximately 3%. During this time, loans gained 1.4 points while bonds surged over three points higher on average.
Average loan bids currently stand at 93.84, gaining 148bps this month and representing a 17.7-point improvement from the market lows of March. In turn, the share of loans bid in the 95-plus area is now at 78% and the par-plus share has improved to 4% as of 17 November, reflecting the significant rebound since the March lows of 3% and 0%, respectively.
The news of a potential vaccine was warmly welcomed, with some industries standing to benefit to a greater degree, as evidenced by the larger than average price gains in the entertainment & leisure sector (217bps net gain in the 26 October to 9 November time period), retailing (+155bps), gaming and hotels (+143bps) and media (+133bps). Each of these industries was heavily impacted by the pandemic and resultant stay-at-home measures put in place to curtail its spread. As hopes for widespread vaccination by mid-2021 have gained steam, so too have prices of term loans for borrowers operating in these affected sectors.
At the other end of the spectrum, industries such as oil & gas (236bps net loss) and telecom (158bps net loss) declined over the 26 October to 9 November timeframe as pre-election losses outpaced post-election gains.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
