


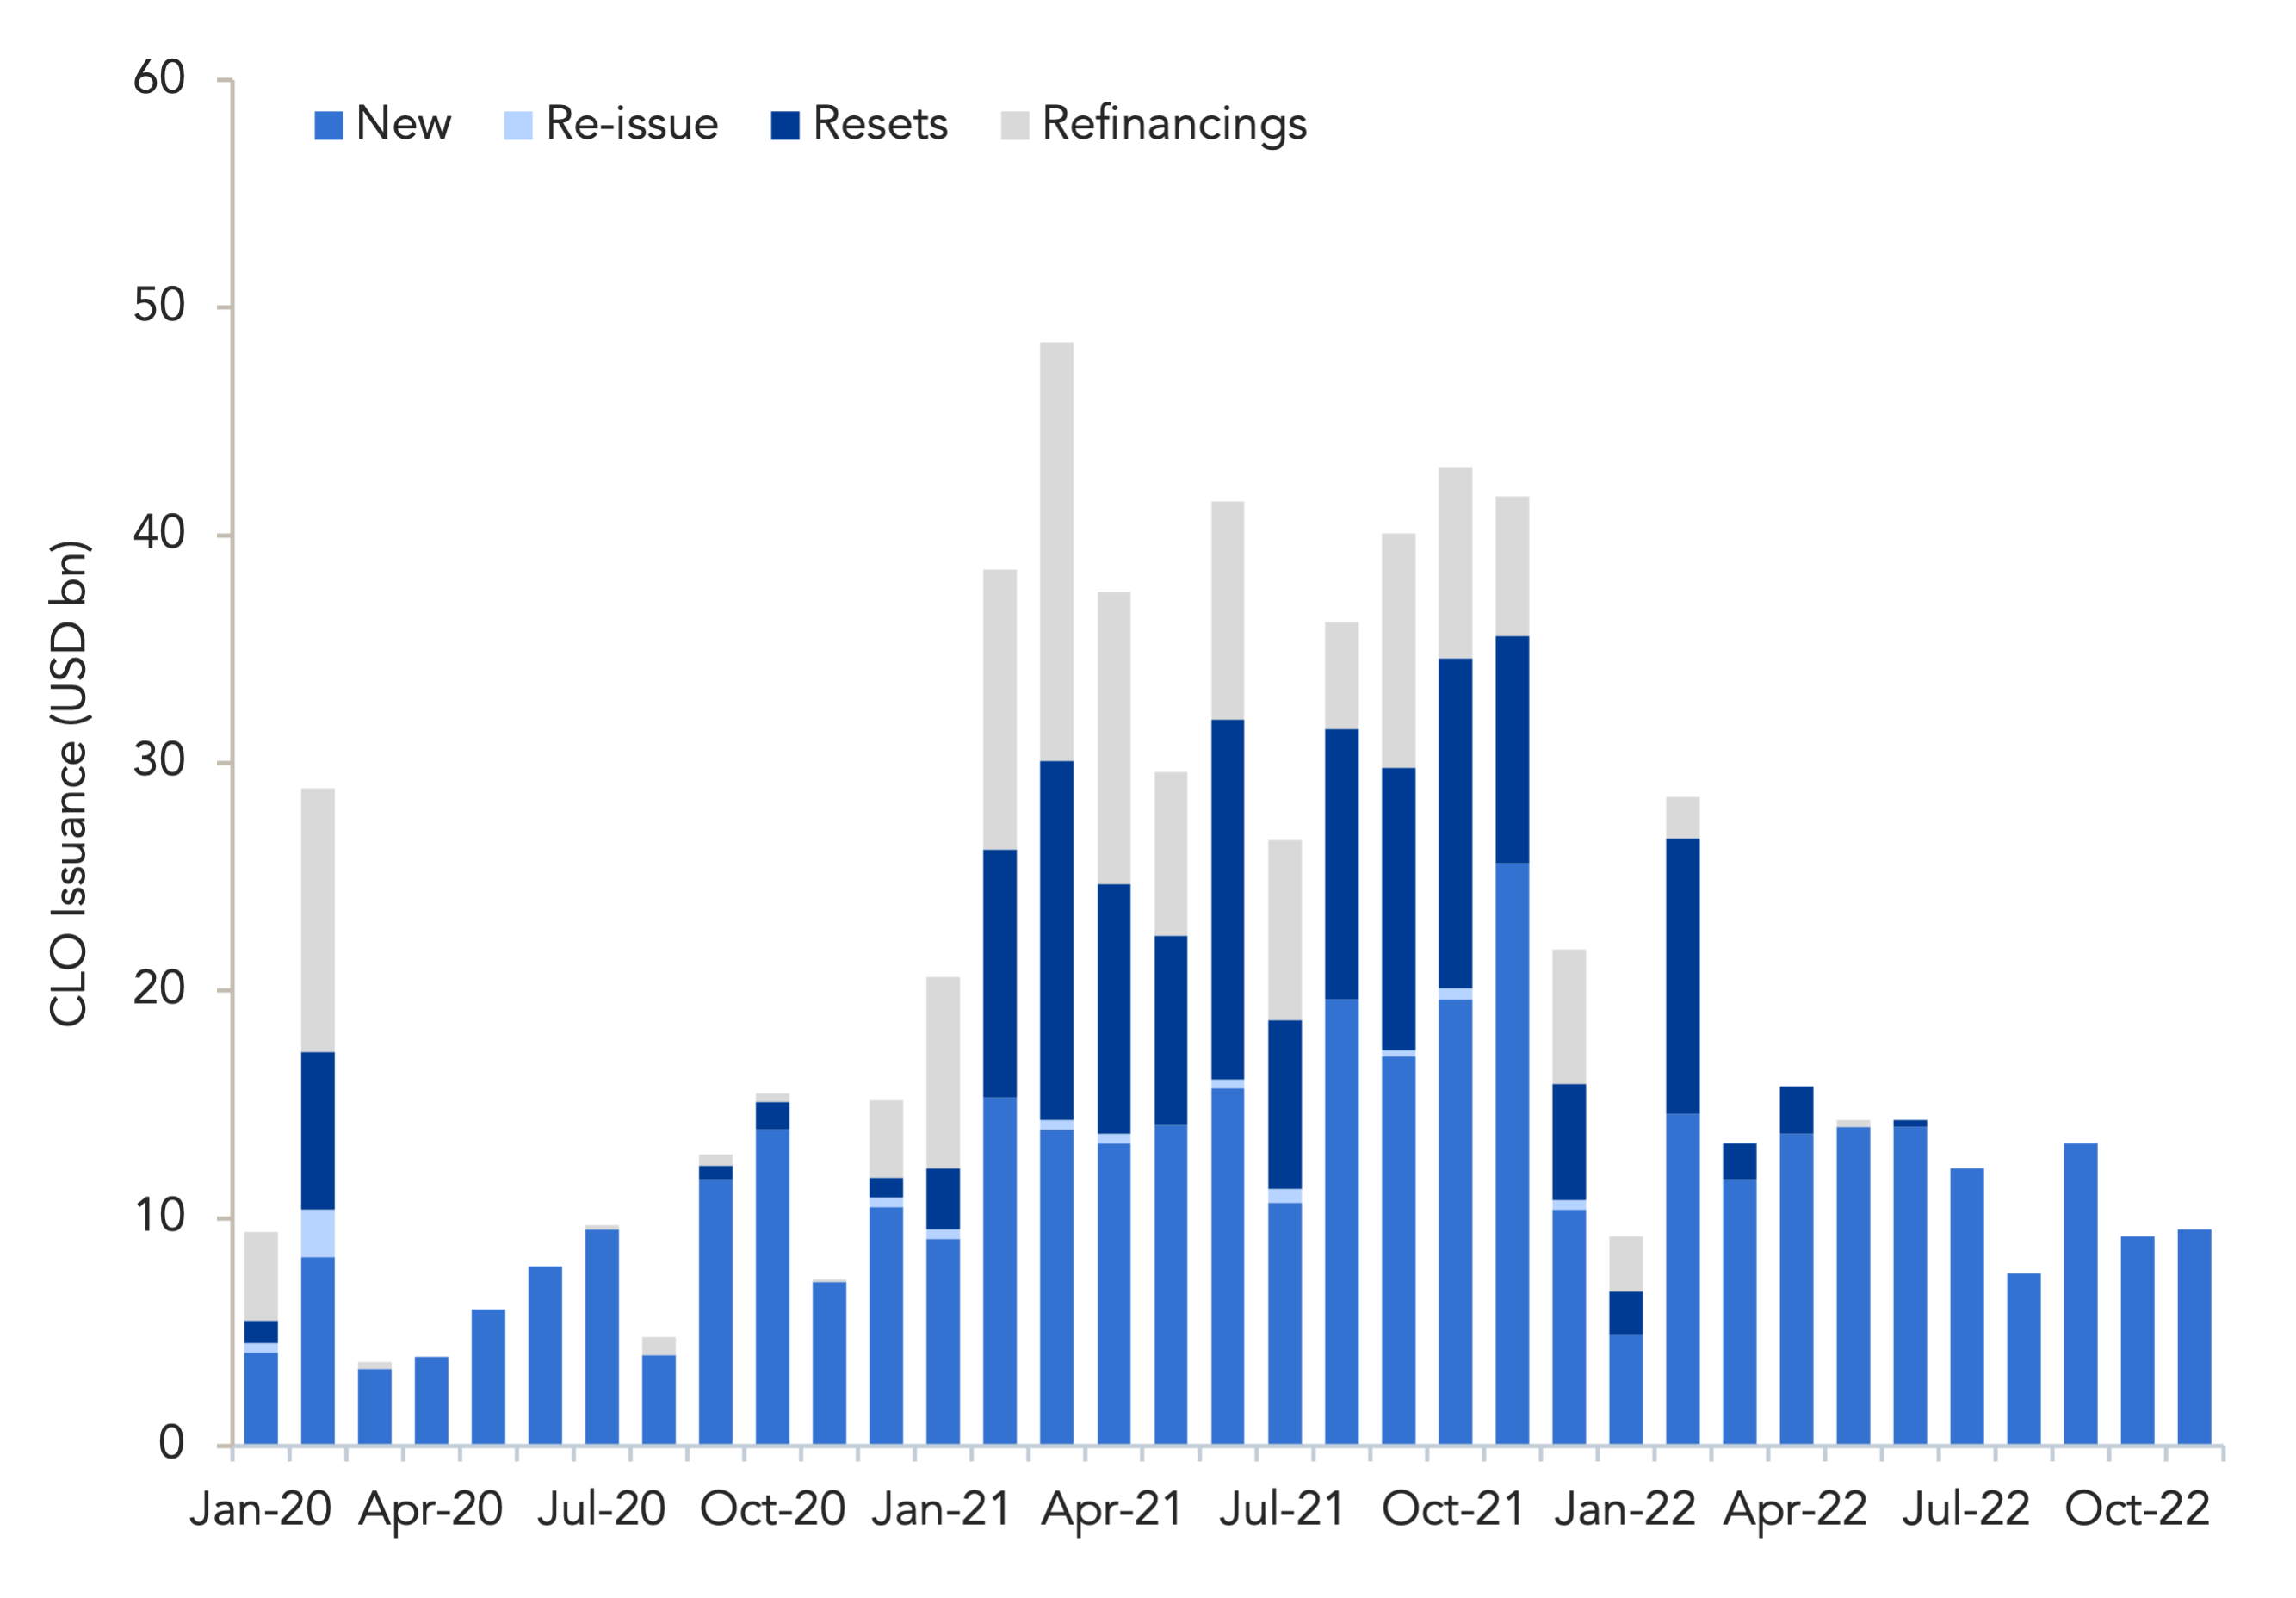
Source: Creditflux, Debtwire Par
New CLO (collateralized loan obligation) issuance has held up well amid a backdrop of challenges in the leveraged loan market this year ranging from persistently high levels of inflation, to the ongoing war in Ukraine and rising interest rates. At USD 124.7bn through November, new CLO issuance has slipped 28% from this time last year, compared to the institutional leveraged loan market where issuance has deteriorated 70% year over year.
Notably, nearly all new CLO issuance since the onset of the coronavirus (COVID-19) pandemic has been issued with with a reinvestment period of two years or less – this year, the average duration of a new CLO is only 1.8 years. During 2020, amid historic support from the Federal Reserve, USD 90.3bn of new CLOs priced with an average life of just 1.32 years. In 2019, the average duration of a new CLO issue was 4.62 years – more in line with a typical CLO structure, which often carry a reinvestment period of five years.
Refinancing and reset volumes jumped in 2021 amid a backdrop of rebounding secondary markets, cheap debt and investor optimism, sending volumes soaring to USD 111.8bn and USD 125.8bn, respectively. All the while, short-dated new CLO’s continued to print at a rapid clip, totalling USD 184.4bn in 2021, with an average life of 2 years.
So far this year, only USD 4.4bn of refinancings and USD 17.9bn in CLO resets have priced as the market rally has faded and rising interest rates drive up the cost of debt and eat into arbitrage spreads, leaving a substantial amount of CLOs issued over the prior two years approaching the end of their reinvestment period. In better times, managers might opt to refinance their deals, extending their reinvestment period out several years, however, with the debt markets currently priced at historically high levels, we have not seen a CLO refinancing since May.
If volatility continues, and a wave of CLOs are unable to refinance and cross into the post-reinvestment phase, liquidity in the loan secondary market could further dry up as the biggest buyer of loans is forced to the sidelines.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
