


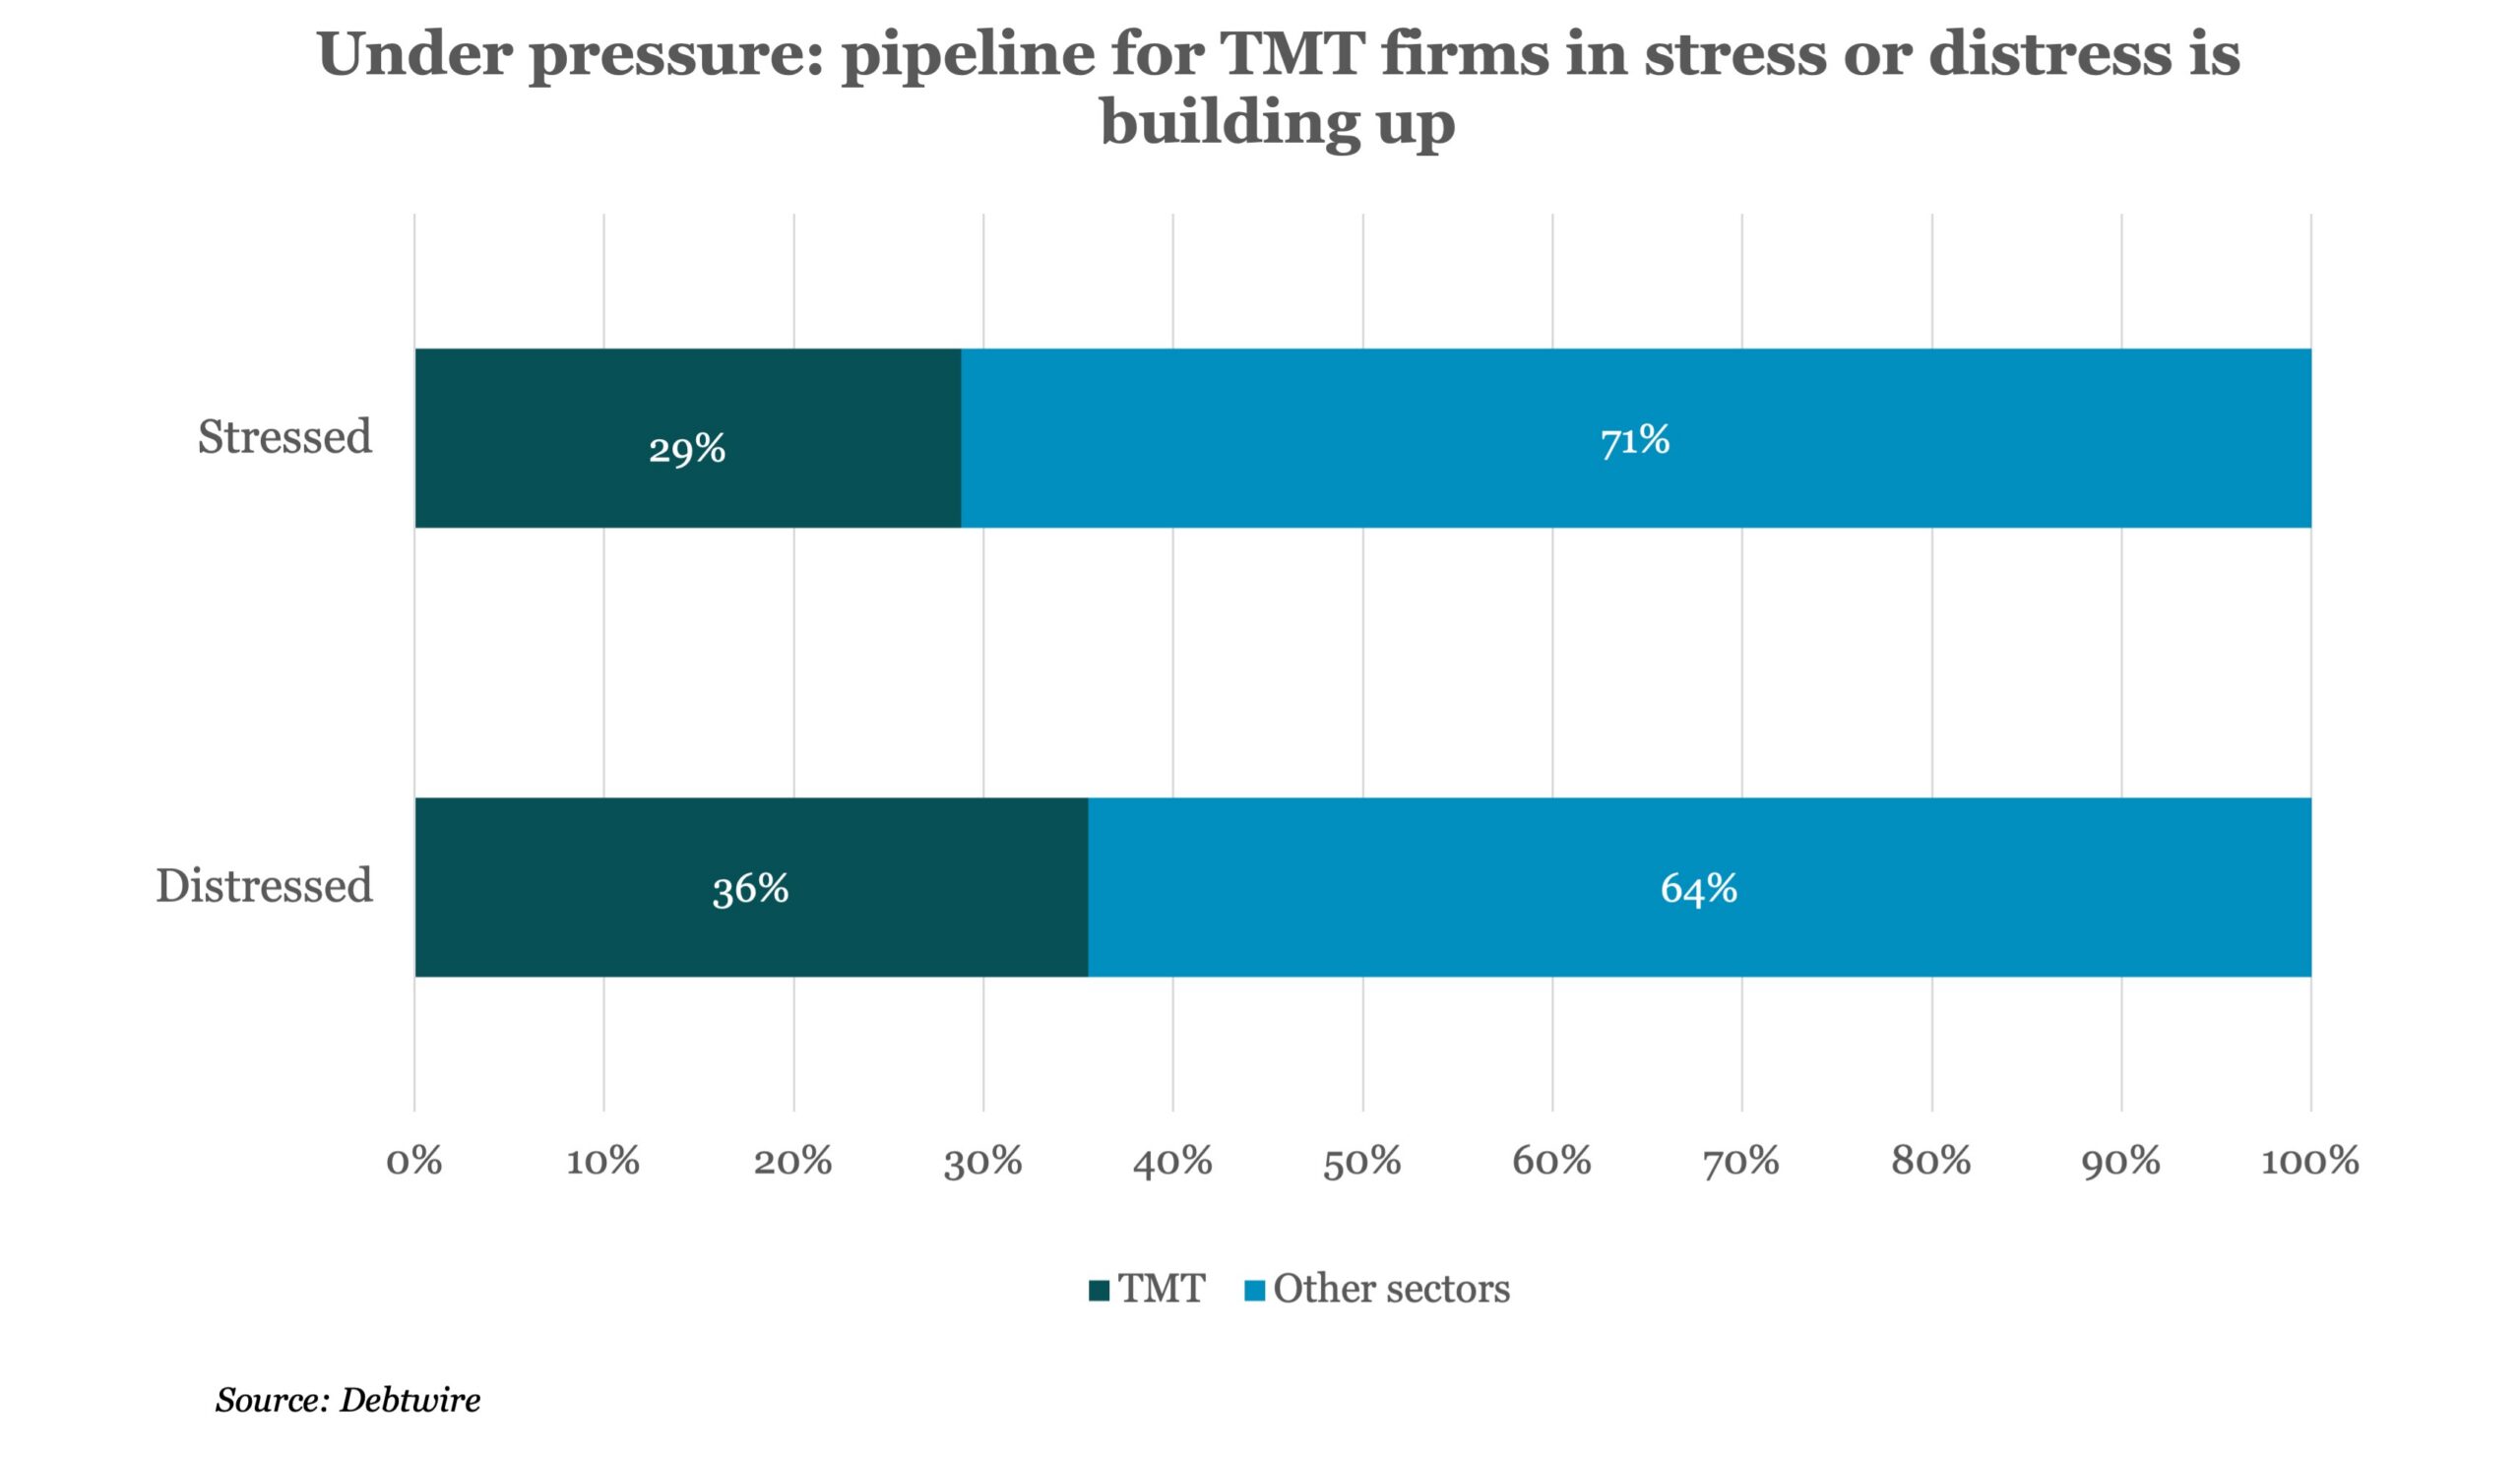
Since 1Q23, the number of bankruptcy applications from TMT firms has been relatively moderate. However, according to Likely-To-Distress (LTD) rankings powered by Debtwire’s NextGen data, there are currently 23 companies in distress and some 57 more in the stressed universe, all facing issues with liquidity, revenue and/or debt servicing. This is a significant number, and TMT businesses currently represent 36% of all companies in our NextGen’s distressed universe and 29% of the stressed universe. While the situation for some may improve going forward and firms could ramp up cash generation, the coming year is likely to be challenging for many in the sector.
The total debt of the 23 companies in Debtwire’s NextGen distressed universe is just shy of USD 60bn, of which USD 23bn is attributed to a single company, EchoStar. This satellite giant completed the acquisition of broadcaster DISH Network on 31 December 2023 in the hope of building up its 5G network, while financing operations using its pay-TV segment. However, on 1 March, the company announced its FY23 financial results, in which it reported an operating income before depreciation and amortization loss of USD 370m and an ongoing decline in subscriber numbers. Following the transaction, Moody’s assigned the merged company a Caa2 rating after its consolidated leverage rose to around 8.6x and is expected to continue rising to 10.9x and 11.7x by end-2024 and end-2025, respectively. At the same time, 5G wireless infrastructure is particularly capital-intensive and expenses at the DISH segment are likely to increase further. EchoStar acknowledged insufficient liquidity in its going concern warning in February. Also in February, the company launched an exchange offer for its convertible and unsecured notes, but later pulled the action after its lenders opposed the offer.
Nevertheless, EchoStar is only one example of an over-levered company in distressed universe that is likely to default. It appears only a matter of time until several more companies from the universe transition to the restructuring pool, as most of them face upcoming maturities that need either repayment amid very tight liquidity or refinancing at unfavourable terms.
For access to our comprehensive news, analysis and data on the global loan and bond markets, please subscribe to Debtwire.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
