


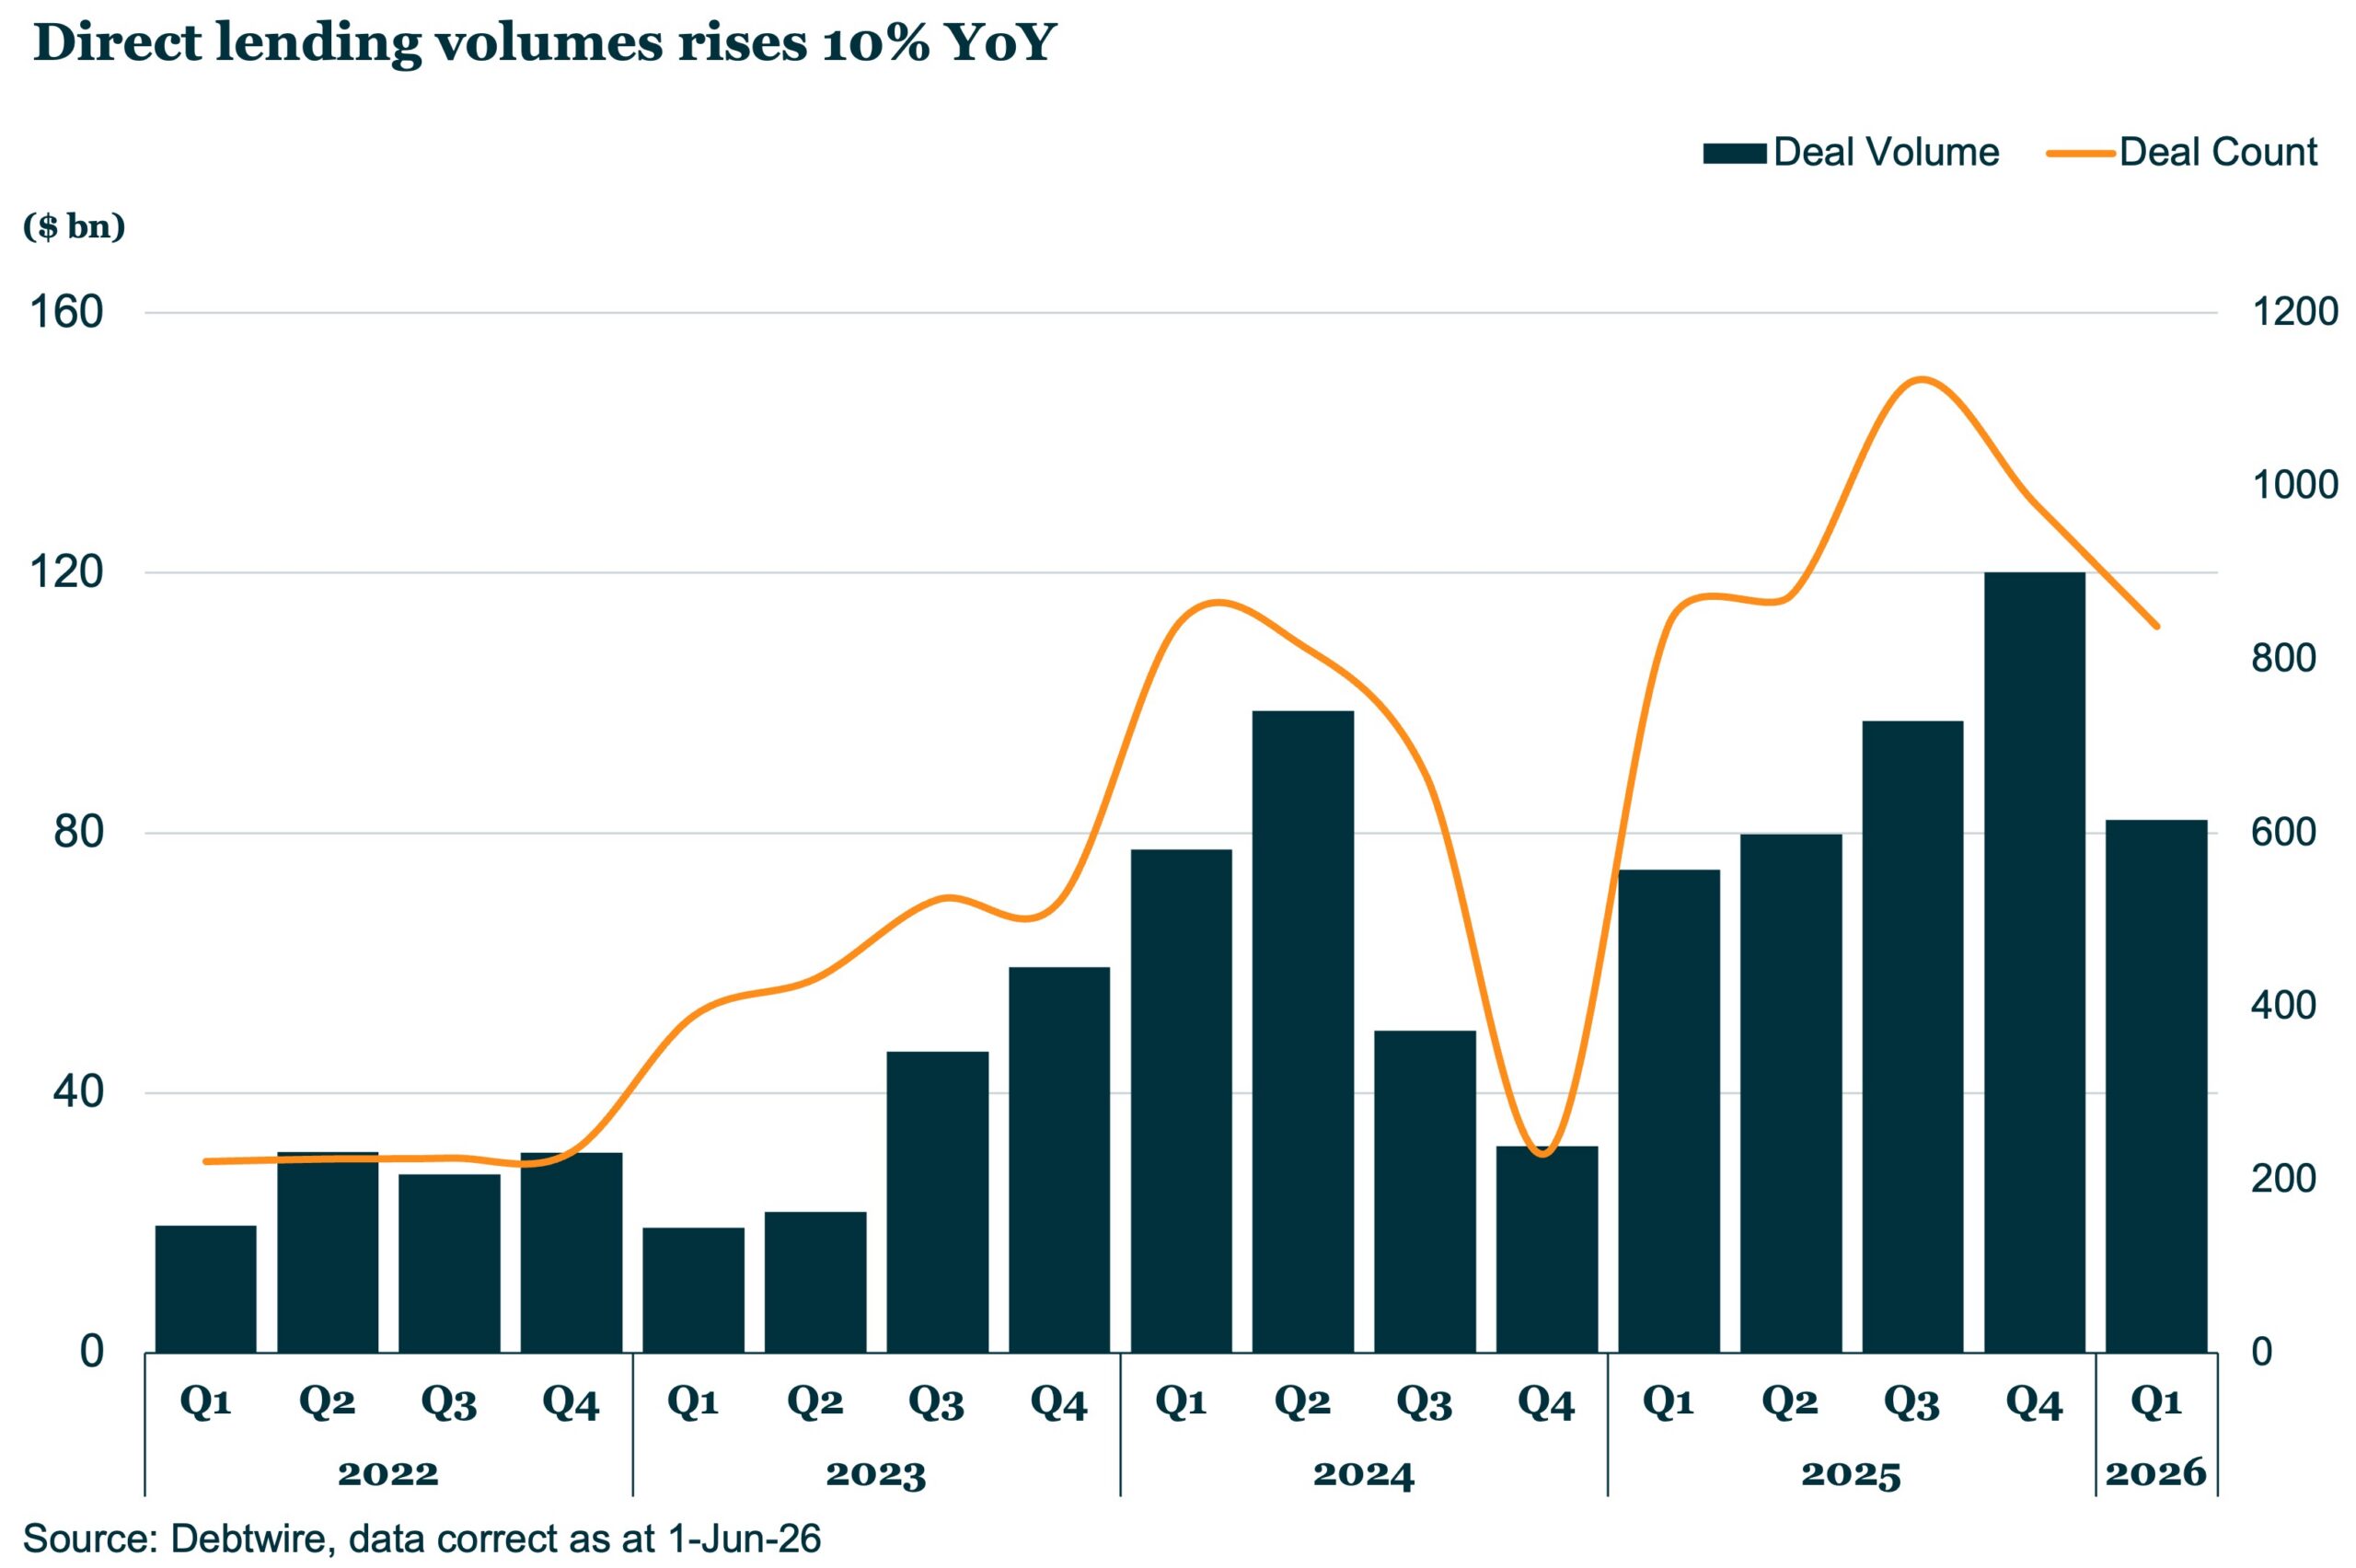
Despite negative headlines around private credit at the start of 2026, including panic redemption requests from retail investors, direct lending volumes rose 10% year-over-year (YoY) to USD 82bn in 1Q26 from USD 74bn in 1Q25, according to Debtwire data. This marked the strongest first-quarter volume on record. By contrast, institutional leveraged loan volumes dropped 36% over the same period, falling from USD 366bn in 1Q25 to USD 232bn in 1Q26.
Although activity saw an increase YoY, direct lending volumes saw a 32% decline quarter-over-quarter (QoQ) falling from USD 120bn in 4Q25 – the highest quarterly direct lending volume, according to Debtwire data.
LBOs rise while refinancing slides
Sponsor-backed transactions dominated direct lending volumes, accounting for 88% of total activity. LBOs remained the largest use of proceeds in 1Q26, with USD 26.1bn in volume, or 32% of the total. M&A excluding LBOs contributed USD 17bn, or 21% of volume. Sponsor-backed deals accounted for 99% total M&A activity, while non-sponsored borrowers focused on general corporate purposes and refinancing transactions.
Notable LBO transactions included USD 5.1bn in private debt financing for Thoma Bravo’s buyout of logistics company WWEX Group, and USD 2.2bn of private debt supporting HgCapital’s USD 6.4bn leveraged buyout of finance software management firm OneStream.
Refinancing, which typically represents more than one-third of direct lending volume, declined 57% QoQ to USD 15bn in 1Q26 from USD 35.3bn in 4Q25. The healthcare sector saw an especially sharp pullback, with refinancing volumes falling to USD 600m in 1Q26 from USD 6.7bn in 4Q25.
Technology declines
Technology led overall sector volumes, accounting for USD 16bn, or 20% of total direct lending activity in 1Q26. Industrials followed with USD 13.8bn, while healthcare ranked a close third at USD 11.9bn.
Despite remaining the largest sector, technology volumes declined sharply, falling 66% QoQ from USD 47bn in 4Q25 and 29% YoY from USD 22.7bn in 1Q25. The so-called “SaaSpocalypse,” which triggered a sell-off of software loans in the secondary market and muted primary issuance earlier this year after the launch of new AI tools, also weighed on direct lending activity, given the market’s relatively higher exposure to the tech sector. Tech, which has accounted for over 30% direct lending activity on average over the past three years, saw its share decline to 20% in 1Q26.
Despite the drop in volumes, investors and market participants at Debtwire’s Private Credit Conference this year emphasized that the sector’s long-term outlook remains strong, with concerns seen as disproportionately overstated. Panelists centered around the view of an increase in scrutiny around tech deals going forward, while overall sentiment remains constructive for the sector in the near term.
Outlook
Despite a challenging environment in 1Q26, including concerns around AI-driven disruption and conflict in the Middle East, direct lending volumes stayed steady. While the impact of AI on software companies weighed on sentiment, participants at Debtwire’s Private Credit Conference noted that AI is likely to affect all sectors over time, not just technology. They emphasized that AI is also driving significant infrastructure-related investment opportunities and viewed its long-term upside as outweighing the downside.
Participants also suggested that 2026 could mirror 2025, when tariff-related uncertainty affected the market early in the year before activity picked up in later quarters. As confidence strengthened and dealmaking recovered, direct lending volumes rose QoQ, reaching their highest quarterly level of the year in 4Q25.
For access to our comprehensive news, analysis and data on the global loan and bond markets, please subscribe to Debtwire.
(Past performance is no guarantee of future results.)


Latest news
US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
