


While payment-in-kind (PIK) loans are uncommon in the broadly syndicated loan market, where cash interest payments are standard, direct lenders have consistently used them to offer cash flow flexibility to borrowers.
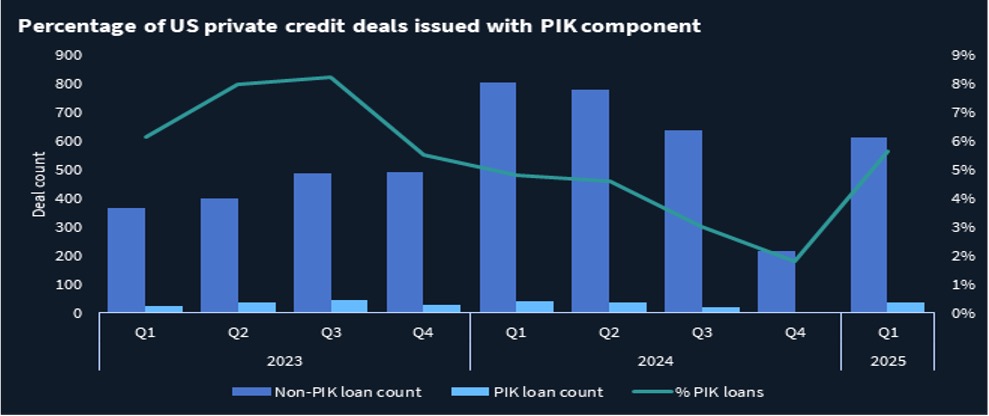
In 1Q25, 37 out of 640 direct lending deals, or about 6%, featured a PIK component, according to Debtwire data. This marked a slight increase from 2024, when PIK loans made up for 4% of all deals, and approached 2023 levels, where 7% of direct lending loans included a PIK option.
According to Jason Kyrwood, Head of the Finance Practice at Davis Polk, the prevalence of PIK loans may not necessarily be increasing in absolute terms, but their strategic value remains significant.
“I don’t know that we’re seeing more or less PIK,” Kyrwood said. “It is one of the key competitive advantages that private credit firms have, so I think they continue to use that as a way to compete for market share with banks.”
A private credit lender noted that this loan type is being seen more commonly in both refinancings and as a war chest for new acquisitions.
“On the junior capital side, I am seeing a lot of structured PIK notes in the market,” the lender said. “Sponsors are looking for a junior capital piece to pay down senior debt or use as dry powder for acquisitions, and many of the deals we’re doing right now have that.”
“For underperforming companies, you have to be careful that it’s not rescue capital,” the private lender added. “This is different from a bridge loan because it’s more permanent, and it’ll be for businesses that the sponsor wants to own for a few years. The PIK will give them some relief if the company is over-levered from the senior debt perspective.”
However, where PIK features are the most valuable is in refinancing scenarios rather than in new acquisition financings, which are typically fully levered and structured with a deleveraging path.
“It’s most useful in circumstances where you have an increasing interest rate environment, and that’s going to put pressure on the cash flows of the company,” Kyrwood said. “Having the option to PIK can buy the company some time, and that will often come up in restructuring or refinancing context rather than in an acquisition context. Even in the acquisition context, though, there are some types of transactions that may be structured at the outset with a PIK election, such as lower-EBITDA software or recurring revenue deals.”
Kyrwood also noted that PIK loans can offer a liquidity buffer for companies with limited cash flow or aggressive growth plans.
“PIK loans can be useful for low EBITDA or growth companies that experience or expect tight liquidity at different points during the life of the facility or want the option to preserve liquidity to make future acquisitions or investments,” Kyrwood said.
For access to our comprehensive news, analysis and data on the global loan and bond markets, please subscribe to Debtwire.
(Past performance is no guarantee of future results.)



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.