


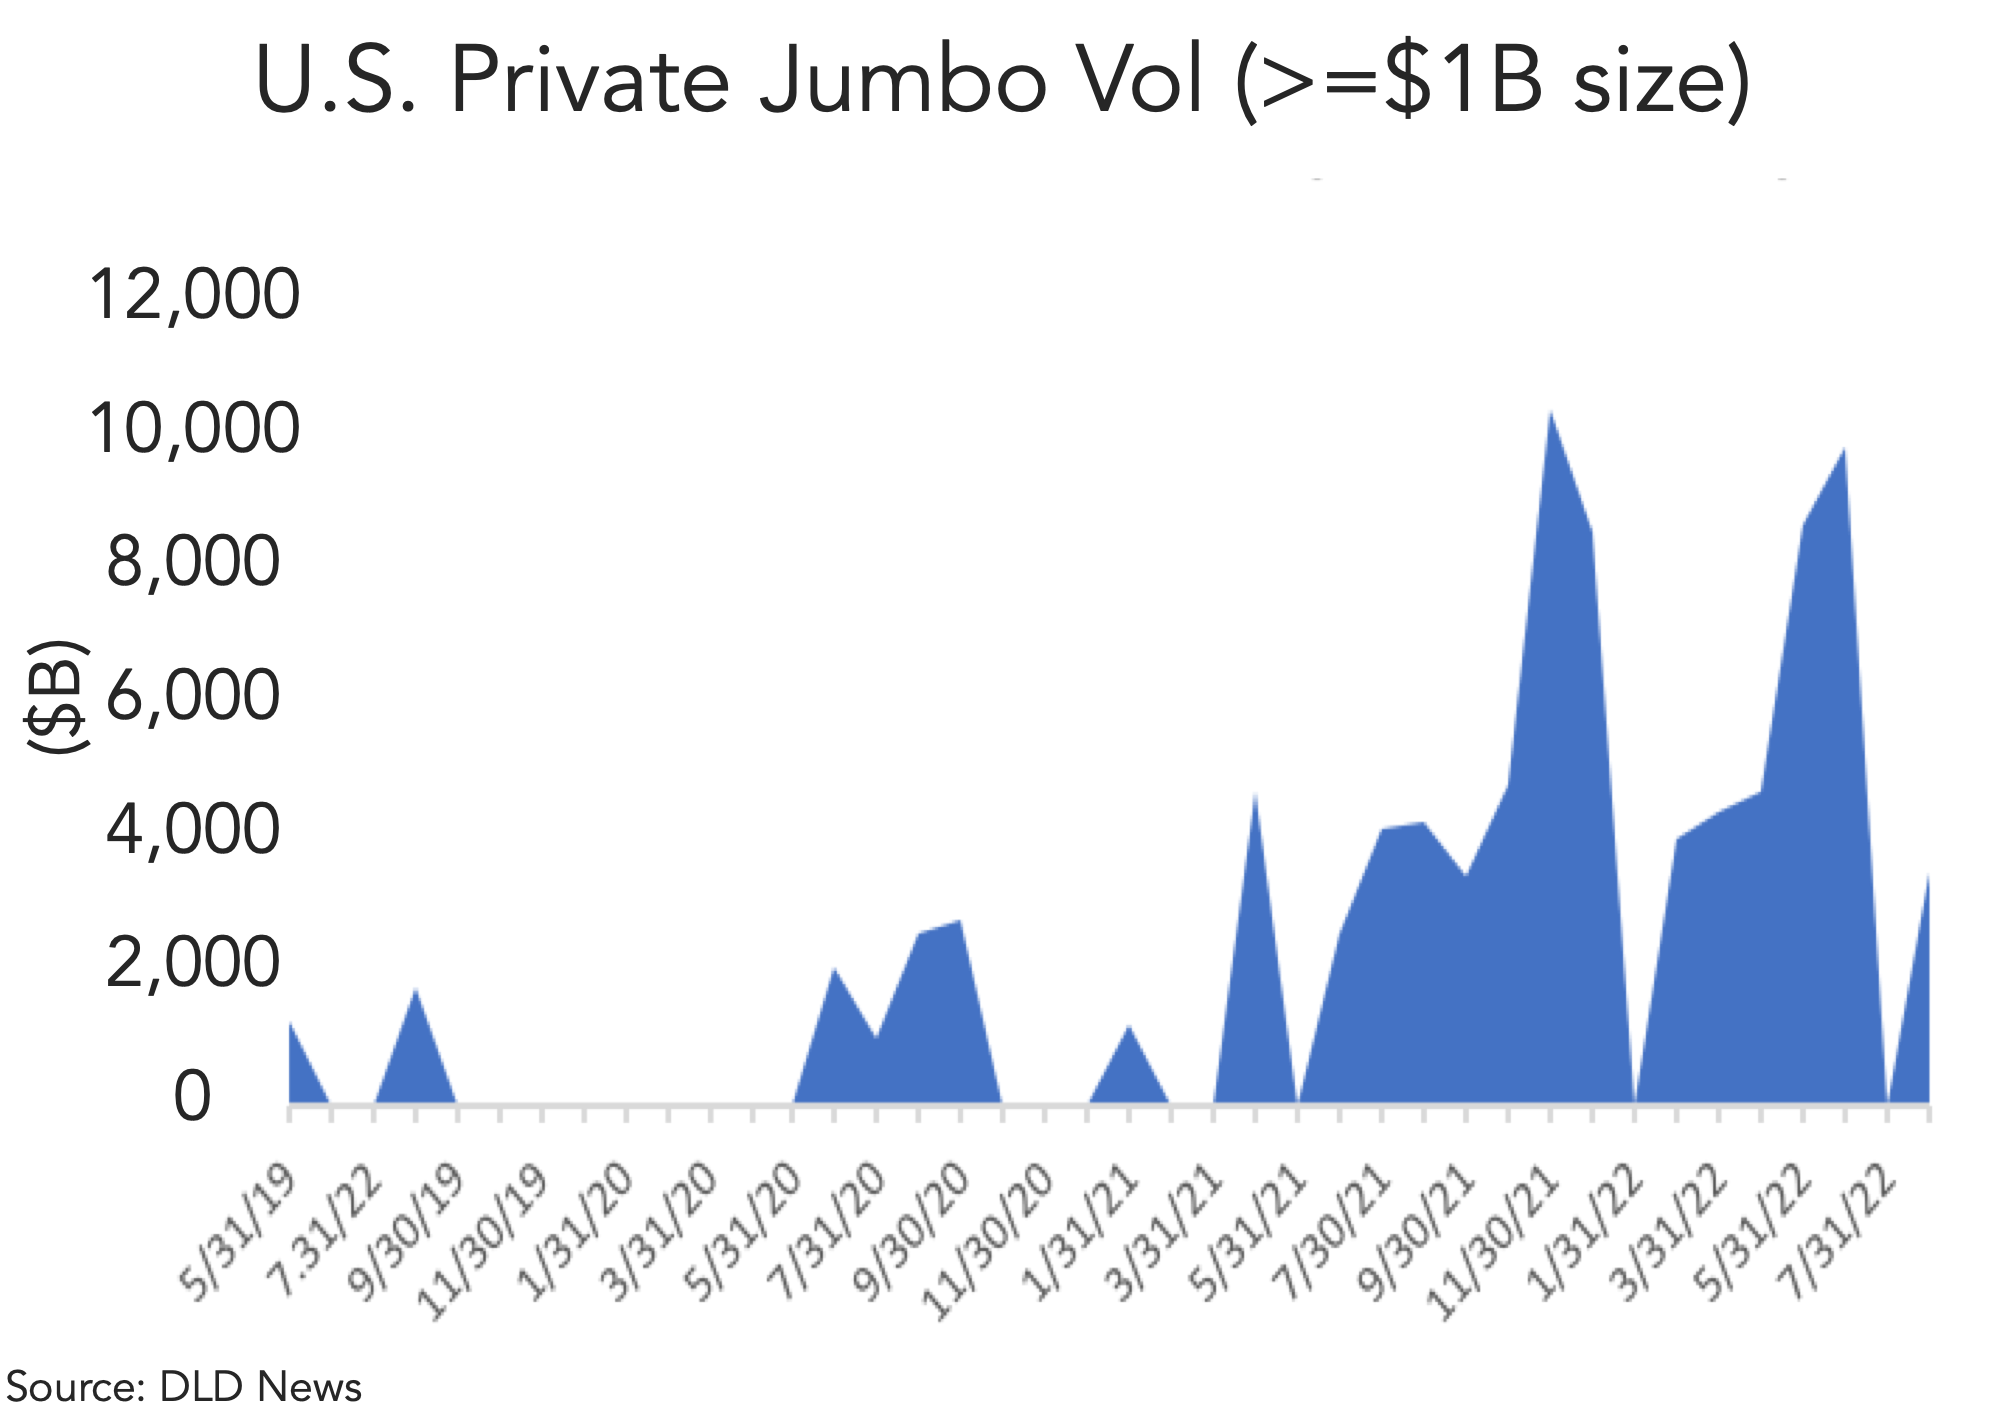
Private jumbo financings (>=$1B) have the advantage under current market conditions, but deals going forward are expected to trend smaller for the first time since DLD started tracking these credits in September 2019.
There are several issues affecting capacity: 1) managers invested much of last year’s record capital in the first half of 2022; 2) rising rates have killed refinancings, and therefore repayments are no longer available for redeployment, and 3) inflation and recession fears have made fundraising difficult.
At the start of the year, capacity for a single private financing was estimated at $9-10 billion. Today, it’s less than half that. A $500 million ticket two months ago is now $250 million.
There were no new jumbo loans in July, only incremental financing for existing borrowers including PCF Insurance, Compusoft + 2020 and Medallia. July’s slump followed two months of heavy volume, with May generating $8.6 billion, and June recording $9.8 billion. The monthly record holder remains November 2021, with $10.3 billion.
Zendesk’s record setting $5 billion credit last quarter looks like it’ll hold that title for the rest of the year, in contrast to the stream of megatranche loans that topped one another over the past 12 months.
Year to date, jumbo volume stands at $35 billion, while the overall total has reached $90 billion and includes one new $2.5 billion recurring revenue deal that surfaced this month.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
