


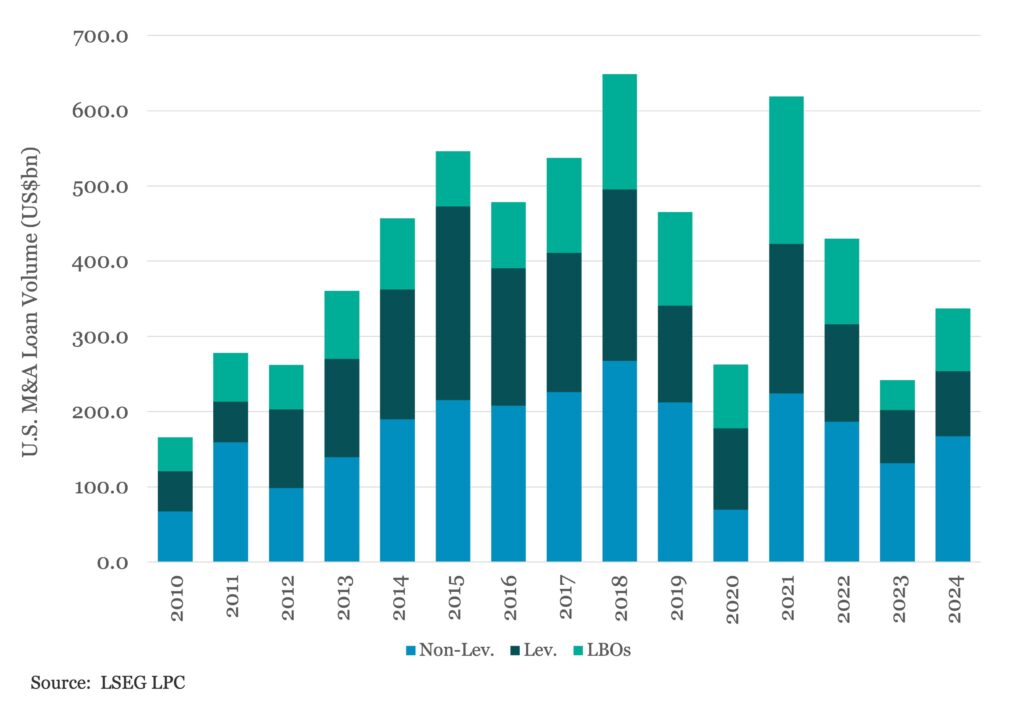
US lenders committed to US$337.5bn in M&A loan volume in 2024, an increase of 40% compared to the 13 year low marked by 2023 totals. In the investment grade space, lenders raised over US$153bn in loan credits to back acquisition deals, up 27% year over year, as a flurry of large, transformative undertakings came to market, to supplement smaller corporate tack on transactions. Among leveraged issuers – despite lender hopes – any developing M&A pipeline was liimited at best. At US$84bn, 2024 buyout volume was over two times year ago levels (which at less than US$40bn, marked a 20 year low) but only represented a thin 8% of total sponsored loan volume for the year, the smallest pro rata share on record.


Latest news
Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.
Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…