


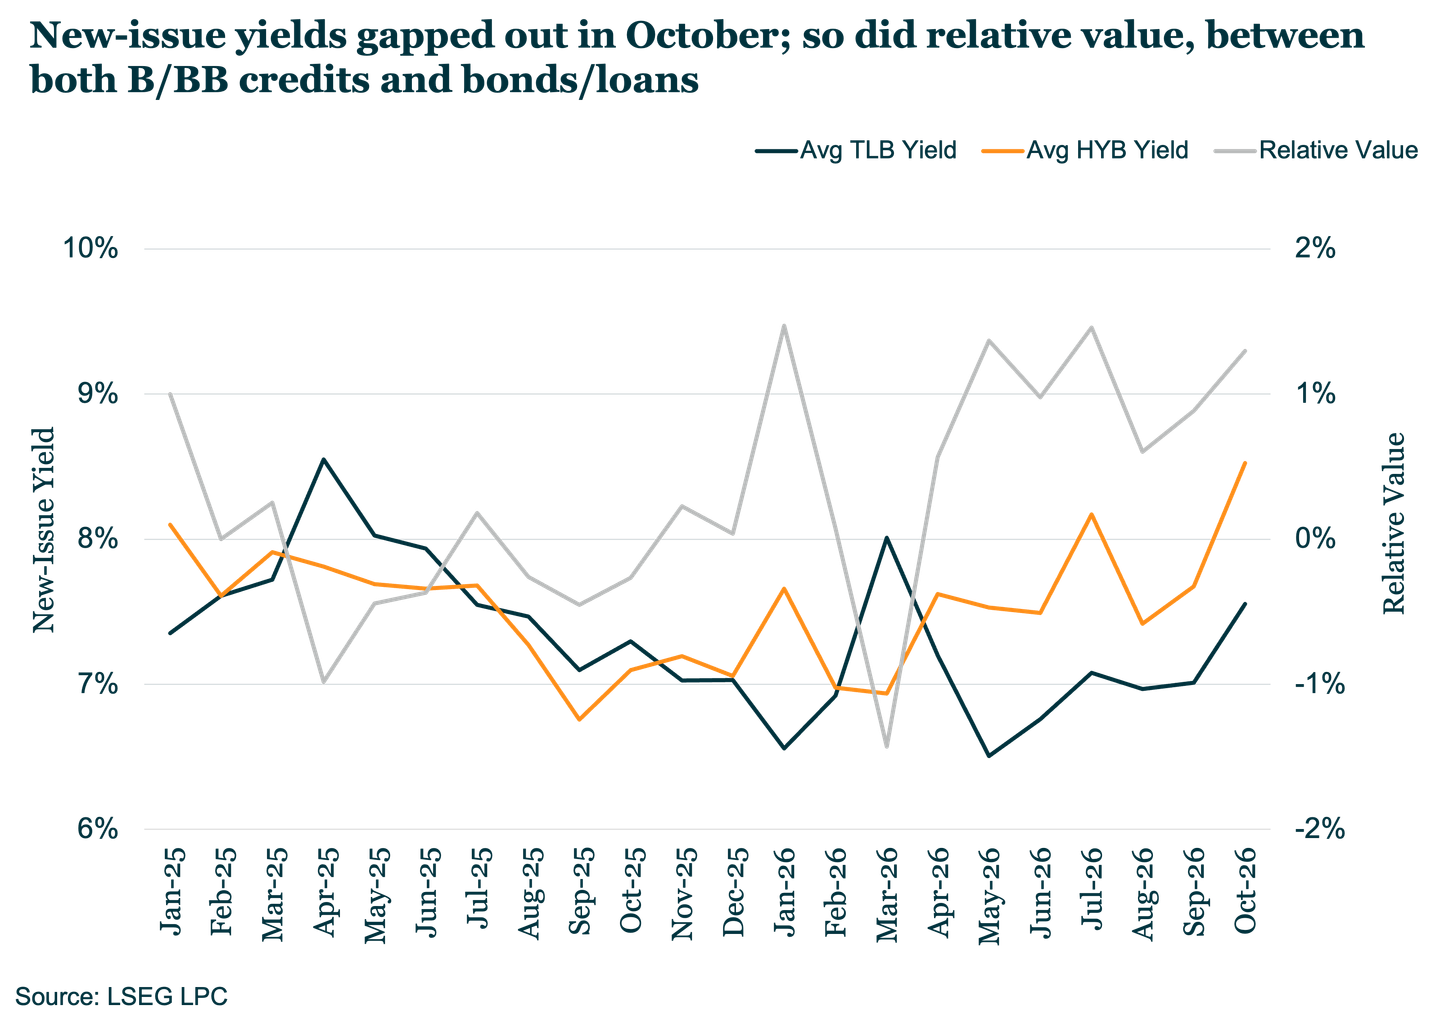
We noted in our monthly leveraged loan coverage how new-issue yields remained elevated through October, with institutional loan yields averaging 7.5% (highest since March) and high-yield bonds printing above 8.5% (widest since November ’23). We also saw the pricing premium for single-B loan issuers (relative to double-Bs) return to 160bp after briefly contracting to 100bp in September, not to mention a similar move in relative value between fixed- and floating-rate debt. Bond yields gapped out disproportionately wider than loan pricing, pushing that bond yield premium to about 100bp, an elevated but normalized level that bonds had already touched in January, May, and July of this year. Although highly situational, we have also seen some better-quality issuers raise floating-rate term debt with a concurrent fixed-rate swap, which offered a synthetic but cheaper fixed-rate alternative to issuing a bond outright. One particular issuer utilized the loan proceeds to redeem and refinance pari passu bonds, pocketing more than 50bp of run-rate cost savings in the process.


Latest news
U.S. Leveraged Finance M&A Rebounds as Credit Quality Pressures Emerge in 3Q26
North American leveraged finance gross issuance moderated in 3Q26 as refinancing activity declined and transaction-related financing increased, according to a new Fitch Ratings report.
Is direct lending losing its lustre?
Our Investor Perspectives survey shows asset-backed finance gaining in popularity as LPs reconsider where to allocate their dollars. The importance…
Quarterly share of PE middle-market exit count by type
US middle-market exit activity hit a bottom in Q2 but bounced back in Q3, posting 36.1% growth in count and 13.9% growth in value QoQ.