


Downward flexes dominated in October
Downward flexes continued to dominate flex activity in October. There were 21 downward price flexes on first-lien institutional term loans in October and only 8 upward flexes. Both downward and upward price flexes were down from September which recorded 28 price cuts and 12 upward price revisions. Moreover, yields have tightened so far in 4Q16 to 5.12% from 5.35% in 3Q16. Demand for the loan asset class remains robust as evidenced by inflows into bank loan retail funds and strong CLO creation, and issuers continue to take advantage of this to cut their costs via repricings and refinancings.
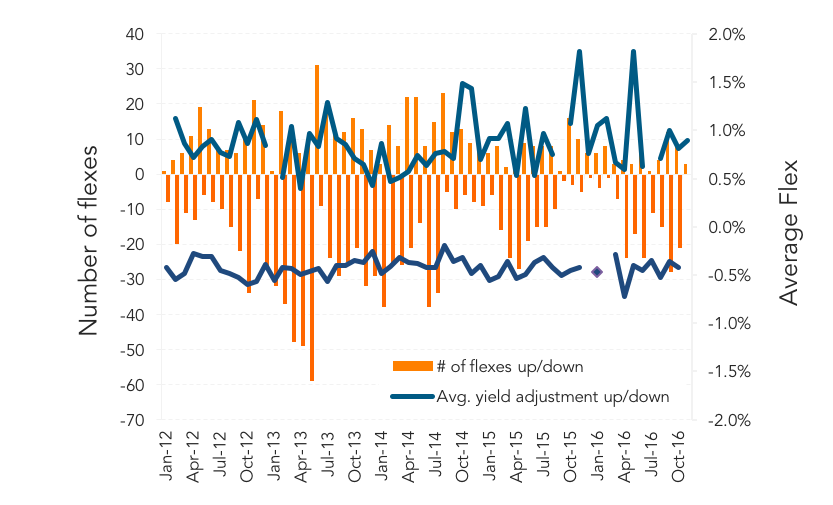
However, so far in November there have been only upward price flexes. PQ Corp. bumped up pricing on its cross-border repricing. Pricing was increased to 425bp on the dollars and 400bp on the euros from initial guidance of 375bp on both tranches. Both tranches were sold at par which was at the tighter end of the initial 99.75-par range. But even with the upward flex, the company was able to cut pricing by 50bp from the margin of the existing dollar term loan and 75bp from the existing euro loan, which both priced in April at 475bp over Euribor with a 1% floor and an OID of 99.
Contact: Diana Diquez
diana.diquez@tr.com



Latest news

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.