


Weighed by repricings, term loan B spreads begin to diverge between single-Bs and double-Bs, although relative value holds steady
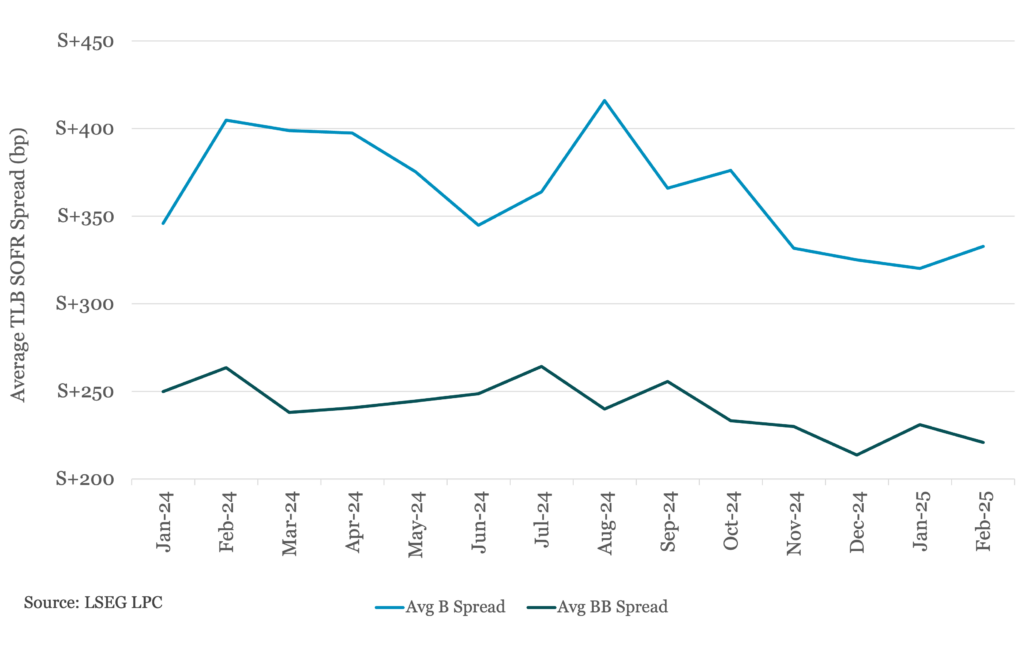
After new-issue clearing yields tightened for three consecutive months, averaging 7.3% in January and marking another fresh monthly low since May ’22, the institutional loan market may finally be showing signs of fatigue from repricings. All three yield components – spread, SOFR, and OID – contracted in January, although tightening was most evident in spreads, which shed approximately 25bp. And although single-B issuers had consistently benefited the most in recent months, extracting more than 50bp of spread savings since October while BB spreads remained essentially flat, that dynamic has reversed course so far in February. For single-B issuers, average new-issue term loan B spreads have ticked up by roughly an eighth over the past two weeks to S+333bp, while BB spreads have contracted by nearly an eighth to S+221bp. Despite the divergence in spreads, and with new-issue term loans now printing in the S+325-350 area for single-Bs versus S+225-250 area for double-Bs, relative value has remained remarkably steady, if not largely unchanged since October, at approximately 100-112bp.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
