


Despite hopes that 2016 would start off on stronger footing than 2015 closed, market volatility intensified in January. The Merrill Lynch HY Cash Pay Bond Index continued to demonstrate substantial downward pressure driven by macro volatility rooted in global growth prospects. Average bids hovered south of 86.5 by the end of last month, down from 89.16 at year end. At the same time, the supply of deals became more scarce as issuers delayed launches in the hope of greater of stability.
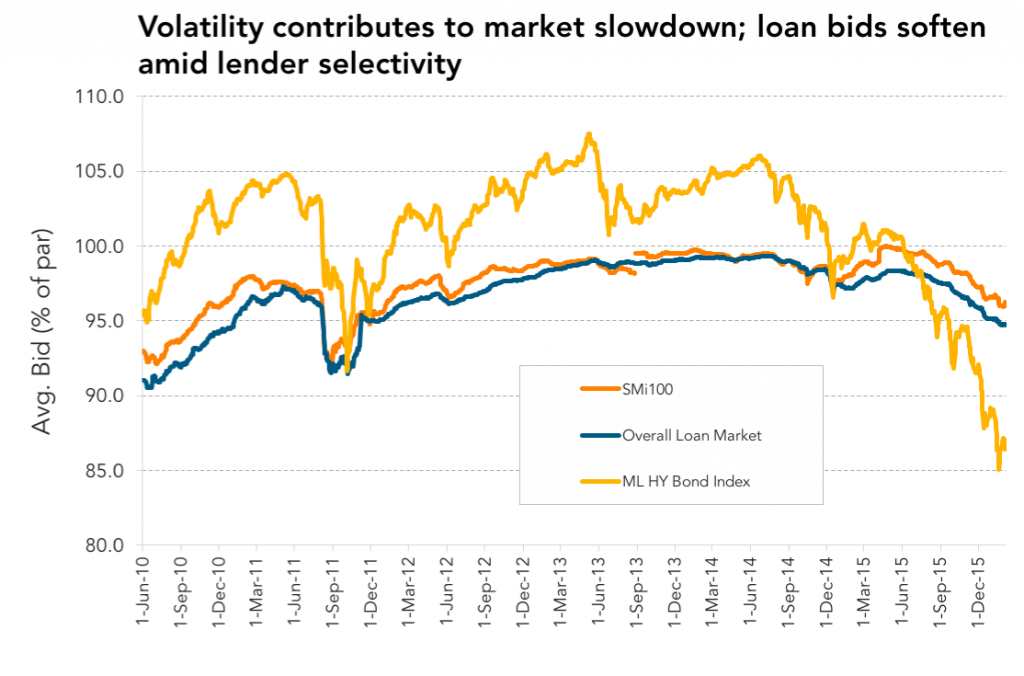 Only $6.6 billion in HY bond volume came to market in January, the slowest January since 2009. The leveraged loan market exhibited more stability but e bids continued to come in with the SMI100 average less than 96 at the end of January and the overall loan market bid at about 94.7. Overhang from 2015 deal flow has cast a long shadow on the leveraged loan calendar as investors and arrangers wait for deals that were launched, and subsequently pulled, in late 2015 to come back to market, before they look at new issuance. At the moment, the market pause raises questions around what supply will look like for the rest of the year absent some market change.
Source: LSTA/LPC MTM Pricing, BAML
Contact: Maria Dikeos
maria.dikeos@thomsonreuters.com


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
