


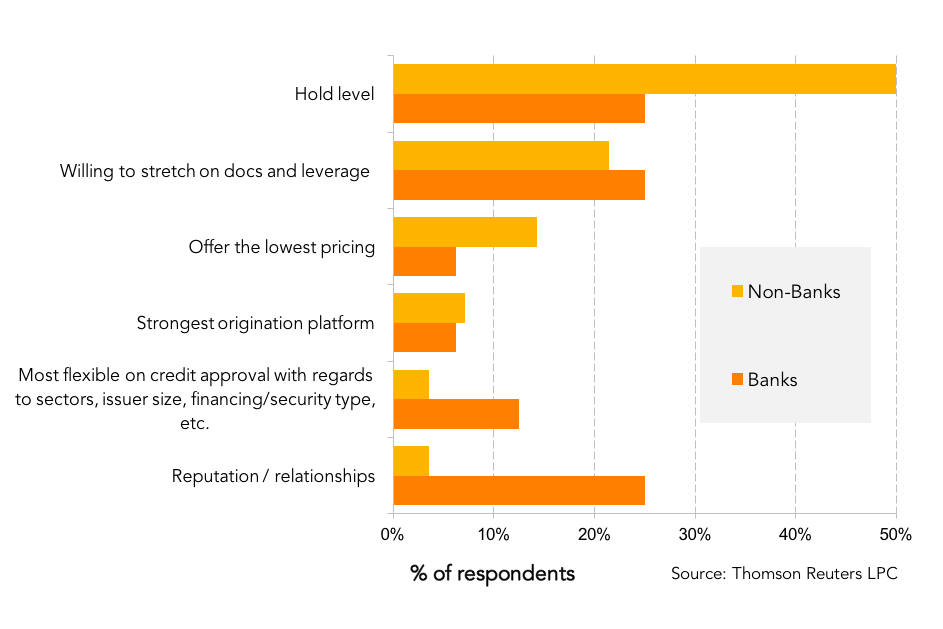
When asked to select the #1 biggest driver in helping them win deals in this increasingly competitive environment, middle market banks were mixed. According to Thomson Reuters LPC’s recent survey, one quarter said it comes down to the relationship, especially in the non-sponsored market where issuers rely heavily on that long term relationship. Perhaps more surprising, only 4% of non-banks ranked reputation and relationship as the number one factor. One quarter of banks chose willingness to stretch especially with regard to sponsors who are often asking for large corporate term sheets on smaller deals. One fifth of non-regulated lenders agreed. Still one quarter of banks said hold sizes were the most important factor and that is where banks are on the same page with non-banks, half of whom focused on hold size as the biggest differentiator. Interestingly, what used to serve as a barrier to entry especially in the sponsored market, having a strong origination platform is much less of a factor now, only chosen by 7% of non-banks and 6% of banks. Surprisingly, being able to offer the lowest pricing was only ranked by 14% of non-banks and 6% of banks. Not surprising in a market where lenders are fiercely competing, being the most flexible on credit approval with regards to sectors, issuer size, financing/security type, etc. was ranked by 13% of banks and only 4% of non-banks as the winning factor.
Register to join TRLPC’s 5th Annual Middle Market Loan Conference




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
