


In 1Q15, higher yields in the leveraged loan market were apparent in both the large corporate and institutional middle market. However, data submitted to LPC from middle market lenders for smaller club sponsored deals indicated that pricing continued to remain tight at the smaller end of the middle market. While smaller deals tend to earn a liquidity premium over larger rated institutional middle market credits, that yield boost has been non-existent for two quarters now. 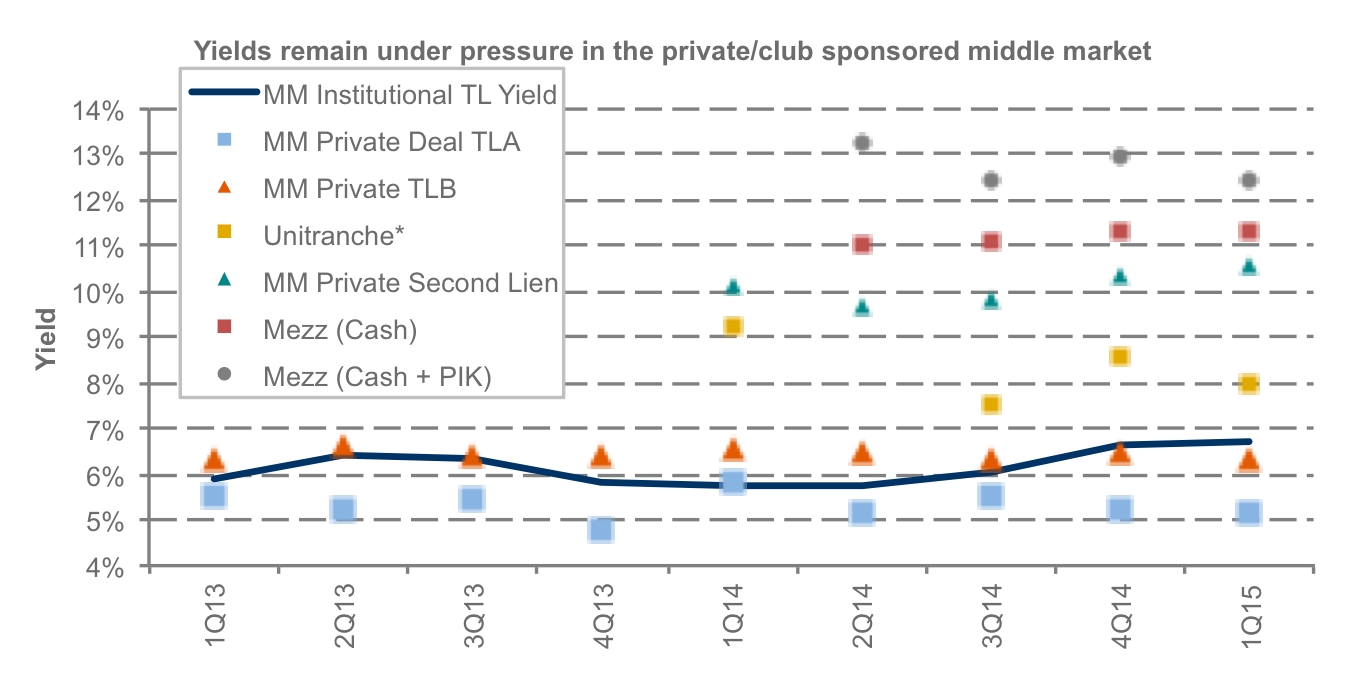 Banks searching for sponsored deals that fit the Leveraged Lending Guidance criteria drove Term Loan A yields down to 5.15% in 1Q15, from 5.25% in 4Q14 and 5.54% in 3Q14. And even investors and finance companies drove issuer yields tighter last quarter. Term loan B yields tightened to 6.31% in 1Q15, down from 6.46% in 4Q14. Smaller non-rated term loan Bs were priced 40bps lower than the institutional middle market rated deals to hit market last quarter which averaged 6.71%. Even mezzanine and unitranche yields were under pressure given the abundance of capital chasing the limited dealflow out in the market. However, second lien yields did rise last quarter, in line with the broader markets. MM private second lien yields incrased to 10.56%, from 10.34% in 4Q14 and 9.85% in 3Q14.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
