


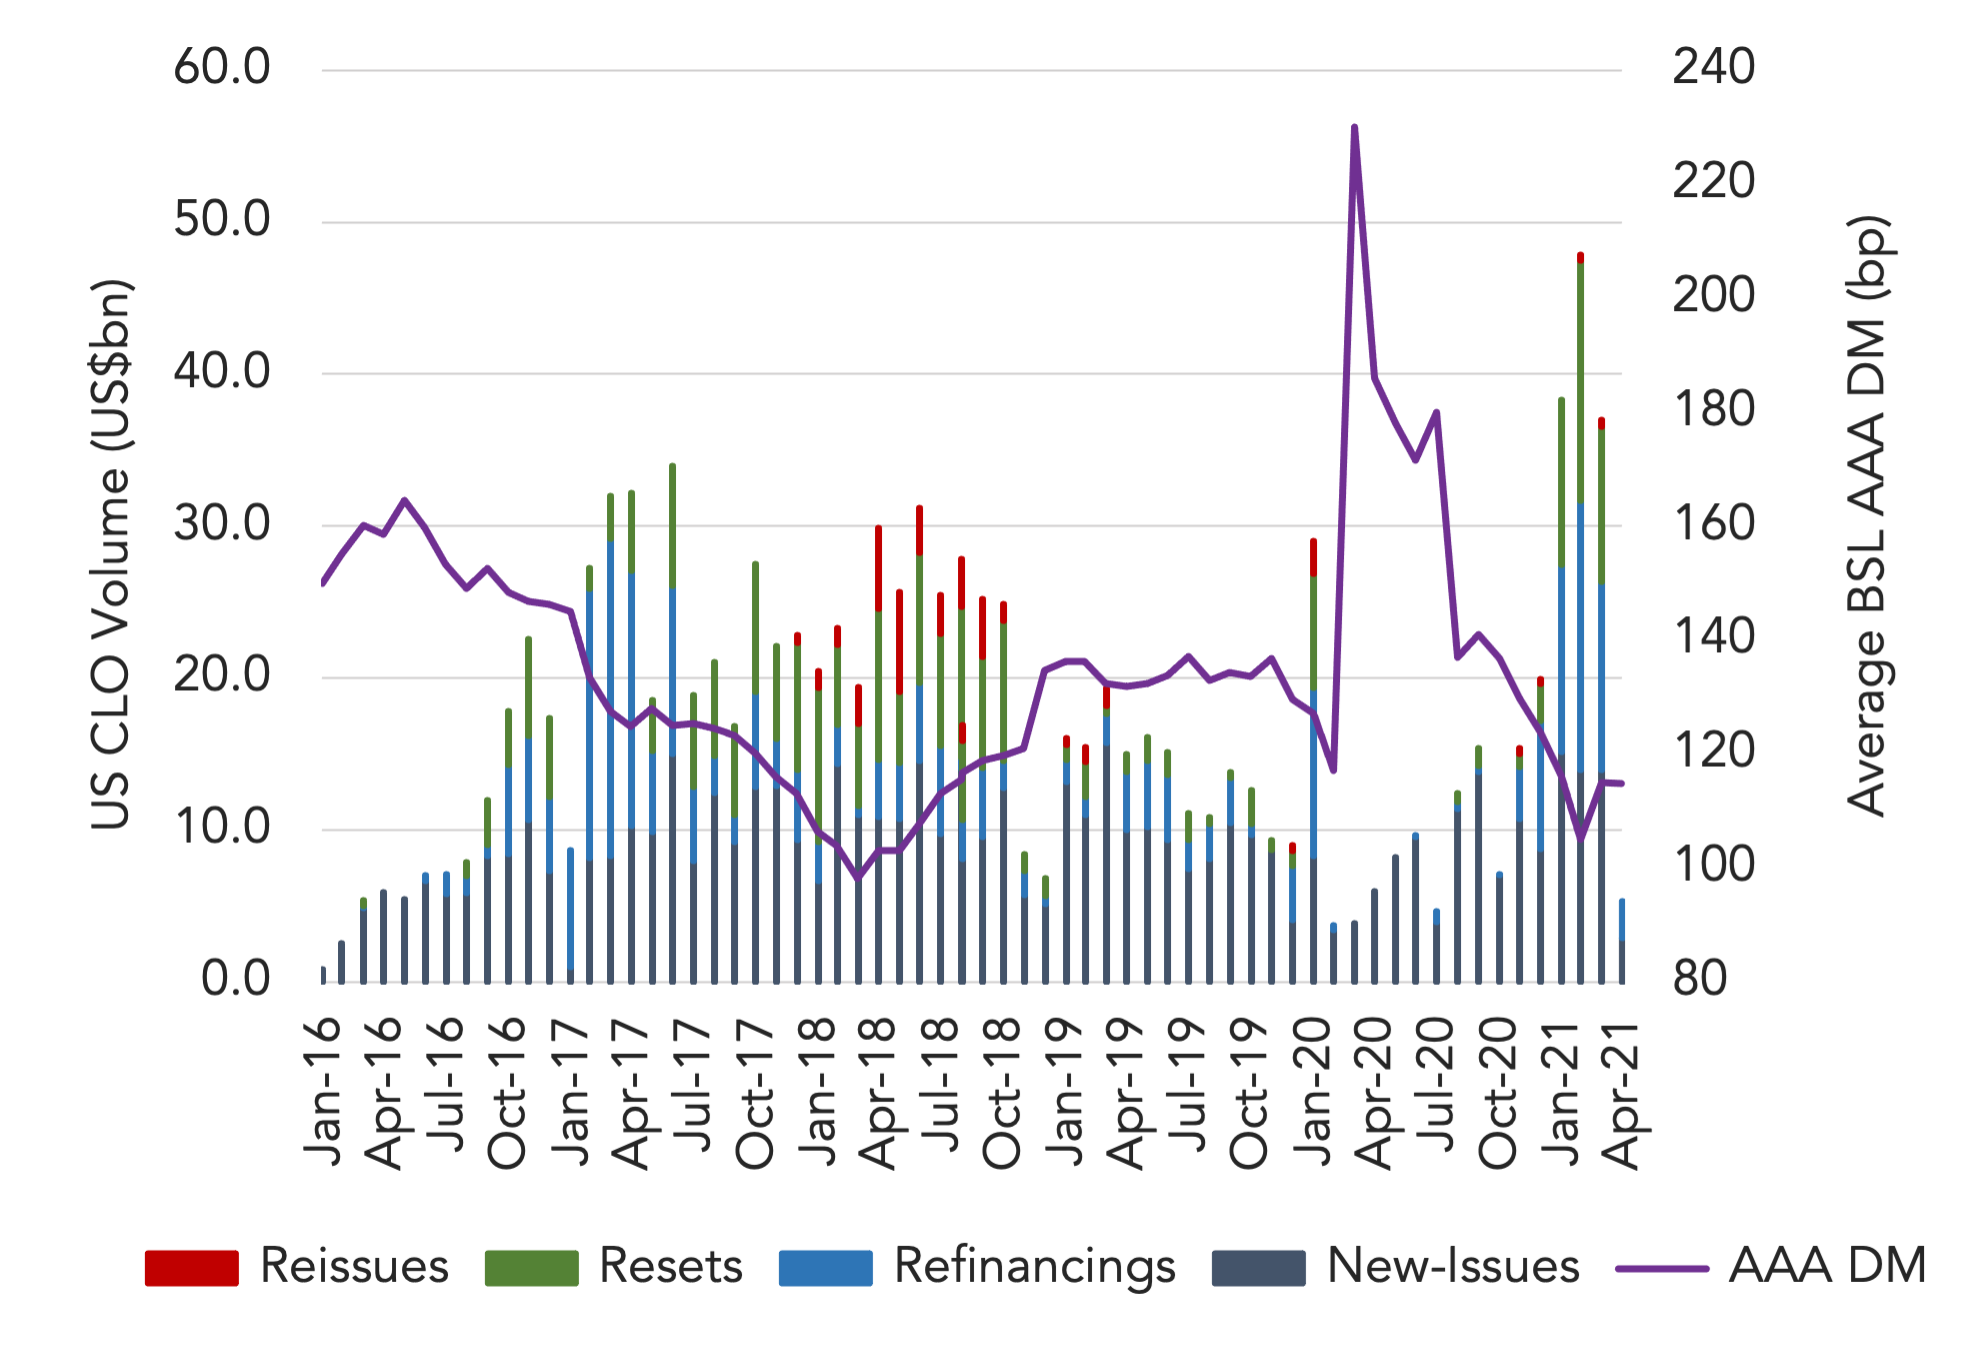
In another indication of robust leveraged loan market activity in 2Q, the CLO calendar continues to grow at a record pace. There has been US$148.4bn of US CLO volume recorded so far in 2021, split between US$54.6bn of new issues, US$53.3bn of refinancings and US$40.5bn of resets or reissues. The average Triple-A DM for April’s new issue activity was 114.8bp, while the tightest Triple-A repricing was 90, executed via PGIM’s Dryden 72 CLO which closed on April 29. After tightening during the first three months of the year, from 124bp to 105bp, spreads widened 10bps in April to 115bp as the pace of CLO volume slowed. Overall, repricing activity continues to overshadow new issue activity, with 223 deals repricing so far this year, of which 59 closed in April and 8 closed in May to date. Repricing volume is also 42% higher than that of new issuance. Amid the ongoing US economic recovery and some inflationary pressures, the CLO market is expected to benefit from investors flush with cash and ongoing demand for yield.
(Past performance is no guarantee of future results.)



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…