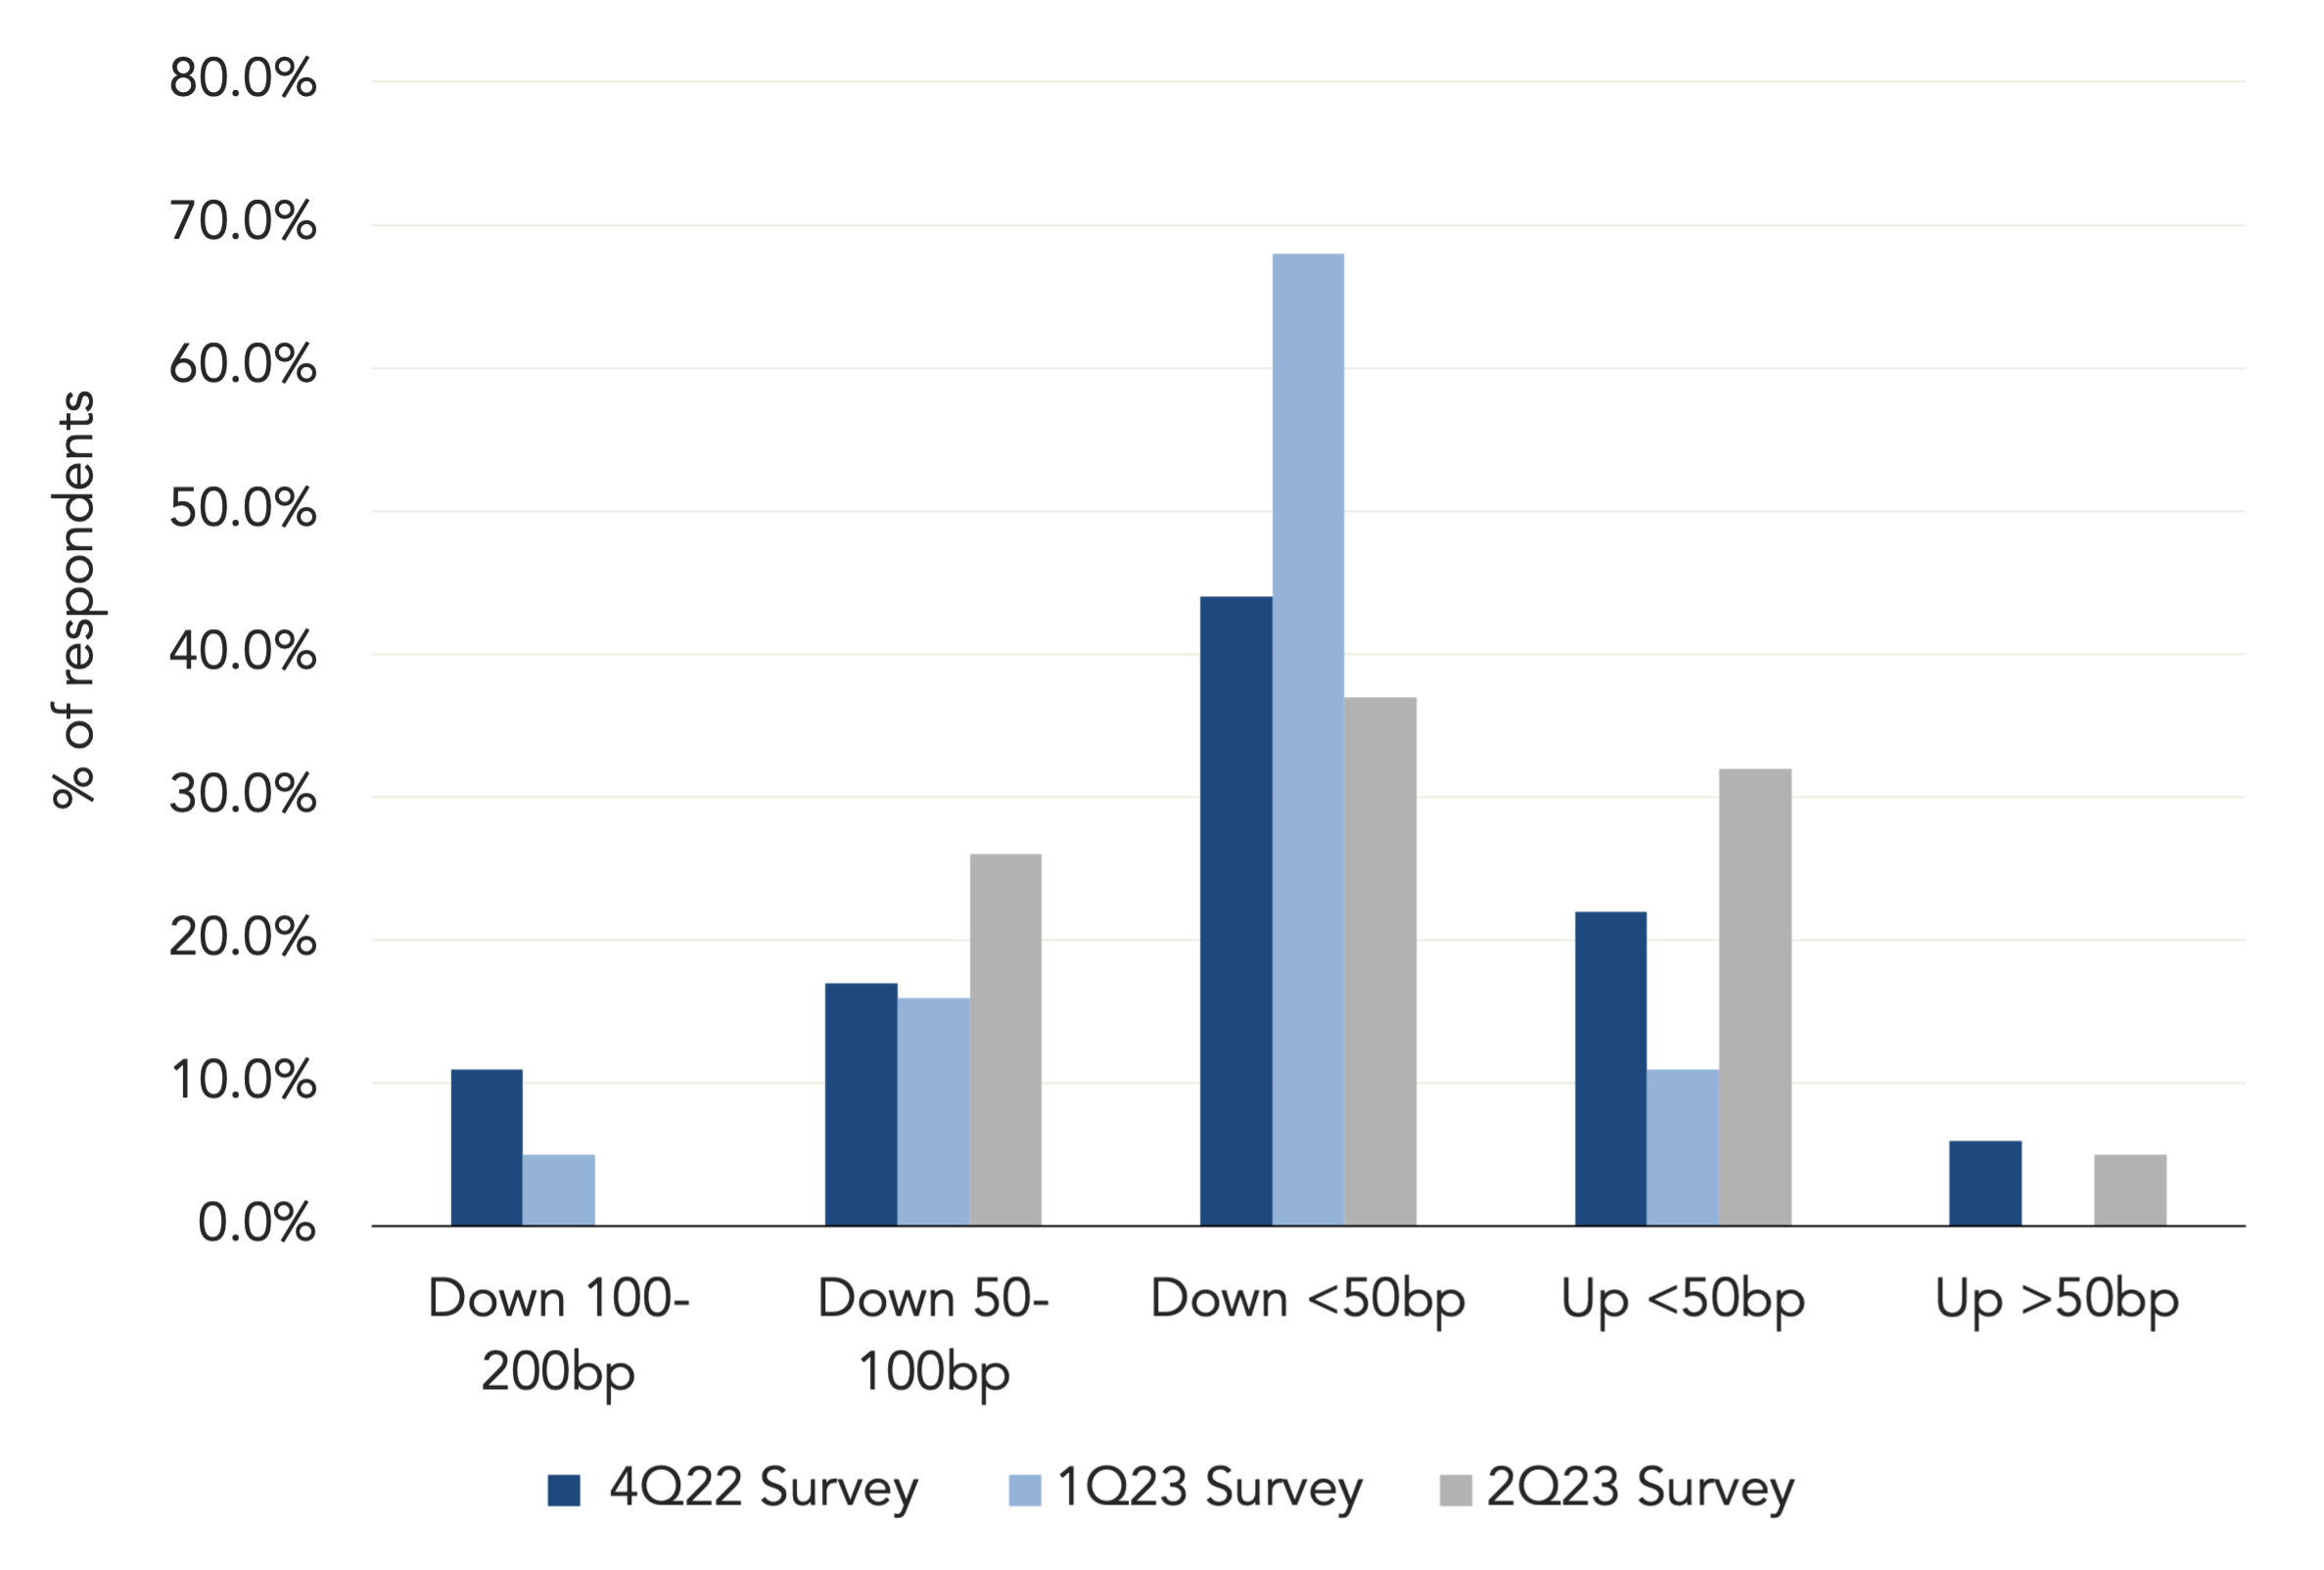
BDC portfolio companies are being closely monitored to gauge stress as a result of the higher interest rate environment, the degree of pressure on margins and declining interest coverage ratios for over-levered borrowers. The most recent, indicative data available does not show any significant deterioration yet although there are indications of softness in some select industries. In terms of credit quality, non-accrual rates remain low by historical standards, holding steady at 1.57% in 1Q23. Despite the current low levels, non-accruals are expected to pick up as operating expenses continue to climb. In terms of valuations, BDC portfolio marks are not expected to move much this quarter. Refinitiv LPC BDC Survey respondents forecast a roughly 50bp change in average portfolio marks for 2Q23, with a bias to the downside from the current 96 level.
(Past performance is no guarantee of future results.)


Latest news
US leveraged loan issuance stalls in October amid secondary market rout
US leveraged loan issuance took a significant hit in October amid deteriorating secondary market conditions. Approximately $41.3b of loans have…