


Institutional loans calendar slows in August amid traditional summer holidays but ahead of year ago-levels
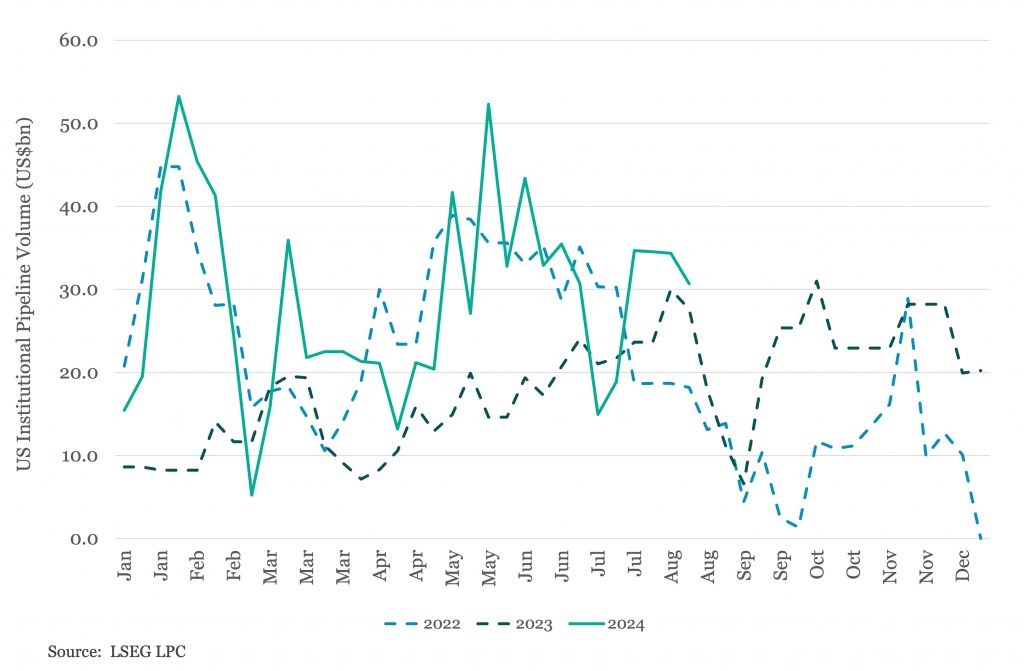
At just under US$31bn, the US institutional loans calendar edged down modestly in early August (from US$34.4bn) as lender and issuer activity slowed ahead of the peak summer holidays. Nevertheless, the anticipated pipeline is up compared to the same time last year and well ahead of 2022’s pace. Following a weaker than expected jobs report on August 2 and subsequent equities sell off, concerns around increased market volatility did prompt a few issuers, including ReWorld Holdings, SeaWorld, SBA Communications, Focus Financial, and ION Analytics, to delay or pull anticipated financings. Lenders noted that although market sentiment remained cautiously positive, the focus on interest rates and geopolitical risk remained in place.


Latest news
Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.
Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…