


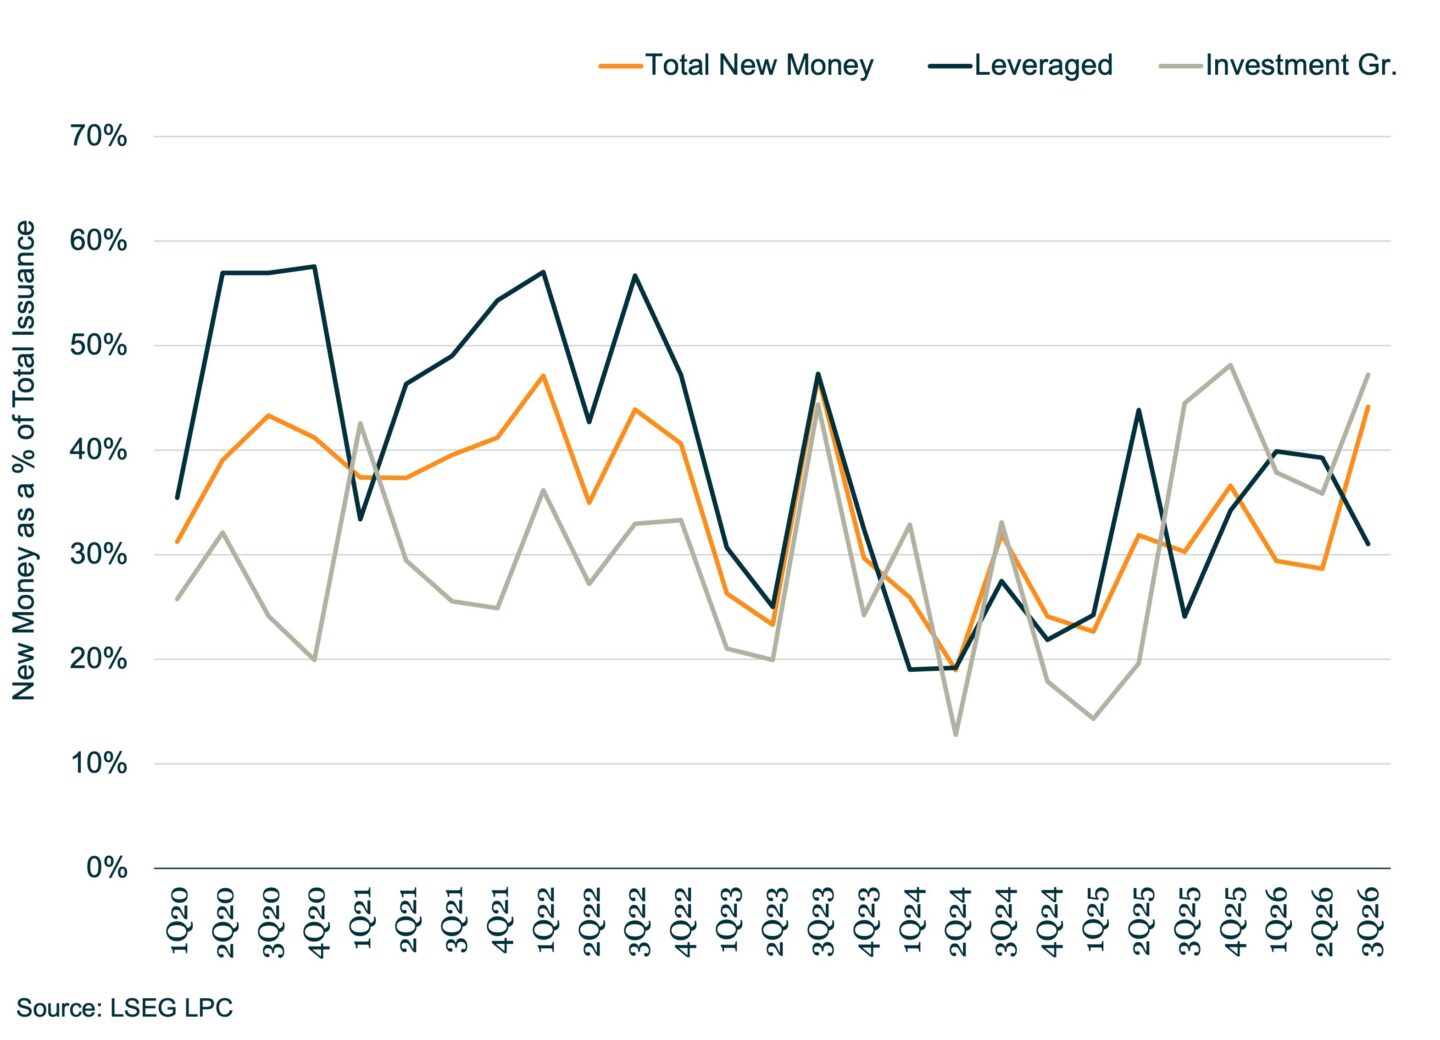
New loan assets as a proportion of total US loan volume make up 44% of the 3Q26 pipeline to date, up from 29% last quarter and the highest level since 3Q23. Most of the boost has come via investment grade issuers who have tapped lenders for M&A financing as well as opportunistic upsizings of existing corporate back stops. Roughly 47% of total investment grade loan volume raised so far this quarter represents new loan assets, up from 36% and the highest pro rata share since 4Q25. In the leveraged space, the trend is a bit more mixed. Although lender demand for new loan assets remains strong, buyout and other acquisition activity has been limited given episodic market volatility. Against this backdrop, 3Q26 new leveraged loan assets only represent 31% of the quarterly pipeline to date, down from 39% in 2Q26.




Private Credit Defaults 101: Back to School
As Labor Day approaches, the unofficial end of summer is upon us. But, before we get too sad, there is also the familiar back-to-school energy.