


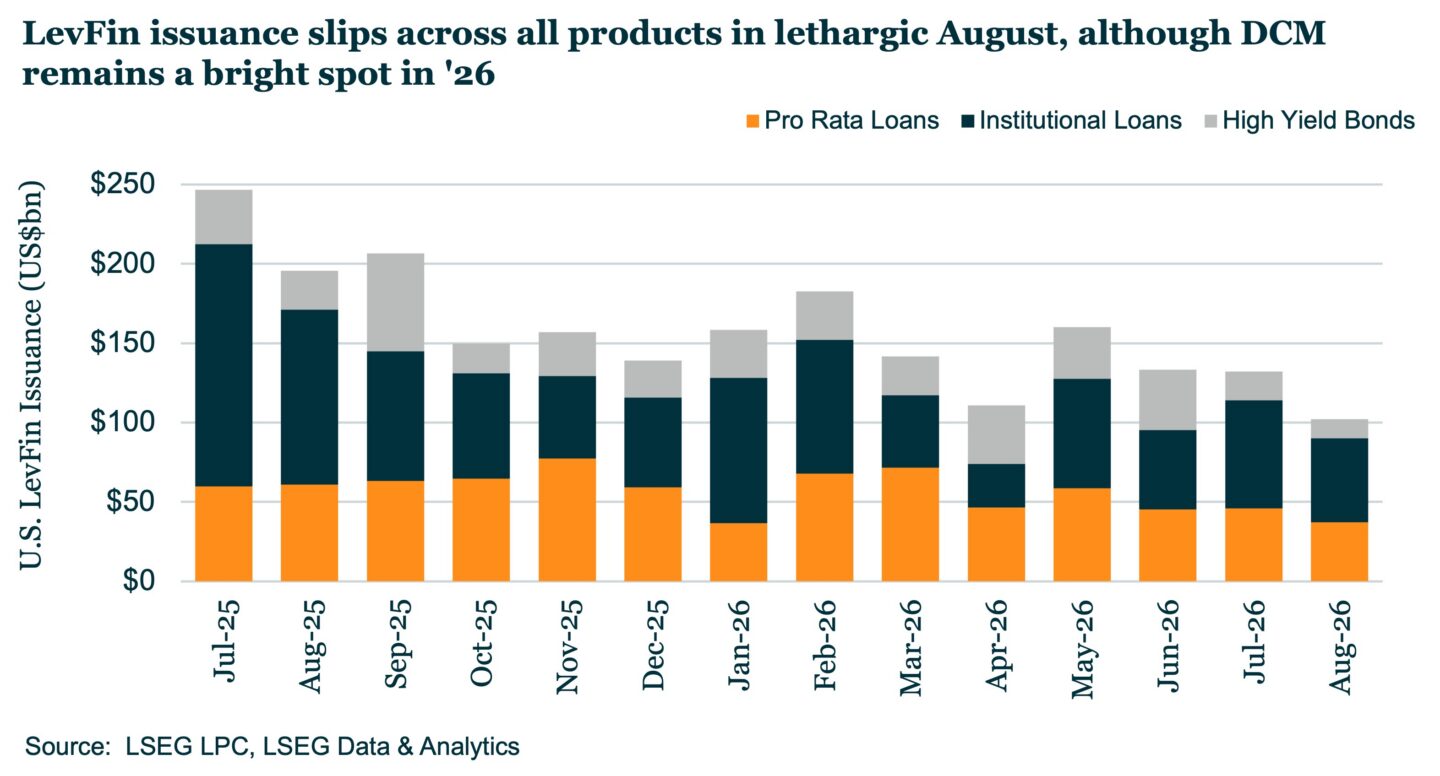
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including high-yield bonds) slipped for a third consecutive month to just more than $100bn, which was almost 25% slower than July and about 50% lighter than last August; aside from April ’25, one would have to go back to ’23 to find a slower month for the business. Originations slowed across all products on the month, led by high-yield bonds (US$12.3bn, down 32%), followed by institutional loans (US$53bn, down 22%) and bank loans (US$37bn, down 19%). Even institutional loan refinancings (US$48bn, down 11%) fell alongside leveraged M&A loan issuance (US$9bn, down 38%). And institutional loan repricings sank (US$14bn, down 42%) even as secondary loan bids and par-plus share steadily edged higher. The one bright spot was strategic M&A lending, although the advance was marginal (less than US$1bn) and outstripped by a much larger decline in LBO underwritings. US LevFin issuance exceeds US$1.1trn so far this year, down about 18% year-over-year. Institutional loans have been the biggest contributor to that decline, with parallel hiccups in refinancings and M&A putting a US$200bn drag on issuance, while high-yield bonds remain the only product trending above year-ago issuance levels.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
