


On the back of increasingly unsettling global headlines, the capital markets took a beating earlier this month. As the equity markets tumbled, the US high yield bond market likewise saw skittishness culminating in an outflow of over $7 billion during the week of August 6 alone, before observing a rebound via over $2 billion in inflows. 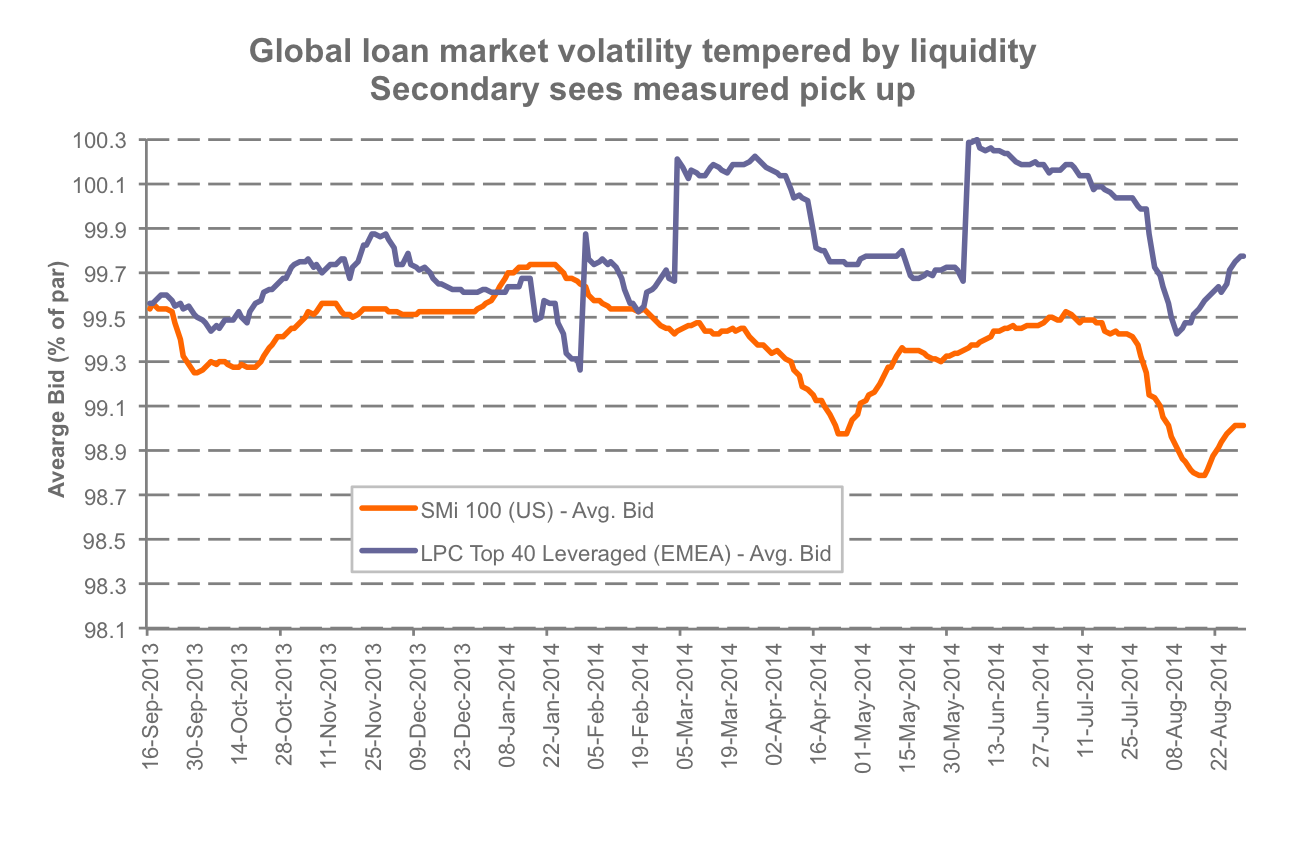 Unsurprisingly, the loan market experienced similar unease in tandem with that of the broader capital markets. Loan retail funds saw nearly $1.5 billion in outflows the week of August 6, the largest weekly exodus of liquidity since 2011, before showing some restraint in the weeks that followed. Globally, pricing corrections and demand for tighter credits resurfaced and issuers took pause to either tweak financings already in market or to postpone planned credits in the hope that better market conditions would re-emerge in September. In both the US and European loan markets, the secondary likewise took a hit as bids tumbled from 99.15 and 99.88 at the beginning of the month to lows of 98.79 and 99.48 within the SMI 100 (which tracks the 100 most widely held loans) and the Lev 40 respectively. Despite the broader market turbulence however, natural loan market investors remained in place with CLO issuance approaching $77 billion so far this year. In turn, secondary bids have slowly crept up with the SMI 100 and Lev 40 finishing August at 99 and 99.78 respectively. Underliers




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
