


Markit Recap – 11/21/2016

The European Commission announced on November 23 a banking reform package that will result in changes to the CRR and CRD IV capital requirement legislation, as well as changes to the BRRD and SRMR legislation relating to recovery and resolution of failing financial institutions. The package is very broad, so we won’t attempt to comment on all of the measures.
But one change under the BRRD caught our eye, as it will have a material impact on how the bond market – and possibly the CDS market – trades. The EC proposes a harmonised framework for bondholder hierarchy. This aims to address the fragmentation among EU countries in how their G-SIBs comply with the FSB Total Loss Absorbing Capital (TLAC) and the EU MREL rules, which aim to contain systemic risk from large global banks. The EU is proposing a new tier of debt (sometimes called junior-senior), effectively sitting between traditional senior unsecured bonds and subordinated debt. France introduced such a tier late last year, and it appears that the EC has chosen to adopt this approach across the EU. Nykredit also printed a “senior resolution note” – tier 3 issuance subordinated to other senior debt – in June.
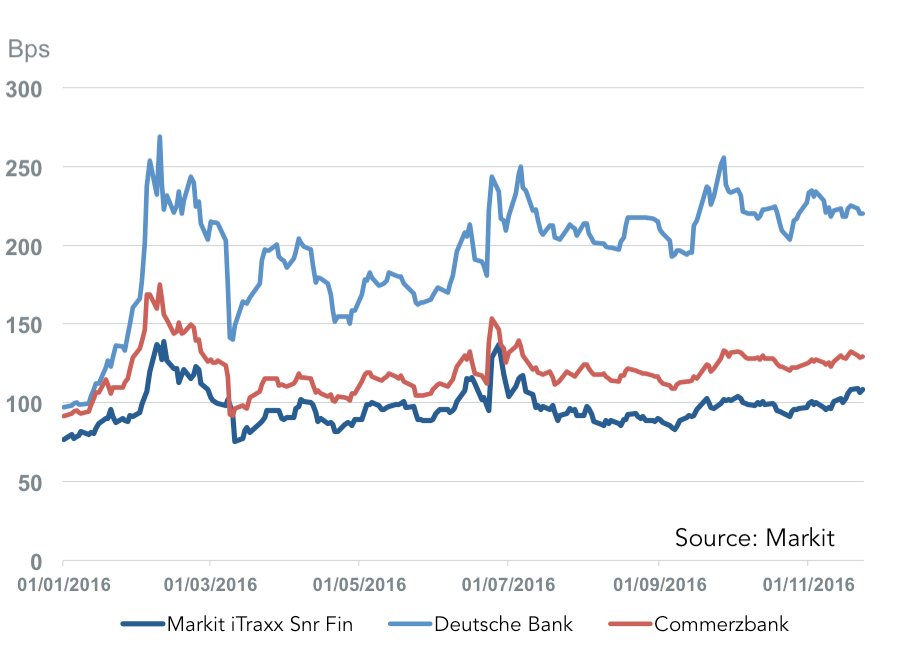
Germany introduced legislation earlier this year that subordinated senior unsecured bondholders to other creditors, such as depositors, certain types of derivatives and holders of money market instruments. This statutory subordination of senior bondholders was posited as an explanation for Deutsche Bank’s CDS widening sharply in 2016, including by the bank itself. It may well be a factor, though Deutsche has underperformed German peers such as Commerzbank. Perhaps this is down to Deutsche’s higher derivative liabilities placing greater subordination pressure on its senior debt, or maybe the CDS market is reflecting broader concerns about CoCo triggers and long-term profitability.
The EC proposal – a new tier of debt – isn’t the only way to address TLAC requirements under a regime of enforced bail-ins. UK and Swiss banks have holding company structures that allow them to issue senior debt that will be structurally subordinated to senior bonds at the operating company level. In some ways this is a neater solution, as the effective seniority of tier 3 debt can be determined by legal entity.
Both approaches will clearly impact the bond markets, with investors having to effectively price a new tier of debt in the EU and evaluate the structural subordination of increasing volumes of debt issued at holding company level. It may also have a knock-on effect on the CDS market. There are already markets being made in UK bank holding company CDS, and we may see markets emerging referencing the new junior-senior tier (if other regulations such as FRTB don’t dampen liquidity provision). CDS users and vendors will need to ensure that the correct pricing, processing and reference data mechanism are in place.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

With inflation running hot, rate hike expectations strengthen
A hotter-than-expected inflation reading has renewed expectations for near-term Federal Reserve tightening. The Consumer Price Index rose 0.6% month-over-month, pushing…

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.
