


Markit Recap – 1/18/2016

The economies of Italy and China don’t appear to have much in common. Italy’s government would welcome a GDP growth rate of 1%, while China expands less than 7% and investors take flight. One is a sclerotic, decaying Western country, the other is a dynamic Asian tiger. Such is the conventional wisdom.
But look beyond the clichés and it is clear that there is at least one striking similarity. Both countries’ banking systems are groaning under the weight of bad loans. In the case of Italy, we can say this with some certainty – EBA figures show that non-performing loans made up nearly 17% of assets in Q3, the highest in the eurozone behind Slovenia and Ireland. The ECB’s Single Supervisory Mechanism recently requested more information on bad loans from Italian banks, a measure they insisted was standard practice but the market was unconvinced. CDS spreads widened sharply – Unicredit 5-year senior was trading at 200bps on Tuesday, 70bps wider than where it started the year; Intesa Sanpaolo was 46bps wider at 138bps.
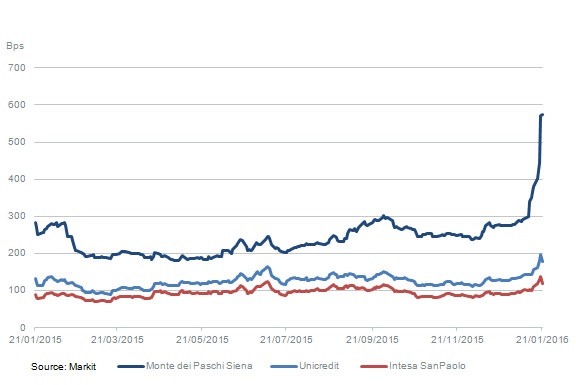
Those are significant moves by normal standards. But they are inconsequential in comparison to the performance of Monte dei Paschi Siena, the world’s oldest bank. MPS spreads widened from 276bps to 575bps over the last three weeks and its curve flattened, indicating near-term distress. MPS is viewed as the weakest of the major Italian banks, and with good reason. Its non-performing loan ratio is a staggering 31% and its market capitalisation of €334 million is dwarfed by the €3bn capital injection it received less than a year ago.
The reaction in the credit and equity markets suggests that the bank is incapable of remaining upright without support. A takeover by a stronger institution or sale of the problematic assets would be the obvious solutions, but without a state backstop on the NPLs – which the EU hasn’t approved – these solutions may not be realistic.
With the introduction of the BRRD earlier this year, senior and subordinated bond investors are understandably cautious about holding bank in weak banks. But at least they have some level of transparency in asset quality, unlike in China. The rampant credit creation and overinvestment since the government’s stimulus programme in 2009 has likely led to a sharp increase in bad loans, but of course these may not have been recognised on the balance sheets of the country’s banks. China’s government may respond to the recent slowdown in growth with further stimulus, which will only inflame the underlying problems and delay the day of reckoning. Or they may devalue their currency, a beggar thy neighbour policy that would hurt other exporting countries, including Italy. The pain is far from over for Italian banks.
Contact: Gavan Nolan
Email: Gavan.Nolan@markit.com




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
