


Markit Recap – 9/18/2017

Toys R Us triggers CDS credit event
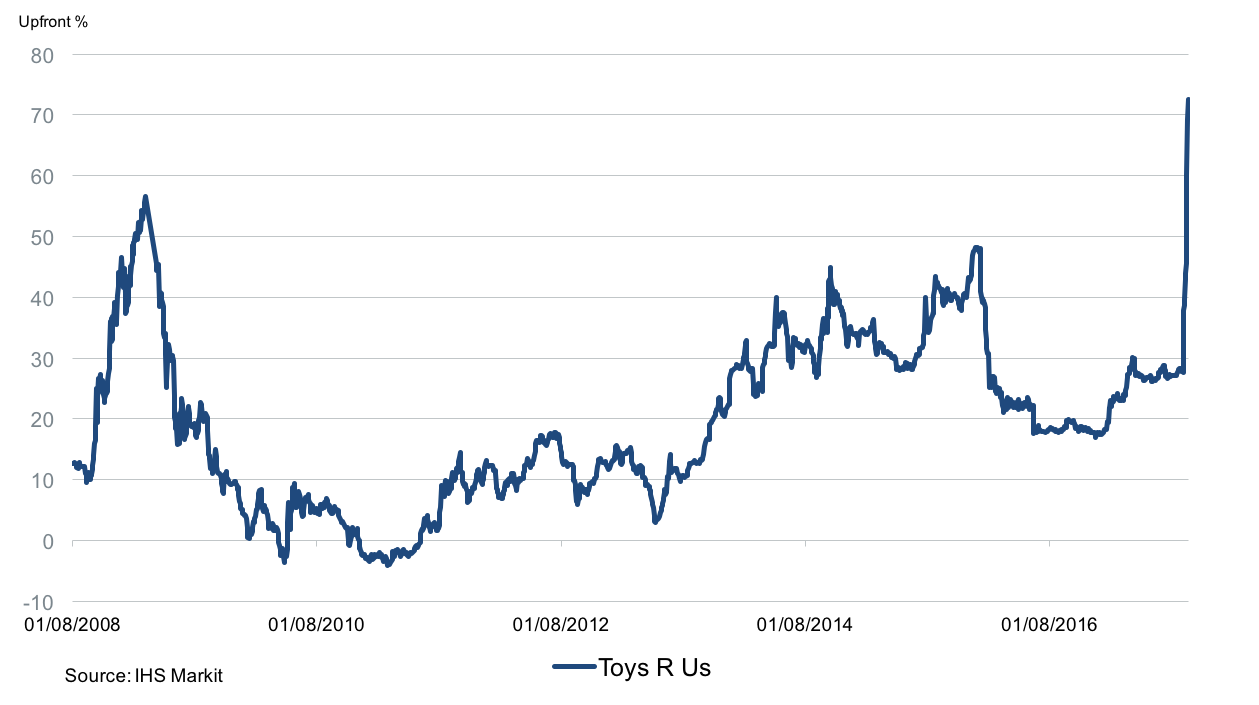
Toys R Us became the latest CDS name to default after it filed for Chapter 11 bankruptcy protection. There have been lots of contentious credit events this year (Noble, Banco Popular, Monte to name a few) but this one was cut and dried. An auction will be held in due course, which will be the eighth auction in 2017. This is the highest number since 2013, a reminder that default cycles and business cycles don’t always move in tandem.
The US toy group is well established in the high-yield CDS market and has been a constituent of the on-the-run Markit CDX.NA.HY index since Series 9 (10 years ago). Not long before that, in 2005, the firm was acquired by a private equity consortium during the leveraged buyout boom. Unsurprisingly, since then it has been saddled with a large debt burden, which wasn’t a problem when the company made decent profits.
But a combination of structural change in the industry- the growth of Amazon and online retail – and the effects of the financial crisis made the debt difficult to service. The owners were unable to exit through one of their usual channels – an IPO – which meant that the firm was destined to remain a high yield name. However, it hasn’t been a steady trajectory of credit deterioration for Toys R Us. It has been quoted upfront for several years, but it did recover during 2015 and was trading at 17 points upfront less than a year ago, a level not suggestive of immediate default.
Nonetheless, operating performance was sluggish and the firm had over $5bn in debt. Matters were bound to come to a head and they did this week, perhaps a little sooner than the market expected. There have been a few casualties of the LBO boom in recent years, most notably the largest of the lot – TXU (Energy Future Holdings). As refinancing conditions become more challenging as the rates cycle turns, then it is possible that other firms taken private will share Toys R US’ fate.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.