


Click here to learn more.
Join Fitch for the upcoming Outlook panel: Credit Outlook 2025 Private Credit
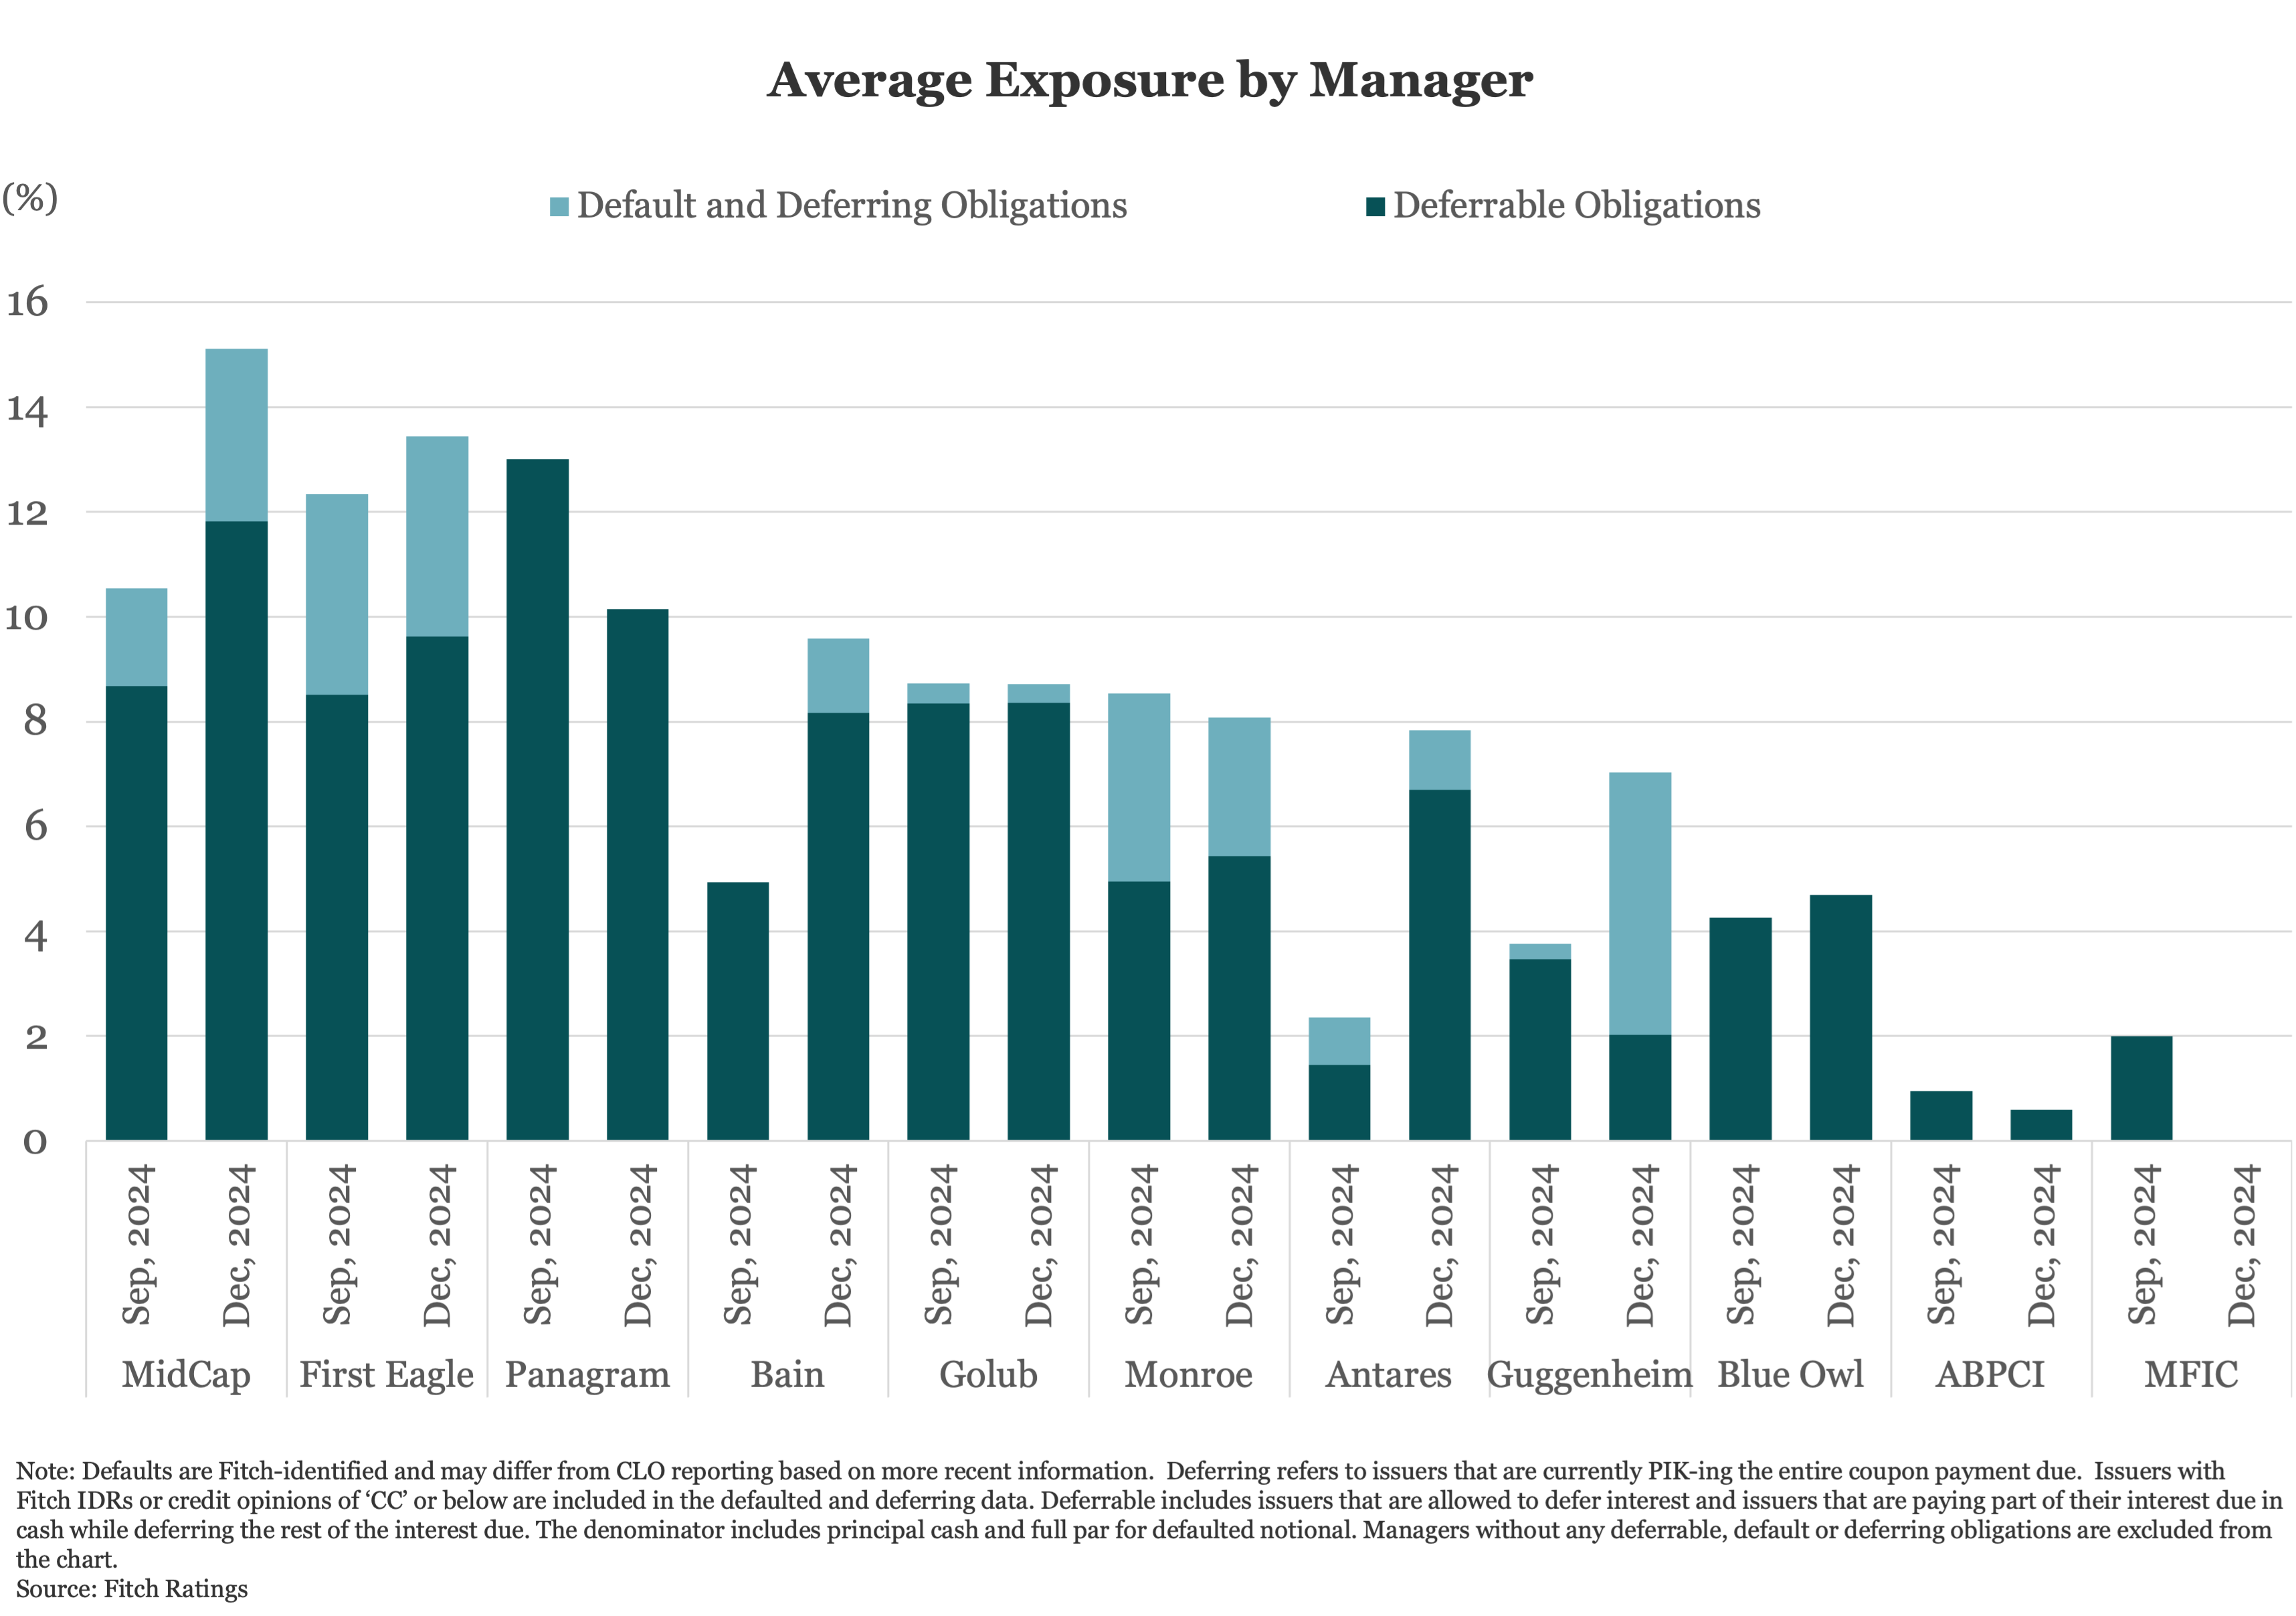
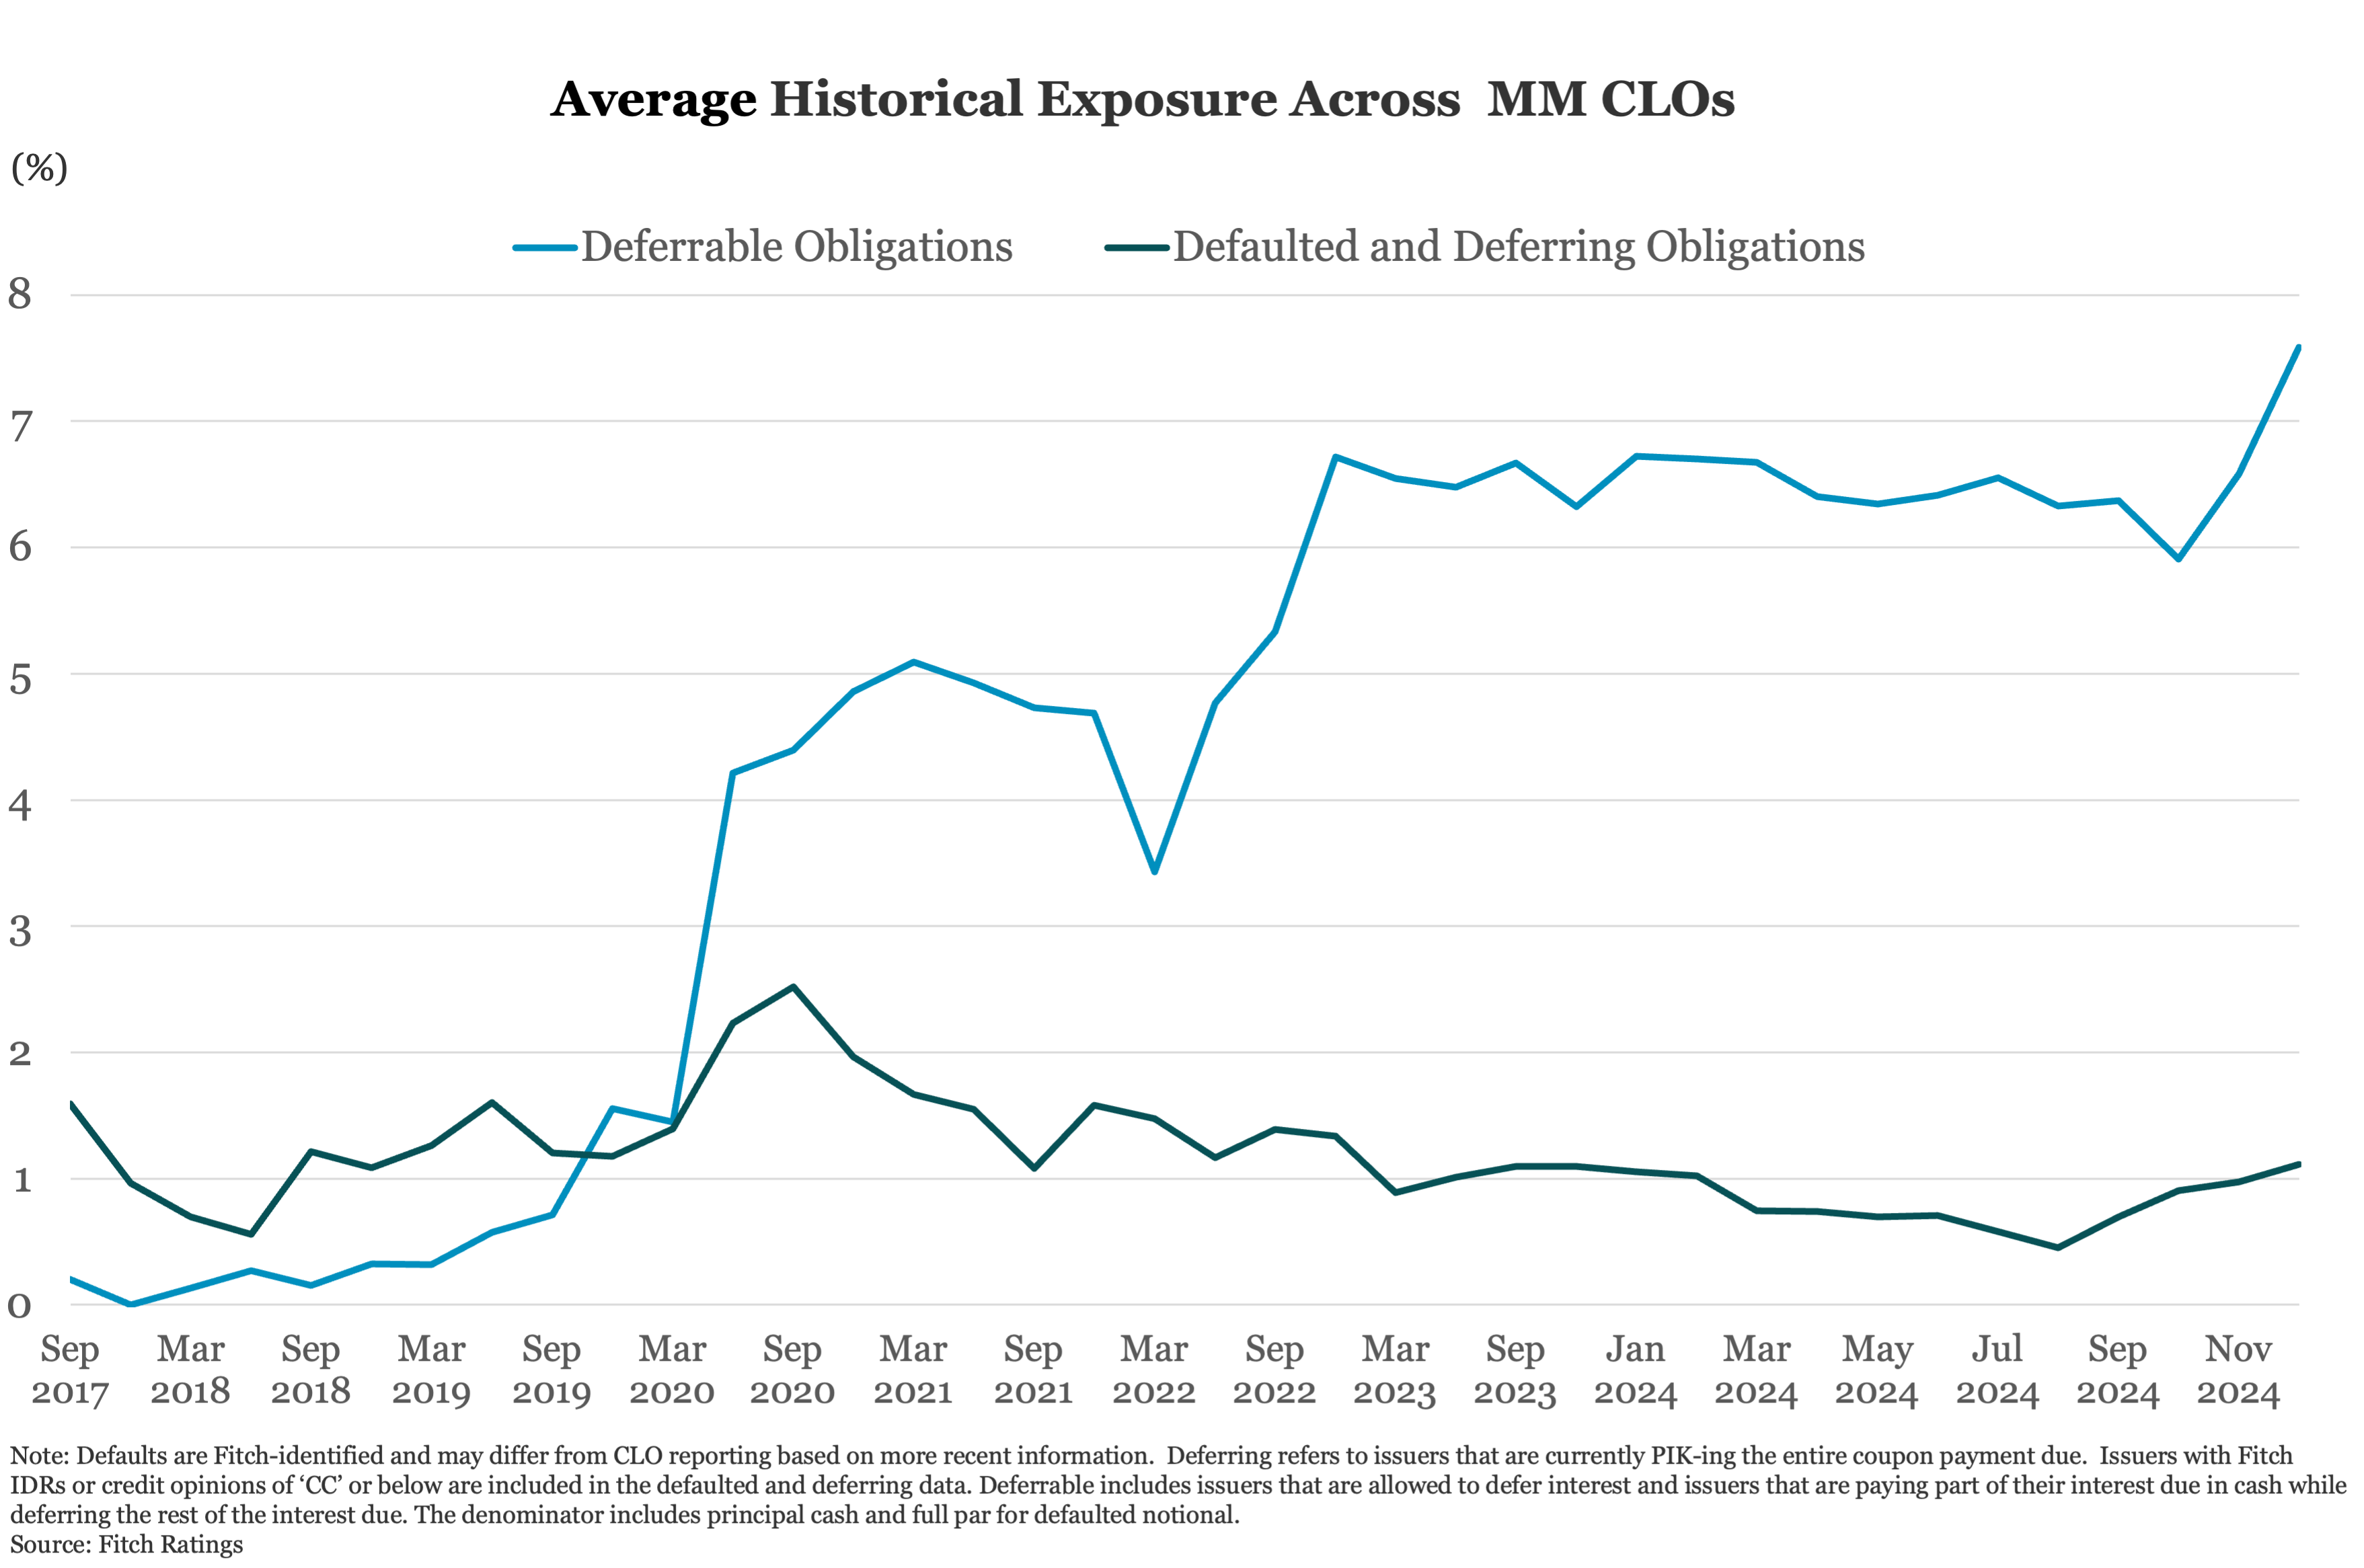
At the end of 2024, 24 CLOs had exposure to at least one defaulted or deferring issuer. The average exposure in middle market (MM) CLOs rose to 1.1%, up from 0.7% in the previous quarter, while remaining unchanged from the same period last year. In December, six new defaulted or deferring issuers were reported across eight MM CLOs, these issuers contributing to a combined exposure rate of 0.7% to 1.4% across these transactions. Additionally, one prior defaulted issuer emerged and another one was removed from the Fitch-rated CLOs in December.


Latest news
Software, technology and consumer sectors lose deal share in 9M’26
The software and technology sector, the second most active sector in 2025 at 17% of total deal activity, slid to fifth place in the first nine months of 2026.


Leveraged loan investors see gains in November
Following a 0.25% decline in October, the Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned 0.60% this month through…