


Click here to download report.
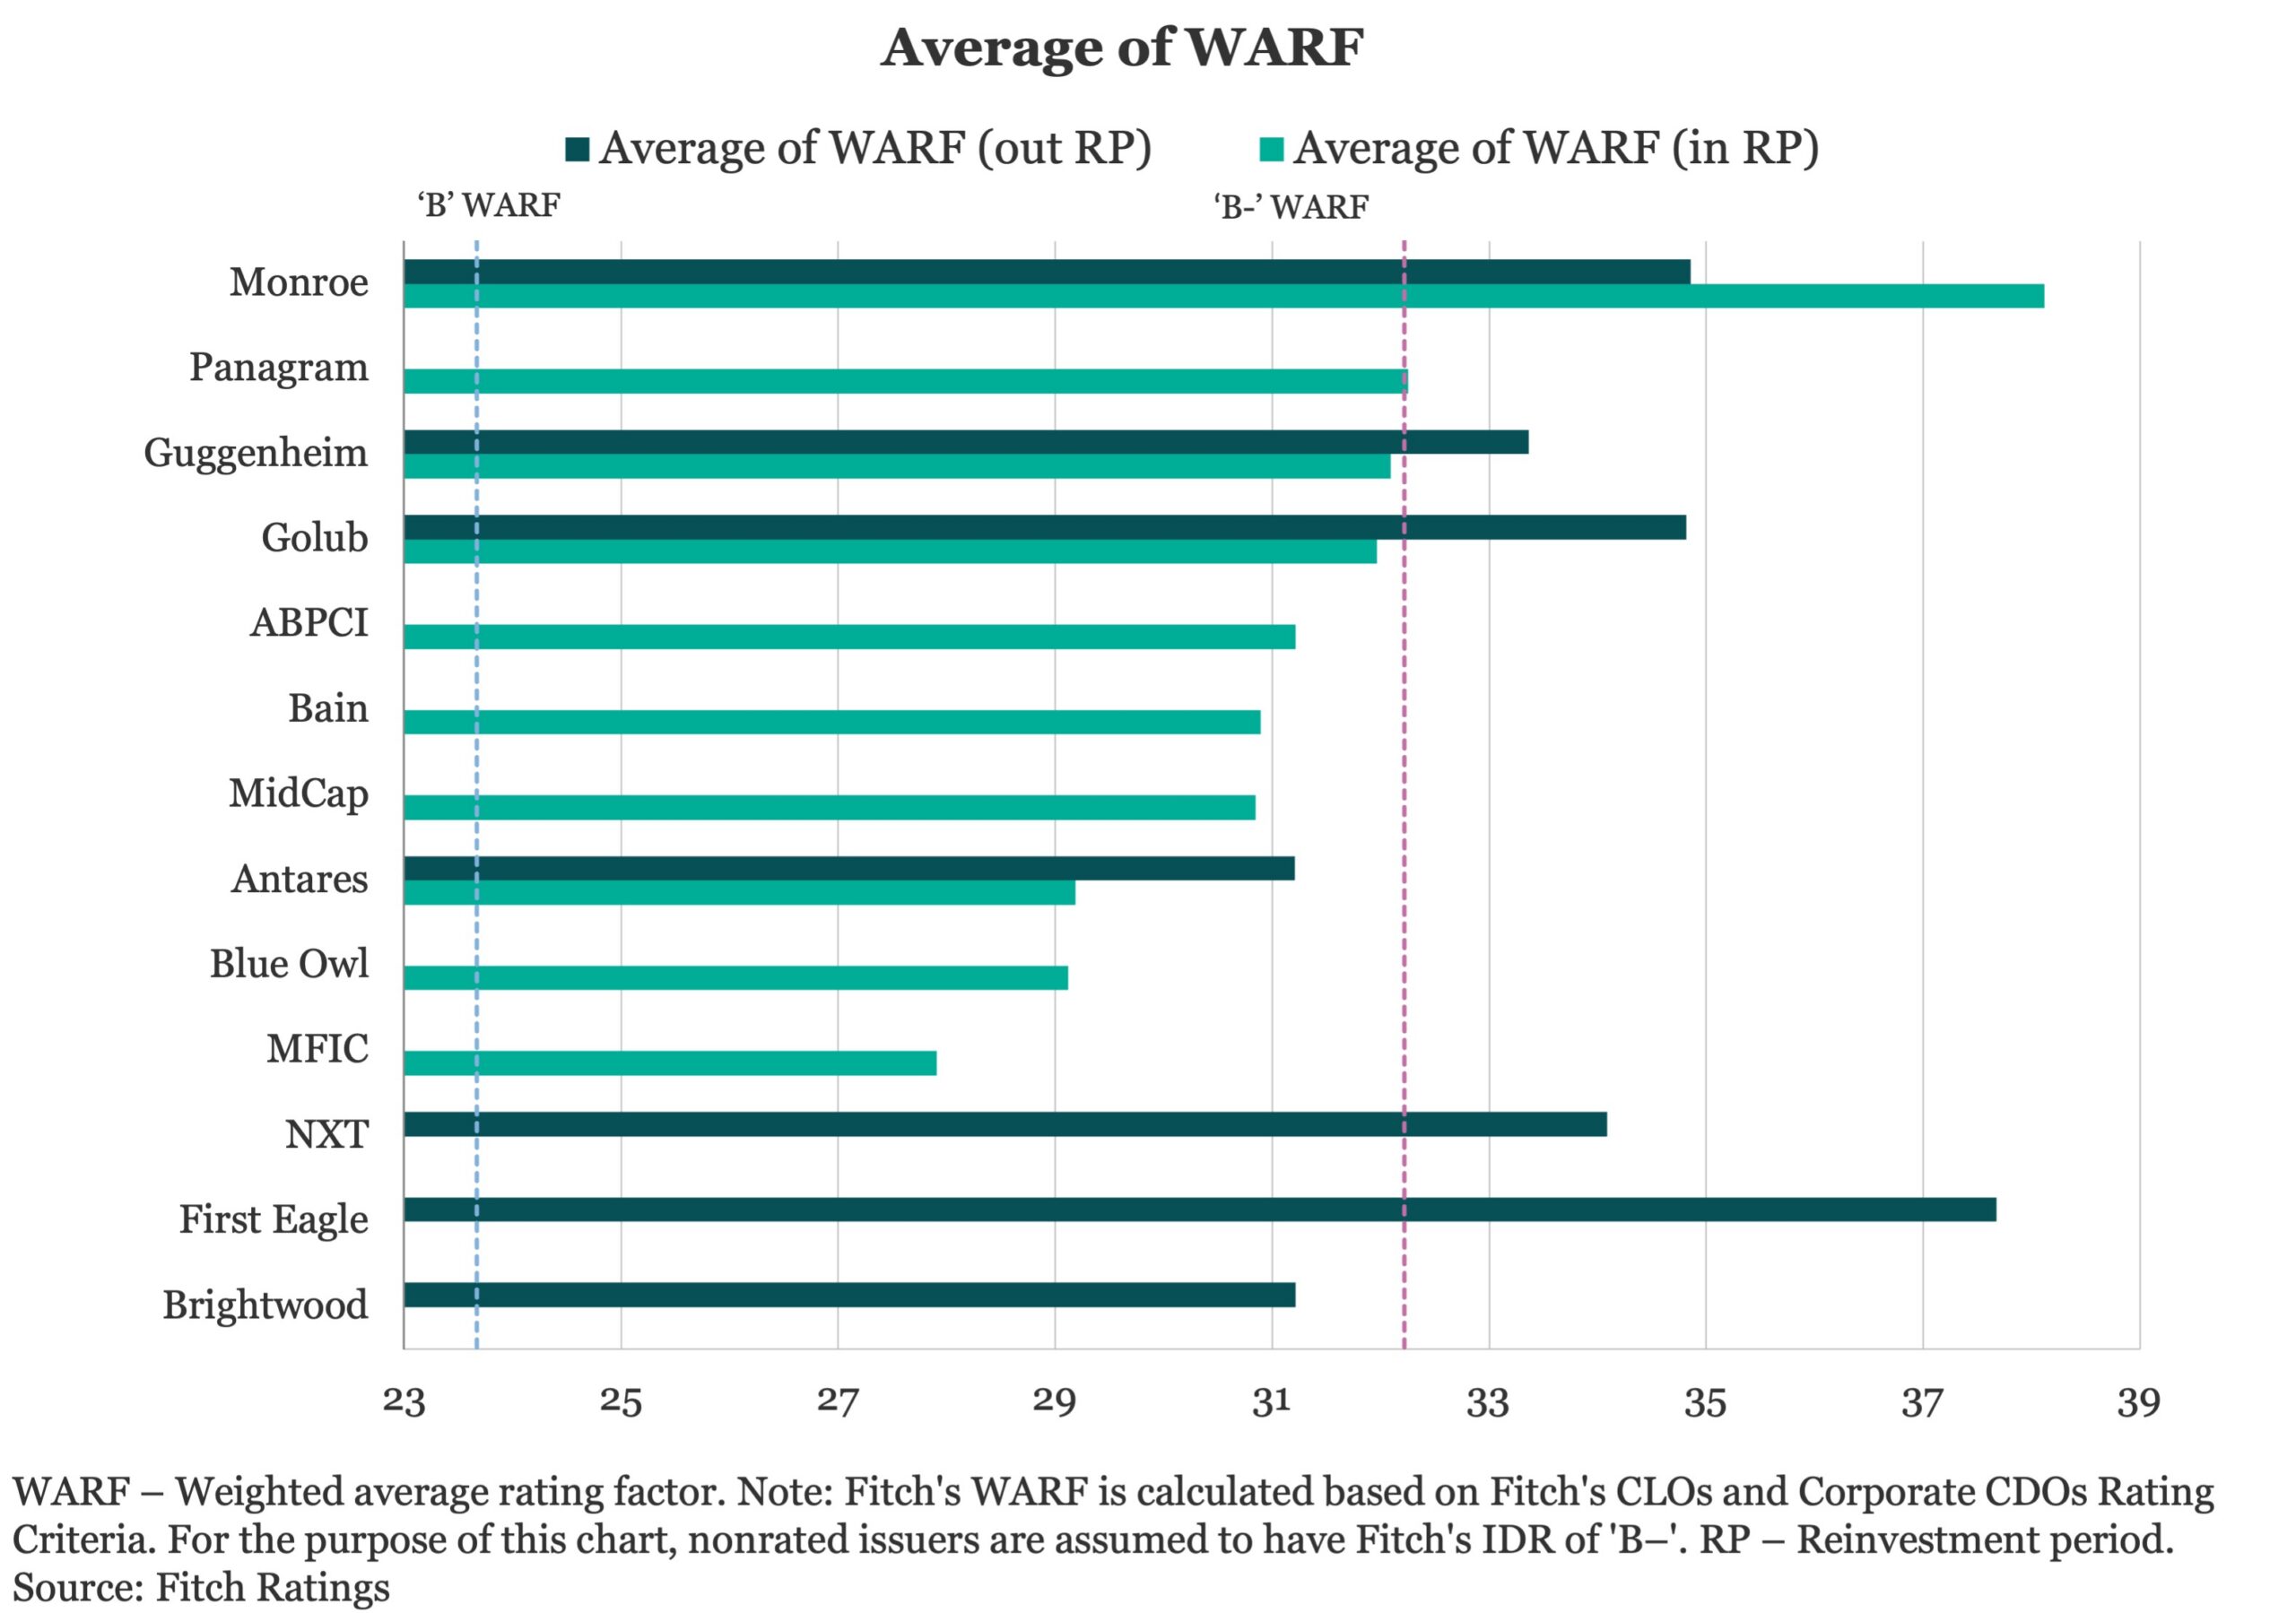
All Fitch-rated MM CLOs include a Fitch Test Matrix as part of a CLO’s Collateral Quality Tests (CQTs) in MM CLOs, including Fitch weighted average recovery rate (WARR), Fitch weighted average rating factor (WARF), weighted average spread (WAS) and weighted average life (WAL), generally remain in compliance against test limits for deals in reinvestment. The median cushion to limits were 1.9% for WARR, 2.0 points WARF, 0.3% WAS and 2.4 years WAL. One MM CLO in reinvestment is not in compliance with both the Fitch WARR and WARF test limits at the end of August 2024.


Latest news
Software, technology and consumer sectors lose deal share in 9M’26
The software and technology sector, the second most active sector in 2025 at 17% of total deal activity, slid to fifth place in the first nine months of 2026.


Leveraged loan investors see gains in November
Following a 0.25% decline in October, the Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned 0.60% this month through…