


Click here to learn more.
Fitch’s Privately Monitored Ratings (PMR) Portfolio – 4Q25
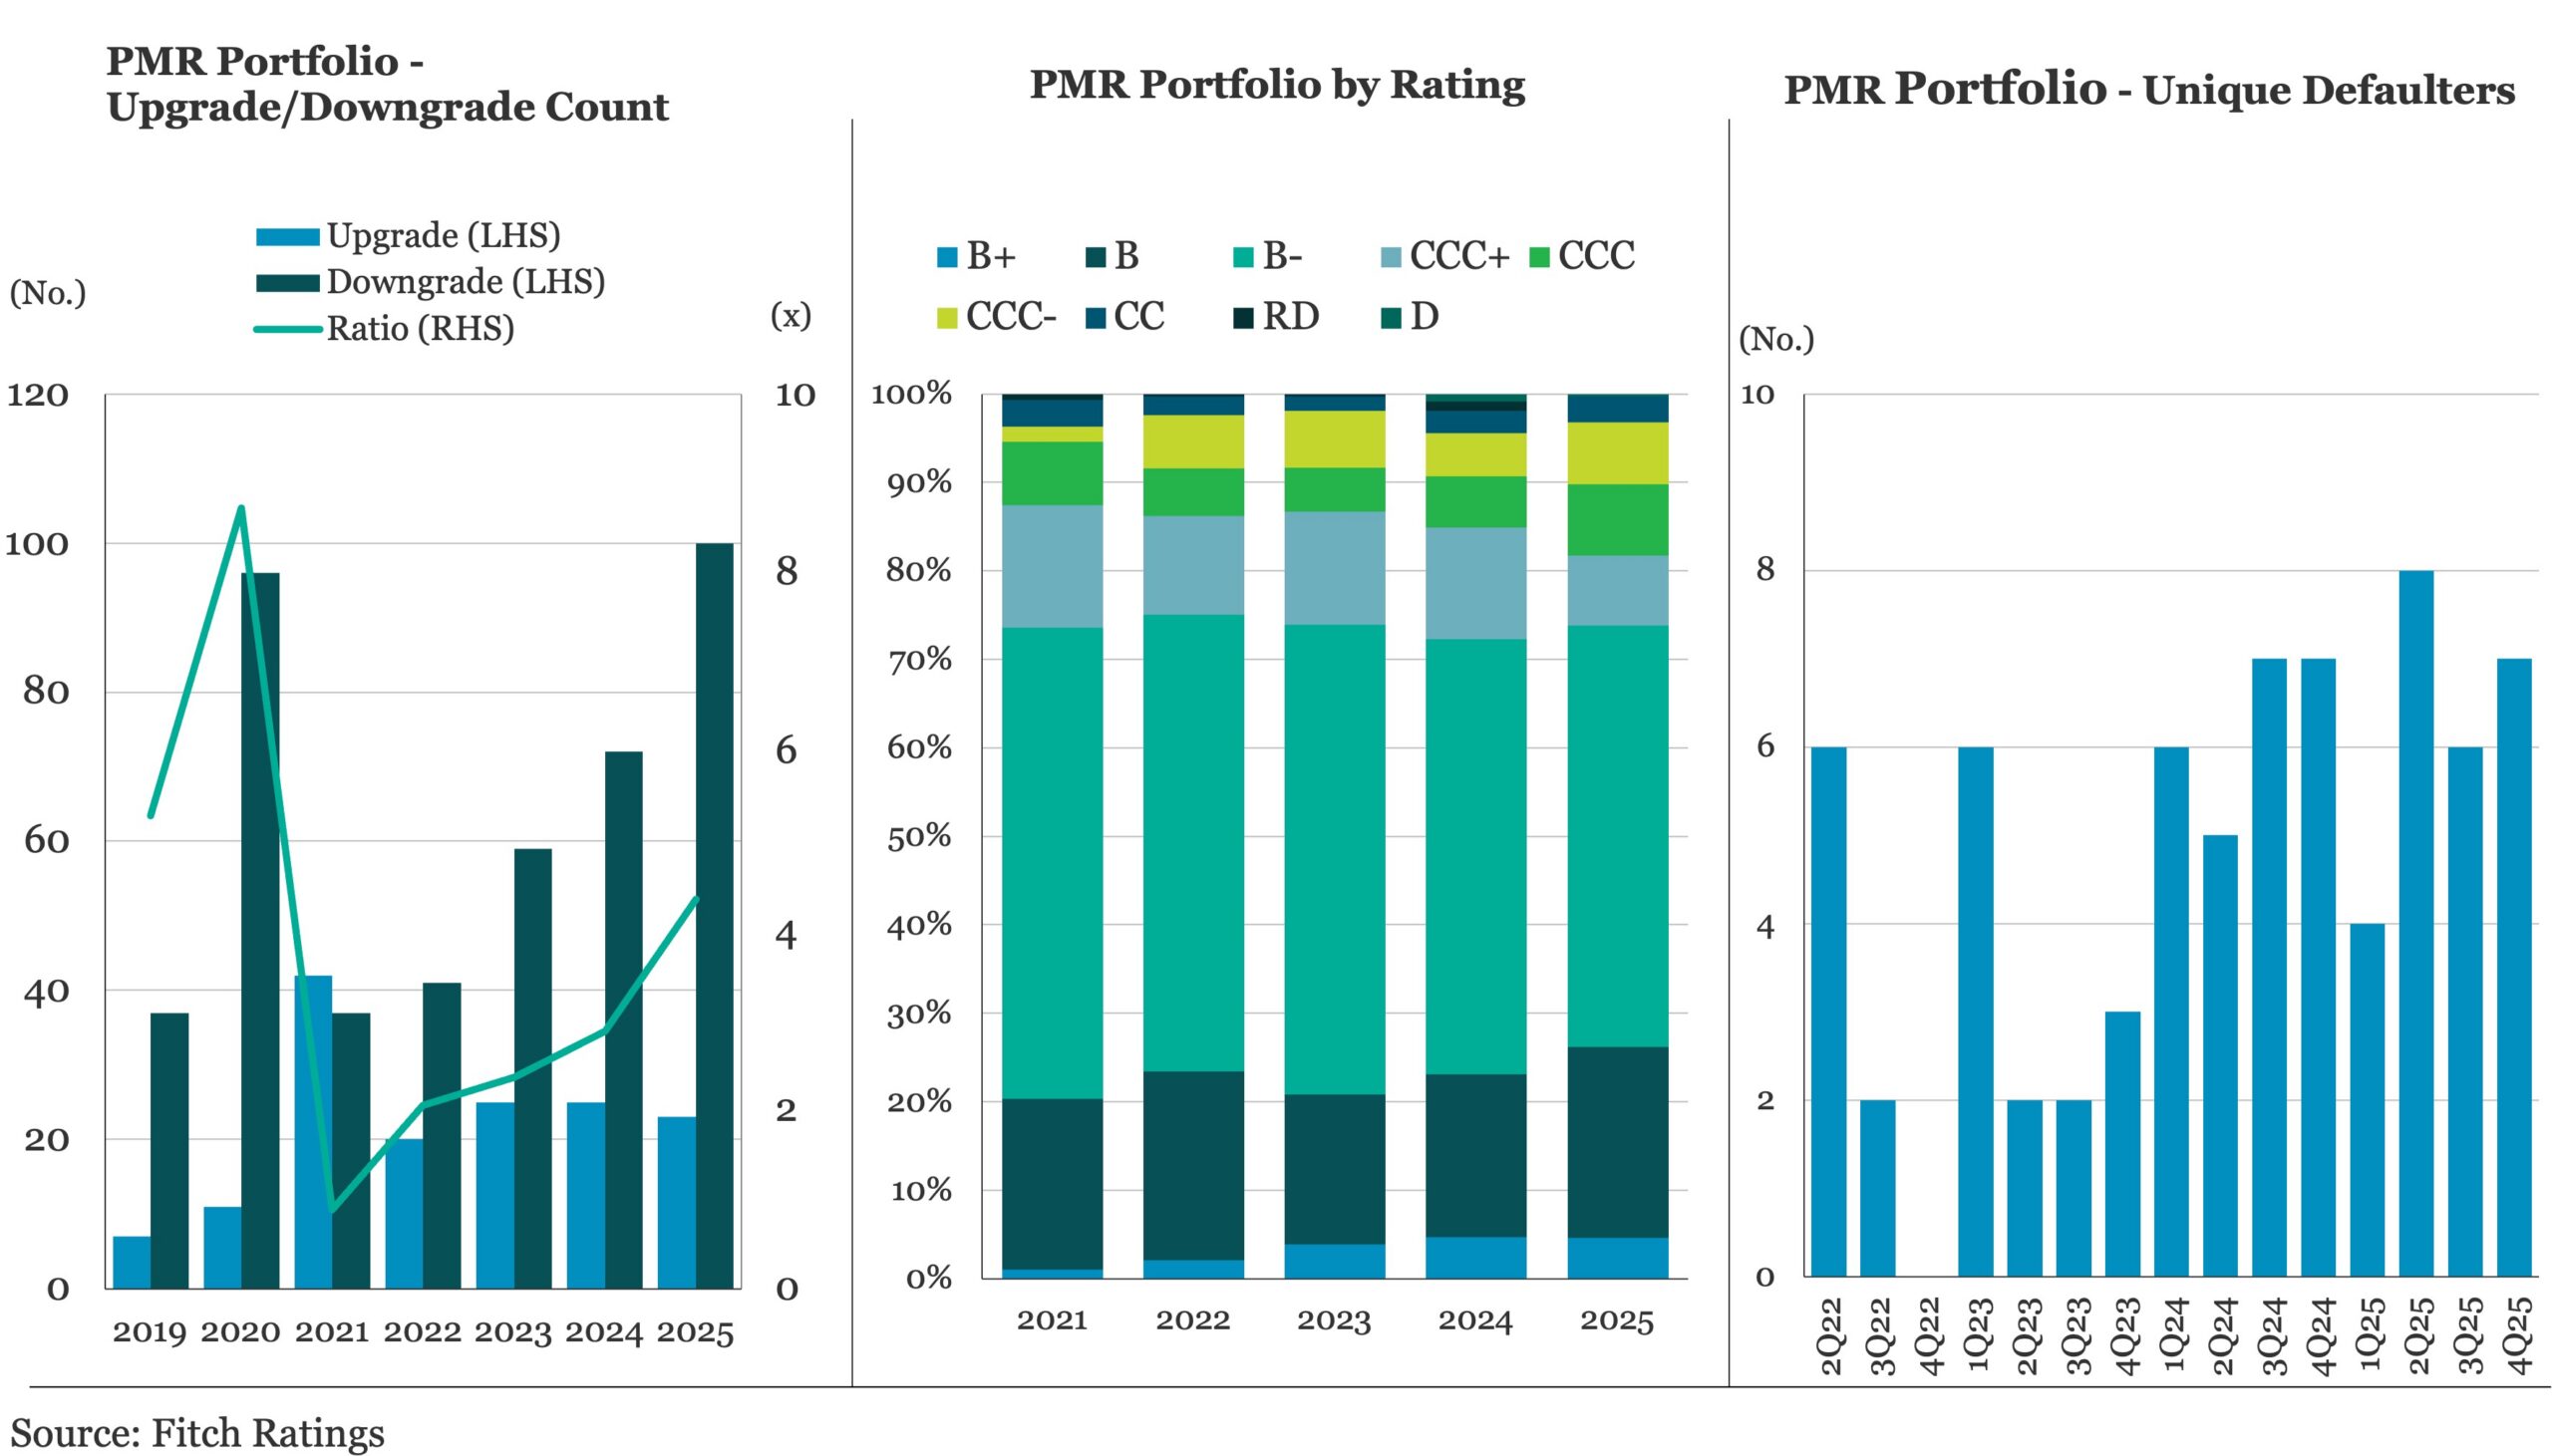
In the charts above, Fitch presents aggregate data for issuers in its PMR portfolio. Fitch privately rates these issuers on behalf of asset managers.
- Fitch recorded 25 downgrades and 5 upgrades in 4Q25, continuing the trend of downgrades outpacing upgrades throughout the year.
- The downgrade-to-upgrade ratio decreased to 5.0x in 4Q25 from 5.5x in 3Q25 but remains above the 3.2x ratio recorded in 4Q24.
- The TTM PMR default rate climbed to 9.2% in 4Q25 from 8.4% in 3Q25, but remained lower than the 9.3% recorded in November 2025. Fitch recorded 28 unique defaulters over the TTM period ending 4Q25, up from 25 for the TTM period ending 3Q25.
- Including repeat defaults by the same issuer, Fitch recorded 40 default events in the TTM period ending 4Q25. Six defaults involved Chapter 11 bankruptcy, liquidations, or out-of-court restructurings. Nineteen cases featured interest deferrals or conversions of cash interest to payment-in-kind. Eleven events involved extending maturities under financial stress and four defaults stemmed from uncured payment defaults.
Contact Brad Hamner



Latest news


Information technology topped nonaccruals on a cost basis
October 14, 2026
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
October 14, 2026
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.