


Click here to learn more.
Private Credit Default Rate (PCDR)
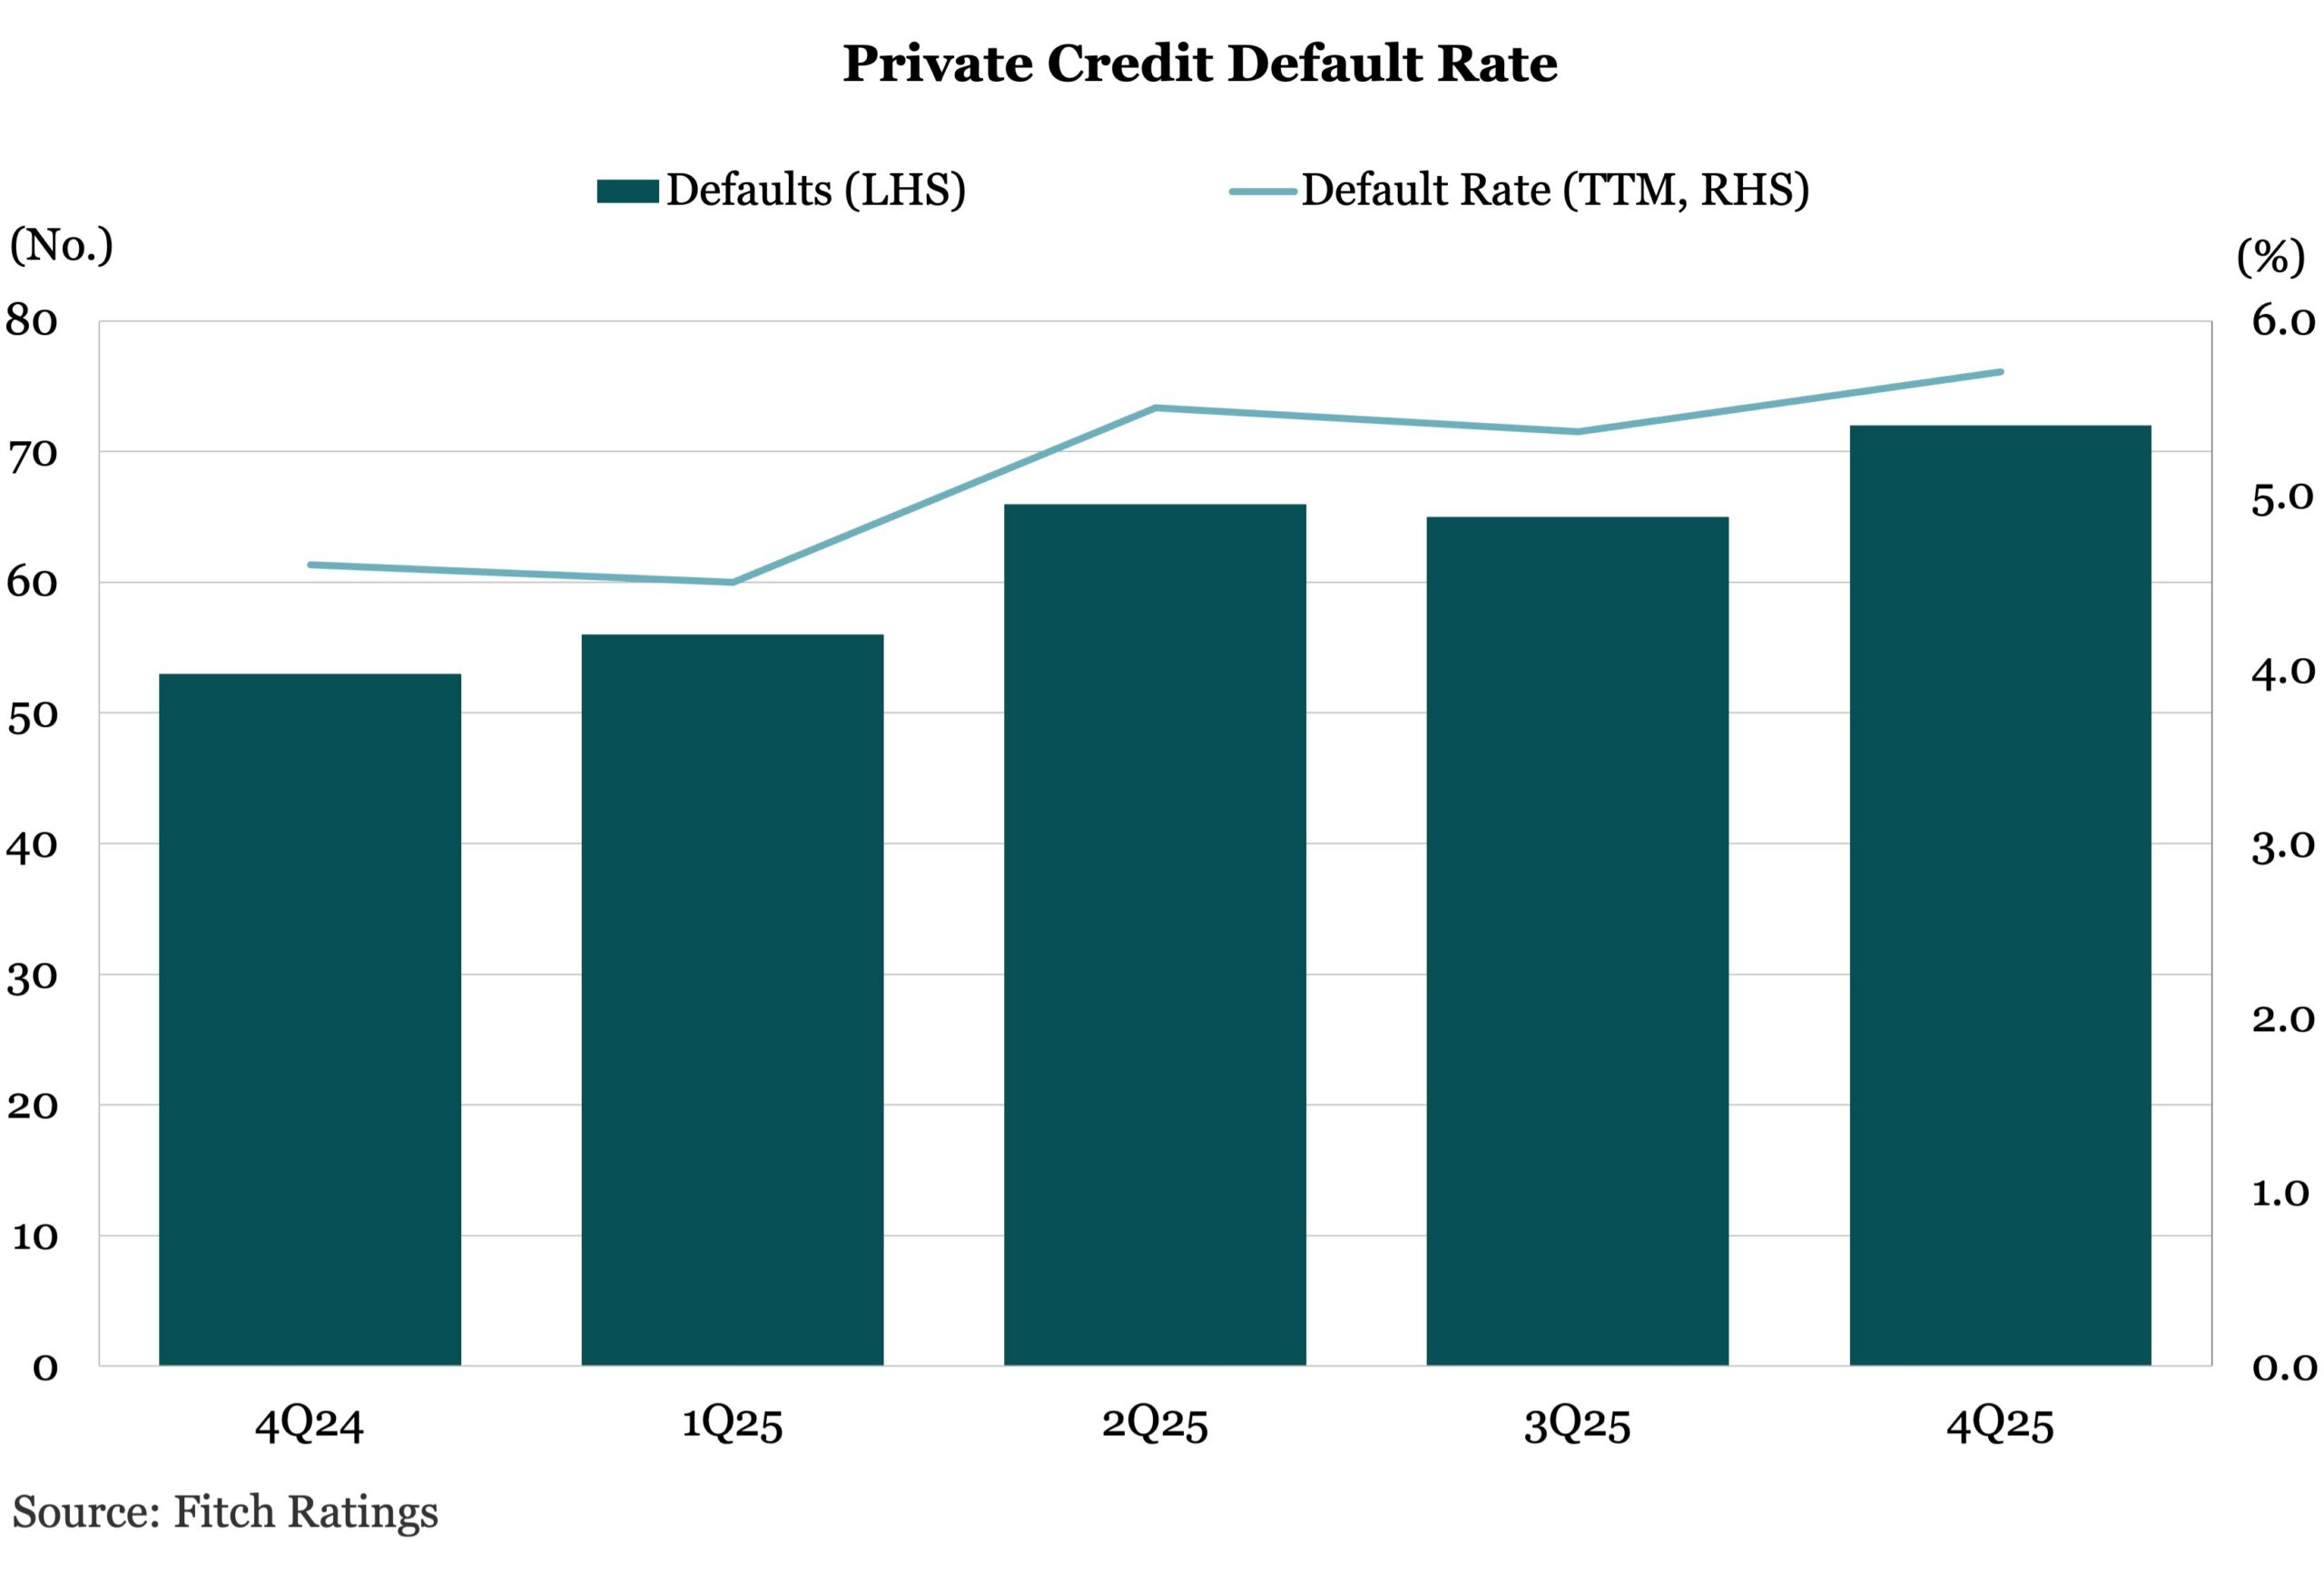
- The U.S. PCDR rose to 5.6% for the TTM ending 4Q25, the second-highest level since tracking began in August 2024. This is just below the peak of 5.7% seen in both February and November 2025, but up from 5.4% in 3Q25.
- The PCDR comprises two components: the Model-based Credit Opinion (MCO) default rate and the Privately Monitored Rating (PMR) default rate. In 4Q25, the MCO default rate increased to 4.5% from 4.4% in 3Q25, while the PMR default rate jumped to 9.2% from 8.4%.
- Within the PCDR, Fitch recorded 23 private credit default events from 18 new unique defaulters in 4Q25, bringing the TTM total to 71 unique defaulters, up from 65 total unique defaulters over the TTM period ending 3Q25.
- Including repeat defaults by the same issuer, Fitch recorded 87 default events in the TTM ending 4Q25. Interest payment deferrals and the introduction of PIK instead of cash interest drove 60% of the default events; stressed maturity extensions accounted for 24%; uncured payment defaults made up 8% of default events; and bankruptcies, liquidations, and out-of-court restructurings represented 8% of default events.
Contact Brad Hamner



Latest news


Information technology topped nonaccruals on a cost basis
October 14, 2026
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
October 14, 2026
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.