


Click here to learn more.
Fitch’s Privately Monitored Ratings (PMR) Portfolio – 4Q25
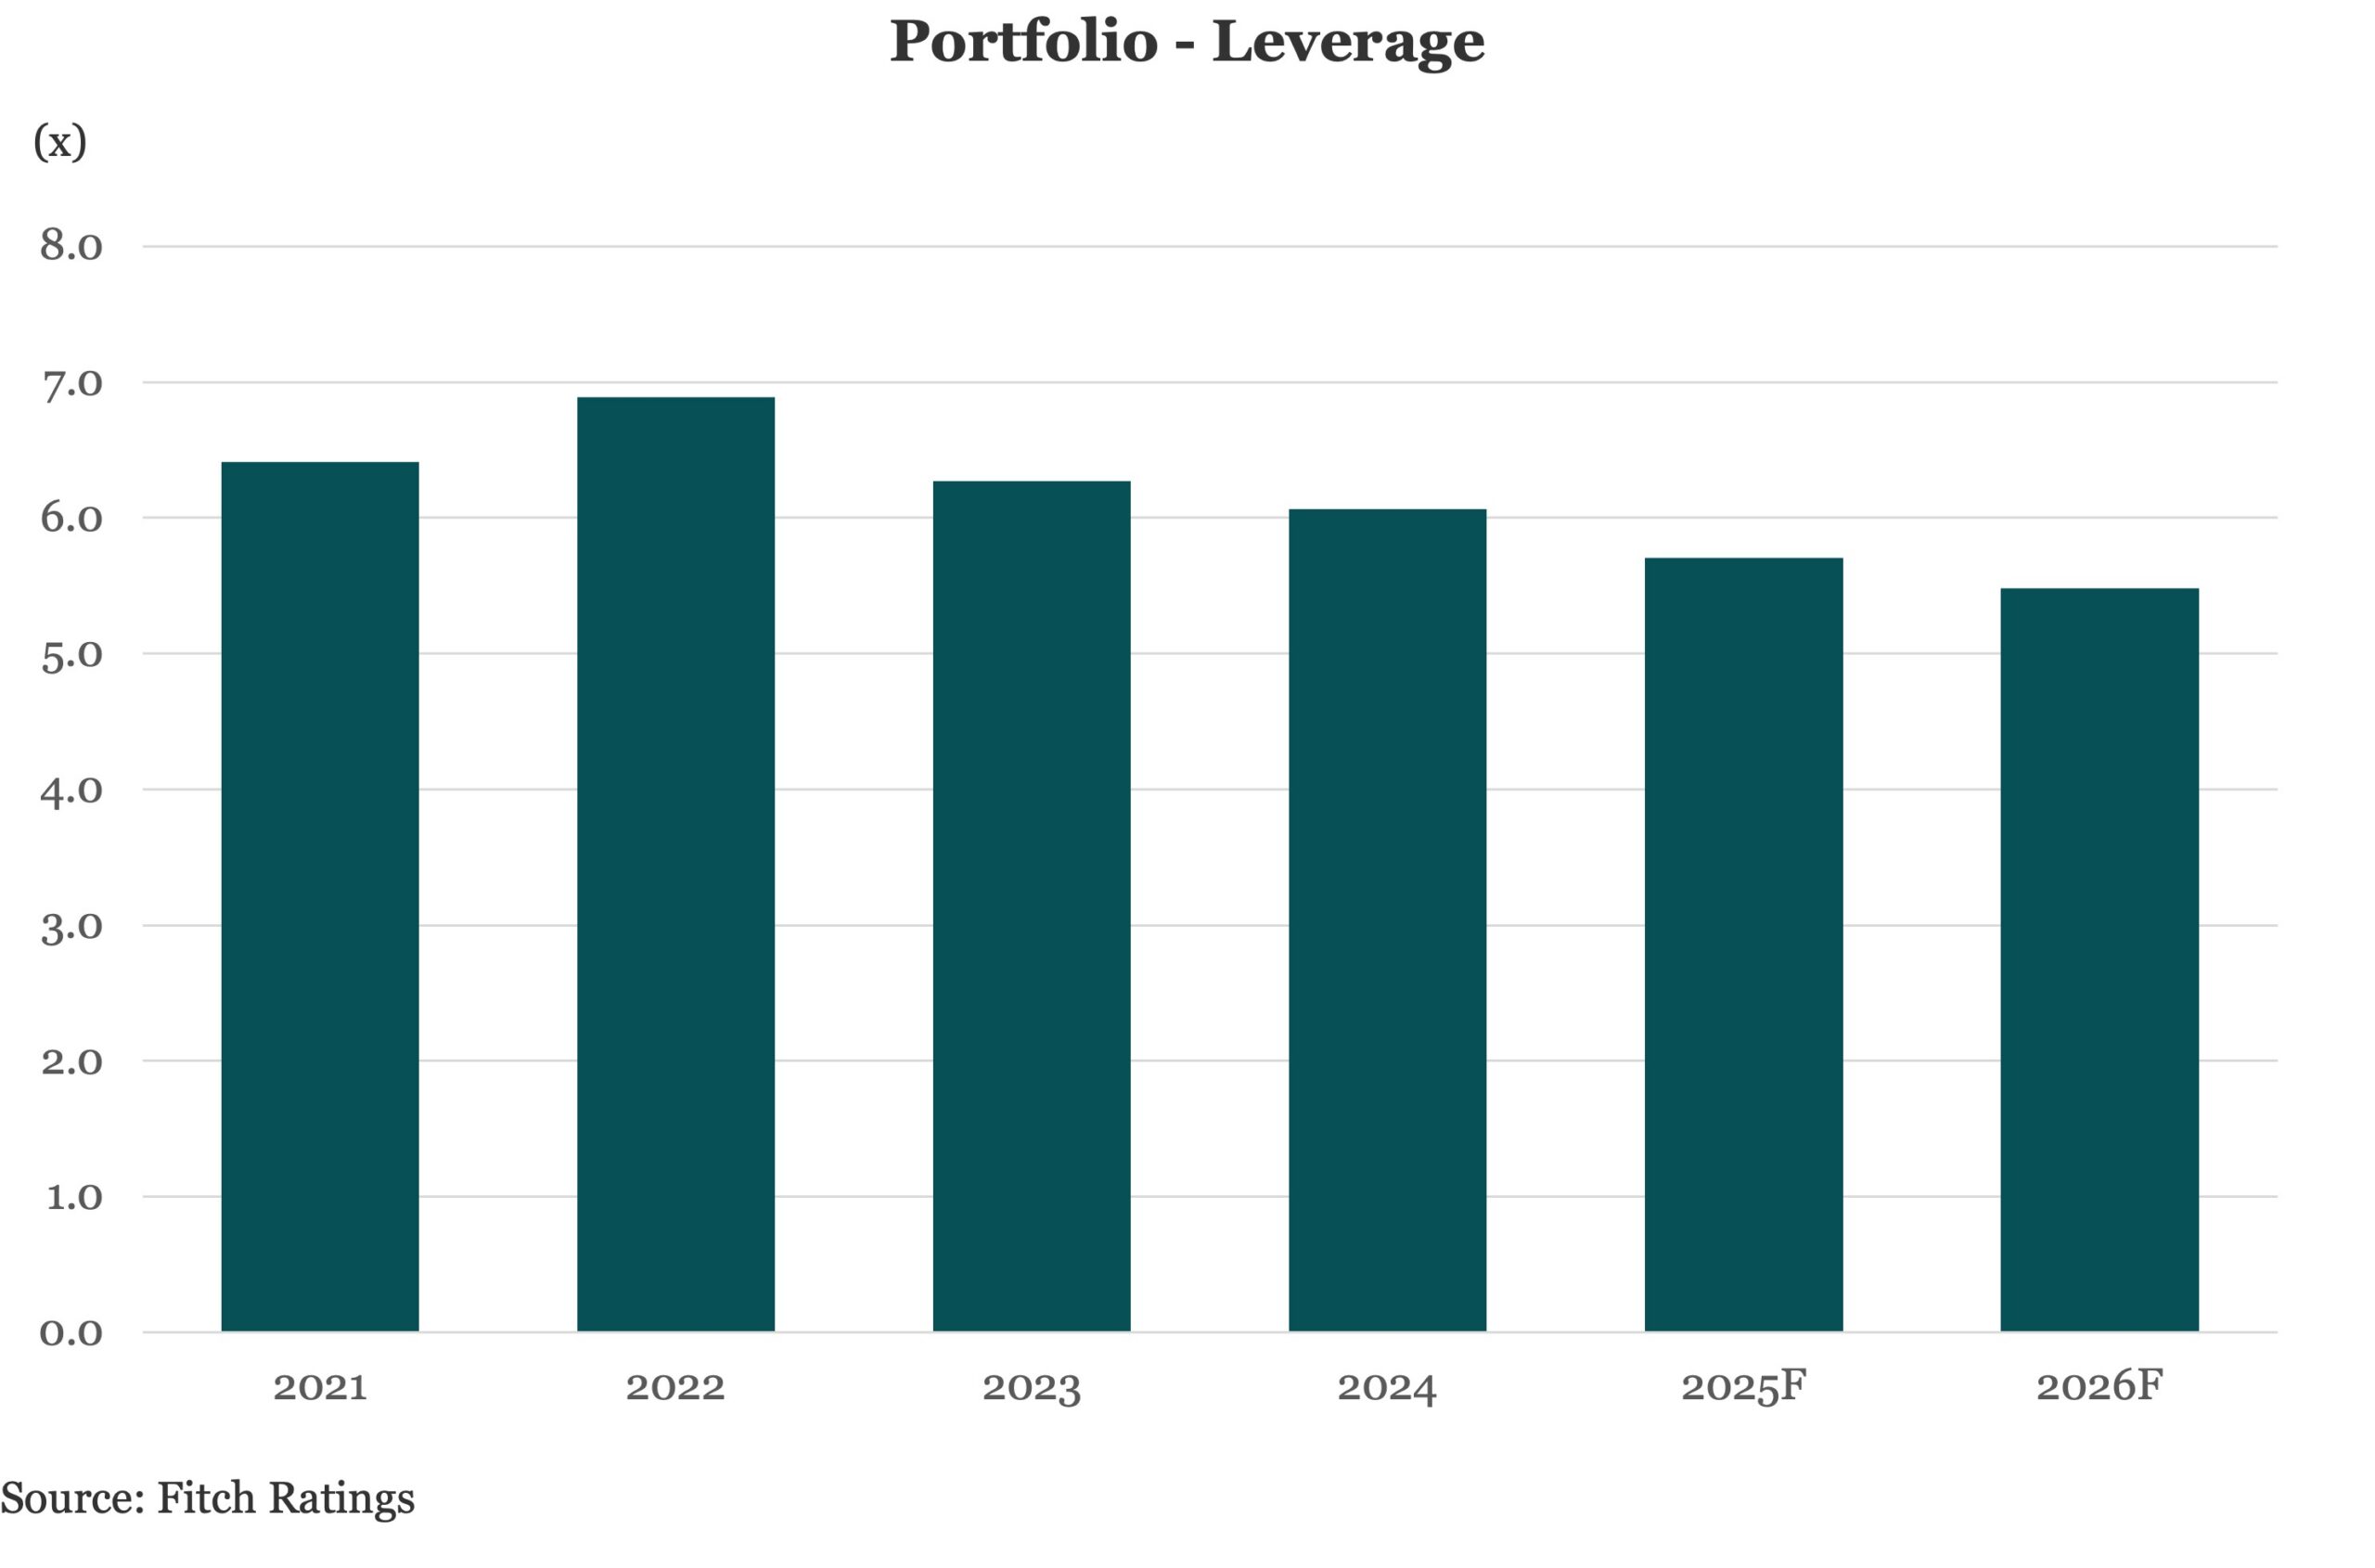
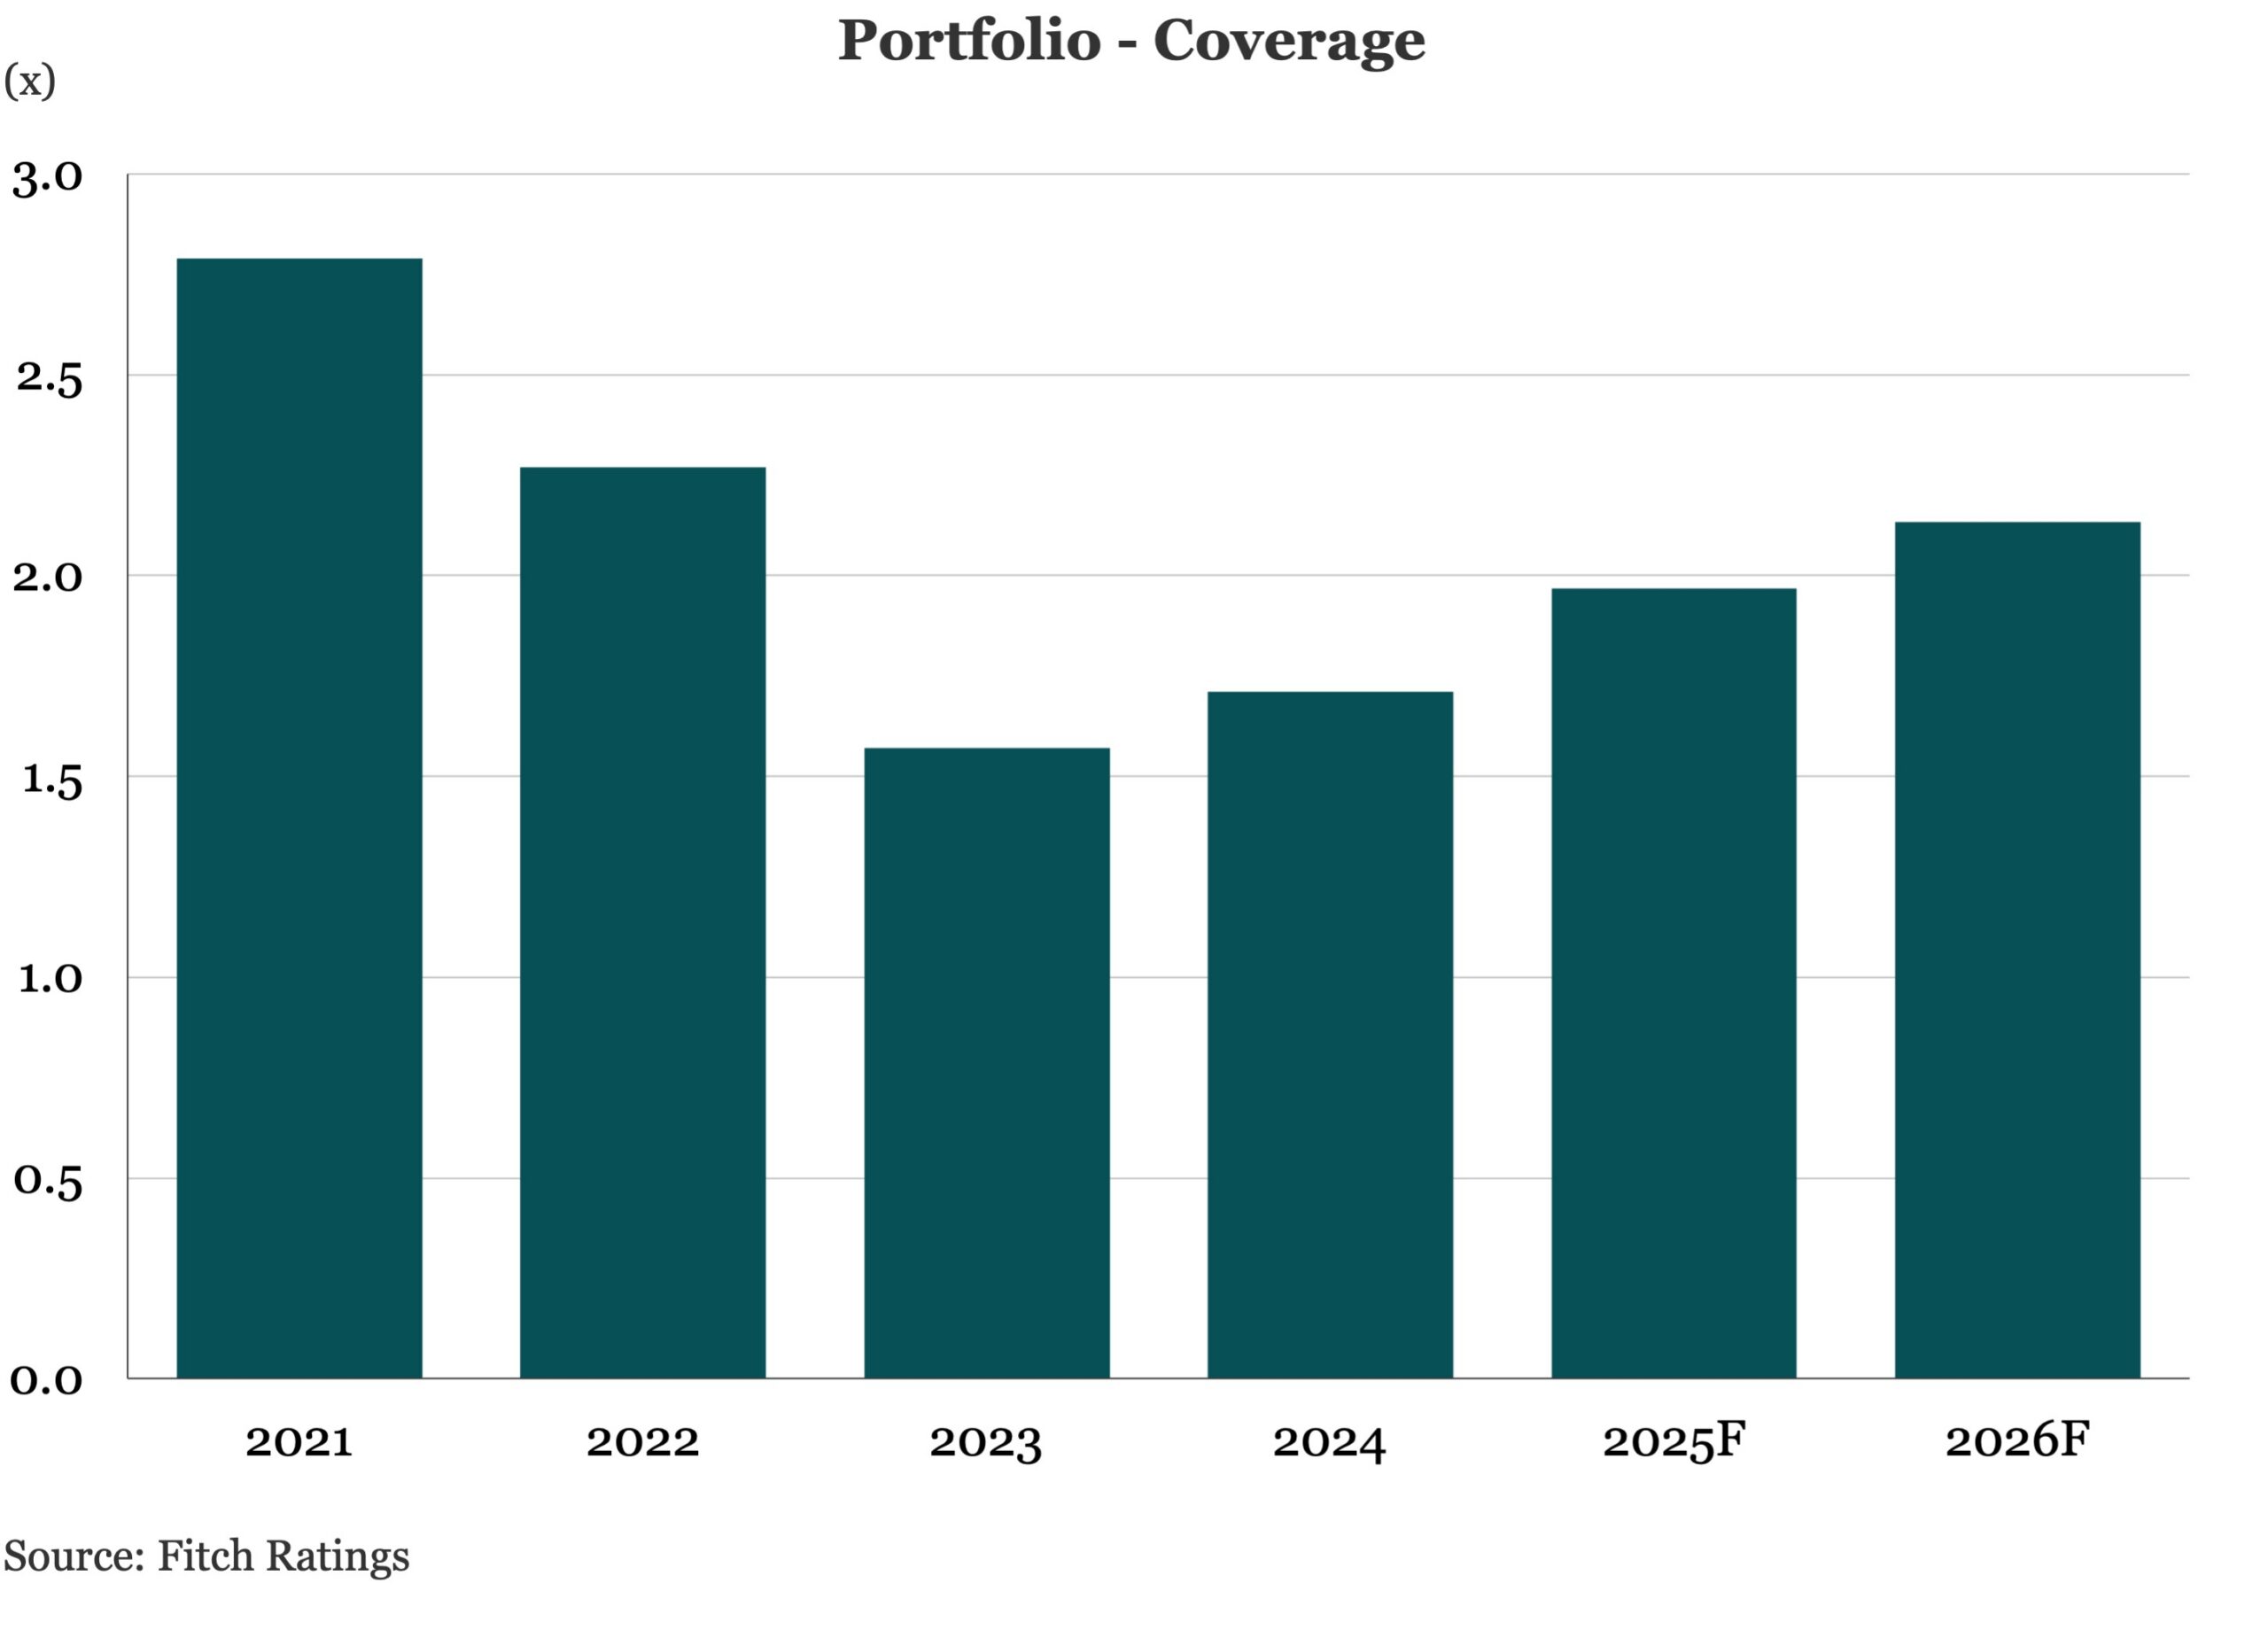
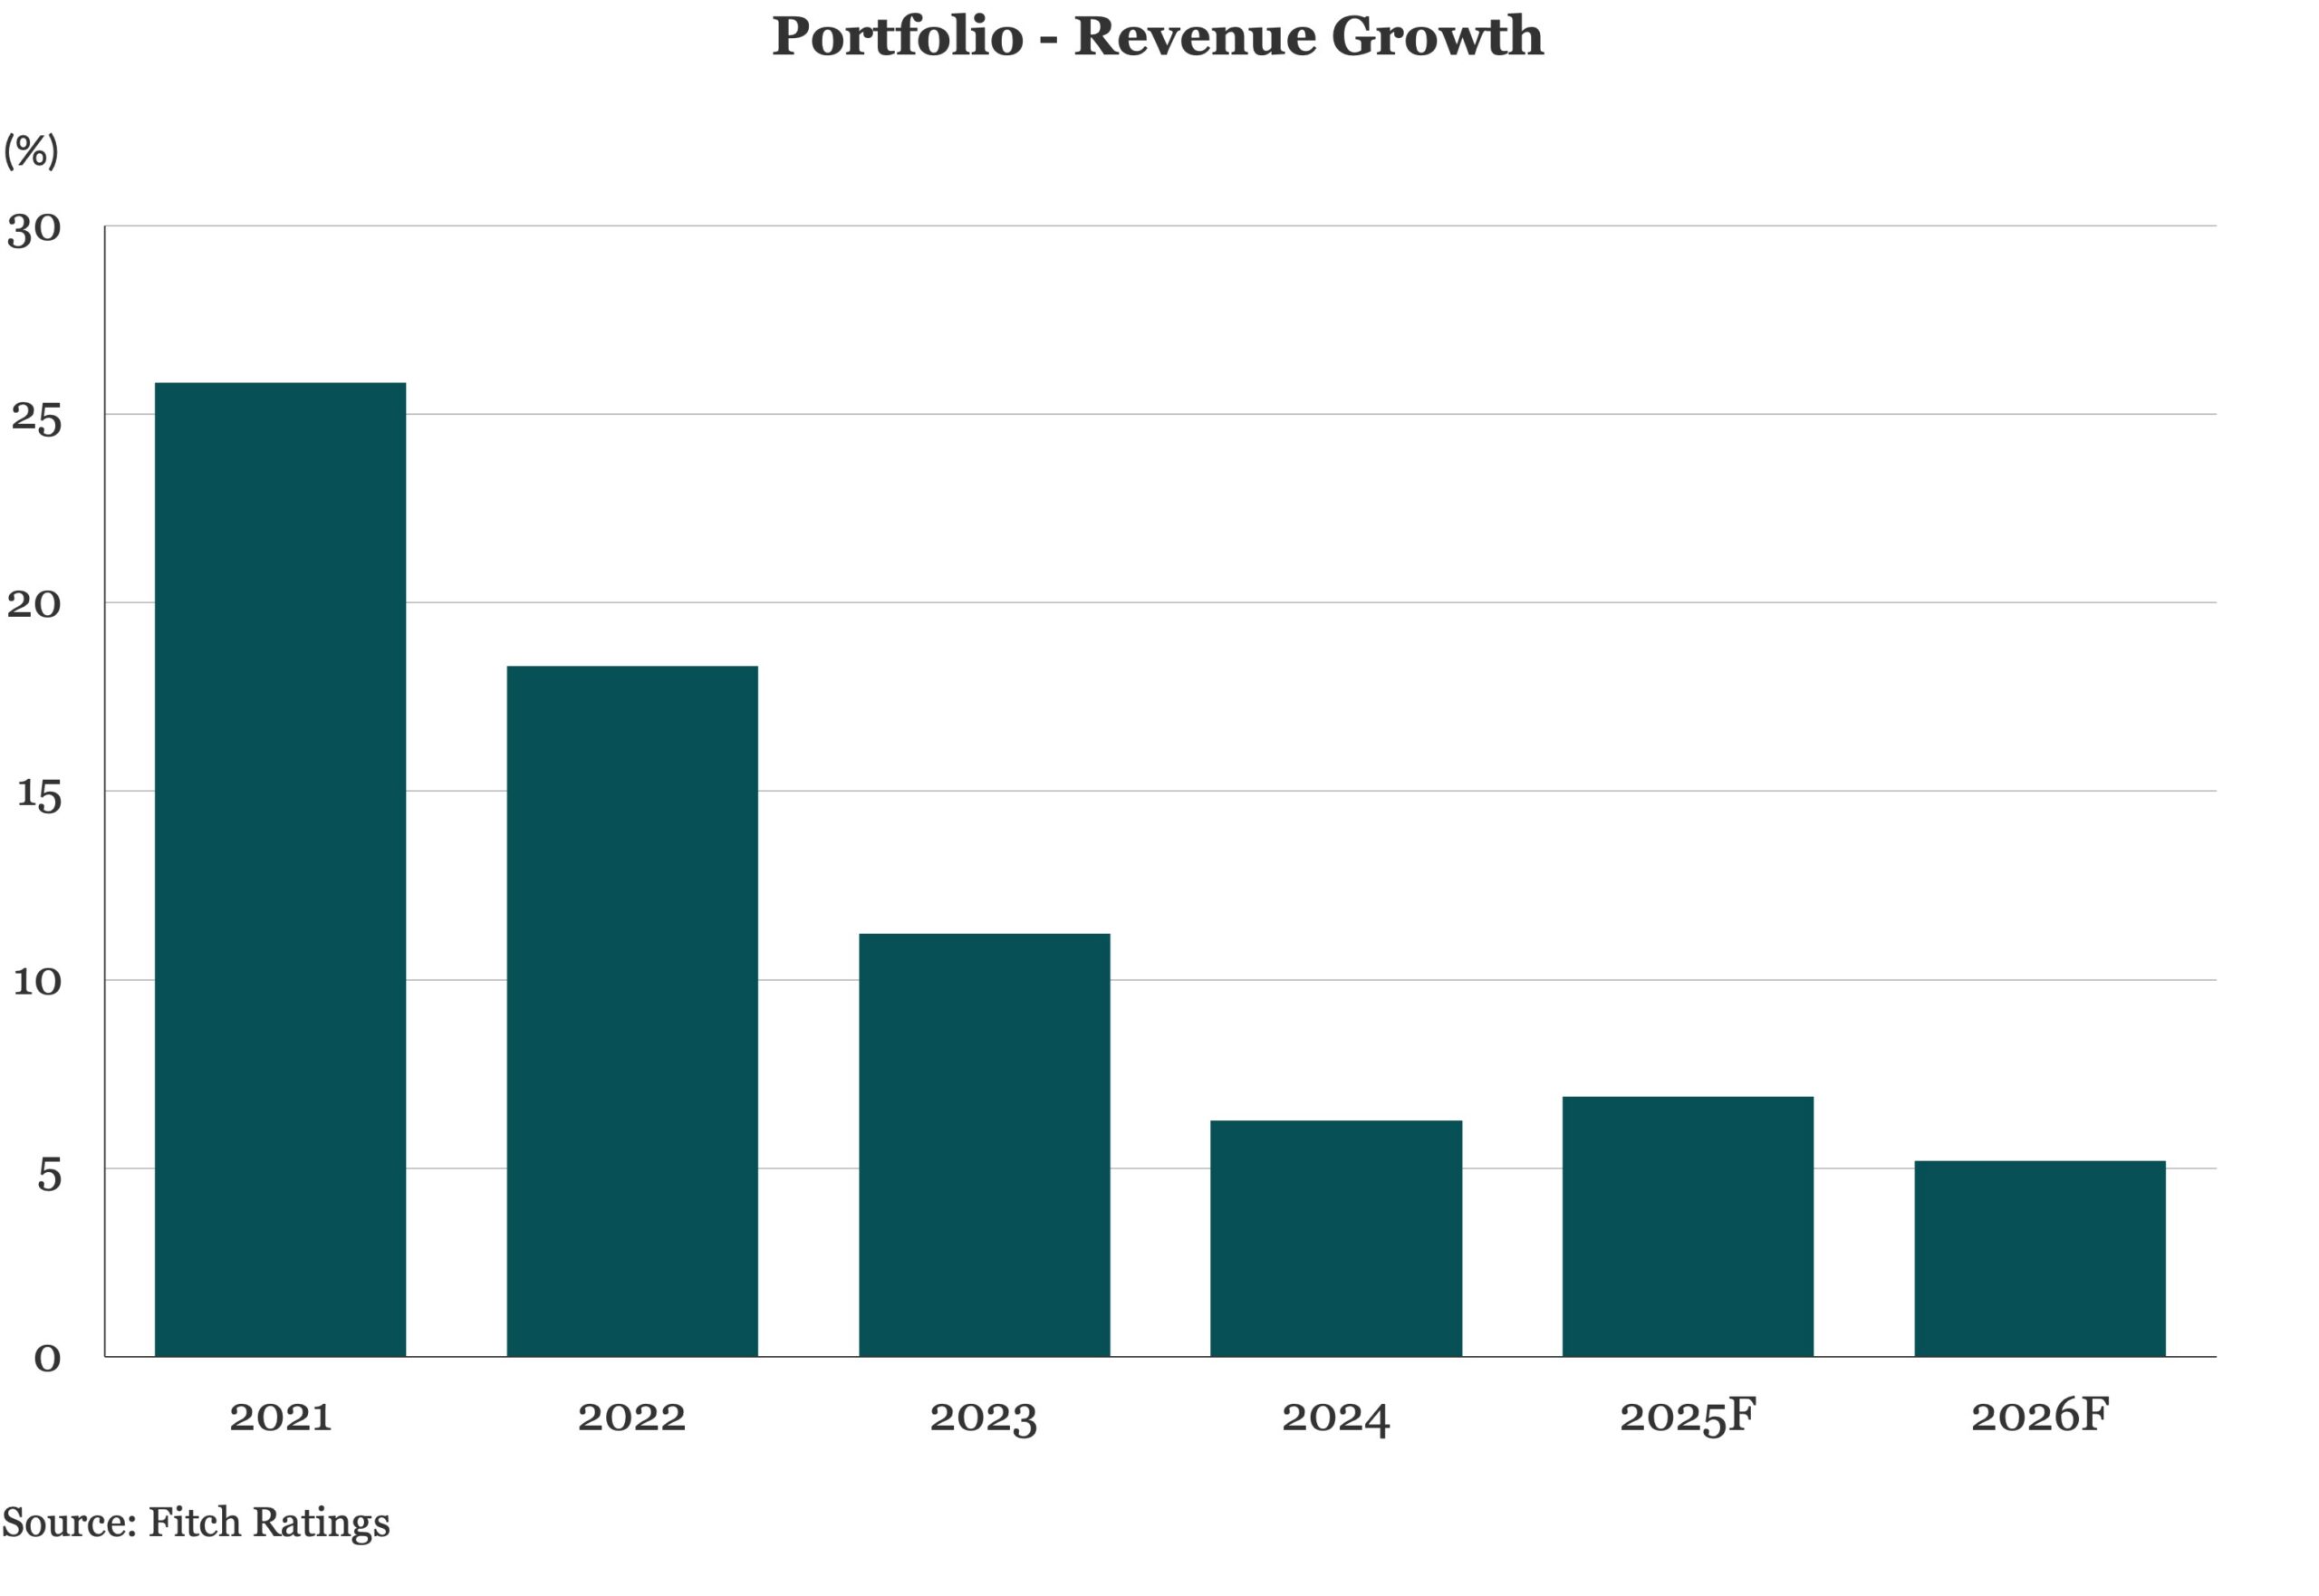
In the charts above, Fitch presents aggregate data for issuers in its PMR portfolio. Fitch privately rates these issuers on behalf of asset managers.
- Fitch forecasts that PMR portfolio median leverage will decline to 5.7x in 2025F from 6.1x in 2024. Diversified manufacturing drive the deleveraging, dropping to 6.1x in 2025F from 8.1x in 2024. By contrast, the consumer sector will see the largest leverage increase, rising to 7.1x in 2025F from 6.1x in 2024. Weak consumer spending has slowed revenue growth and pressured discretionary categories. This leverage increase aligns with the consumer sector’s rising default rate in 2025.
- Fitch forecasts an increase in median interest coverage for the PMR portfolio to 2.0x in 2025F from 1.7x in 2024. Lower rates could provide liquidity relief for highly leveraged issuers with floating-rate capital structures. Further projected Fed rate cuts in 2026 will support further increases in median interest coverage, bringing the federal funds rate to 3.25% by year-end.
- Fitch forecasts 2025F revenue growth of 6.9%, up from its 3Q25 projection of 6.0% and above 2024’s 6.3%. Stabilizing economic conditions and declining interest rates drive the upward revision, despite ongoing policy and geopolitical uncertainty.
Contact Brad Hamner




Latest news

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
September 10, 2026
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.

Reading the Board
September 10, 2026
The story changes depending on which numbers you’re counting.
Private Credit Defaults 101: Different Numbers, Different Stories
In Season 2 of Billions, Bobby Axelrod takes his lawyer Orrin Bach to an empty Yonkers racetrack in the dead of night.