


US Private Credit Defaults Rose Sharply in 2024 While Lender Losses Remained Limited
Click here to learn more.
Join Fitch Rating upcoming Webinar: The Highs and Lows of Private Credit Defaults and Recoveries
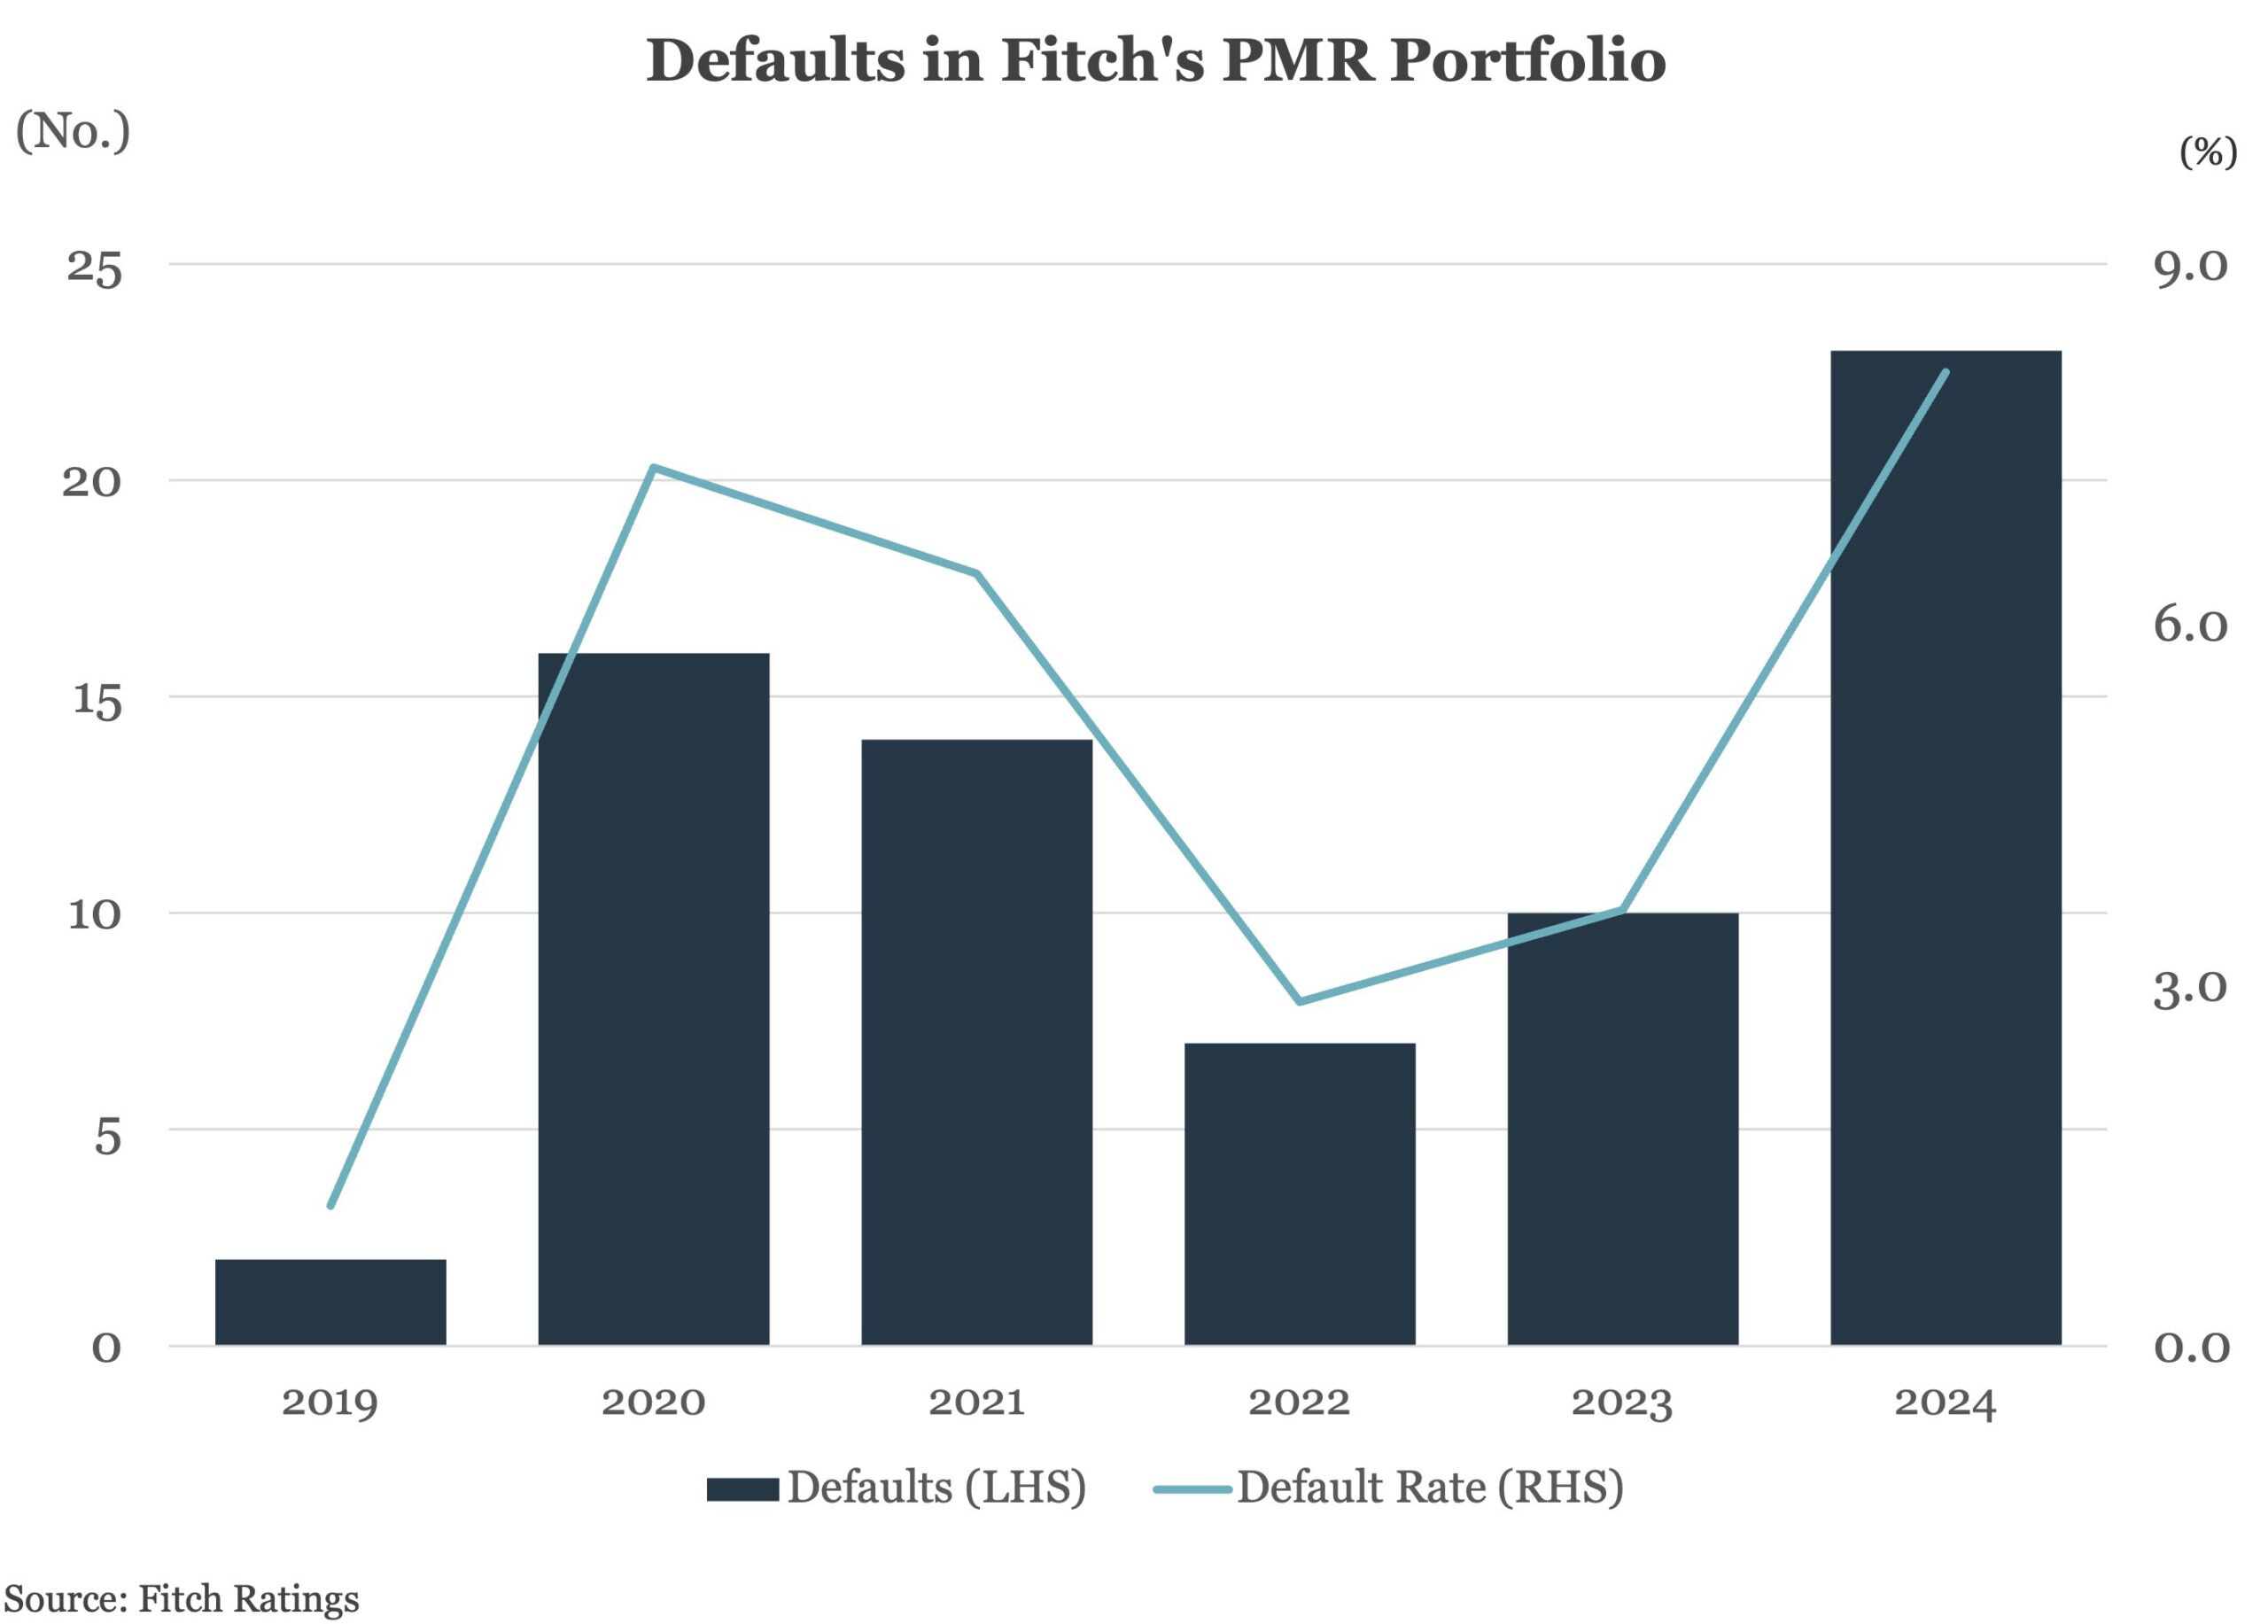
The default rate in Fitch Ratings’ portfolio of U.S. privately monitored ratings (PMR) rose sharply to 8.1% in 2024. This is the highest level since Fitch recorded the first default in the portfolio in 2019.
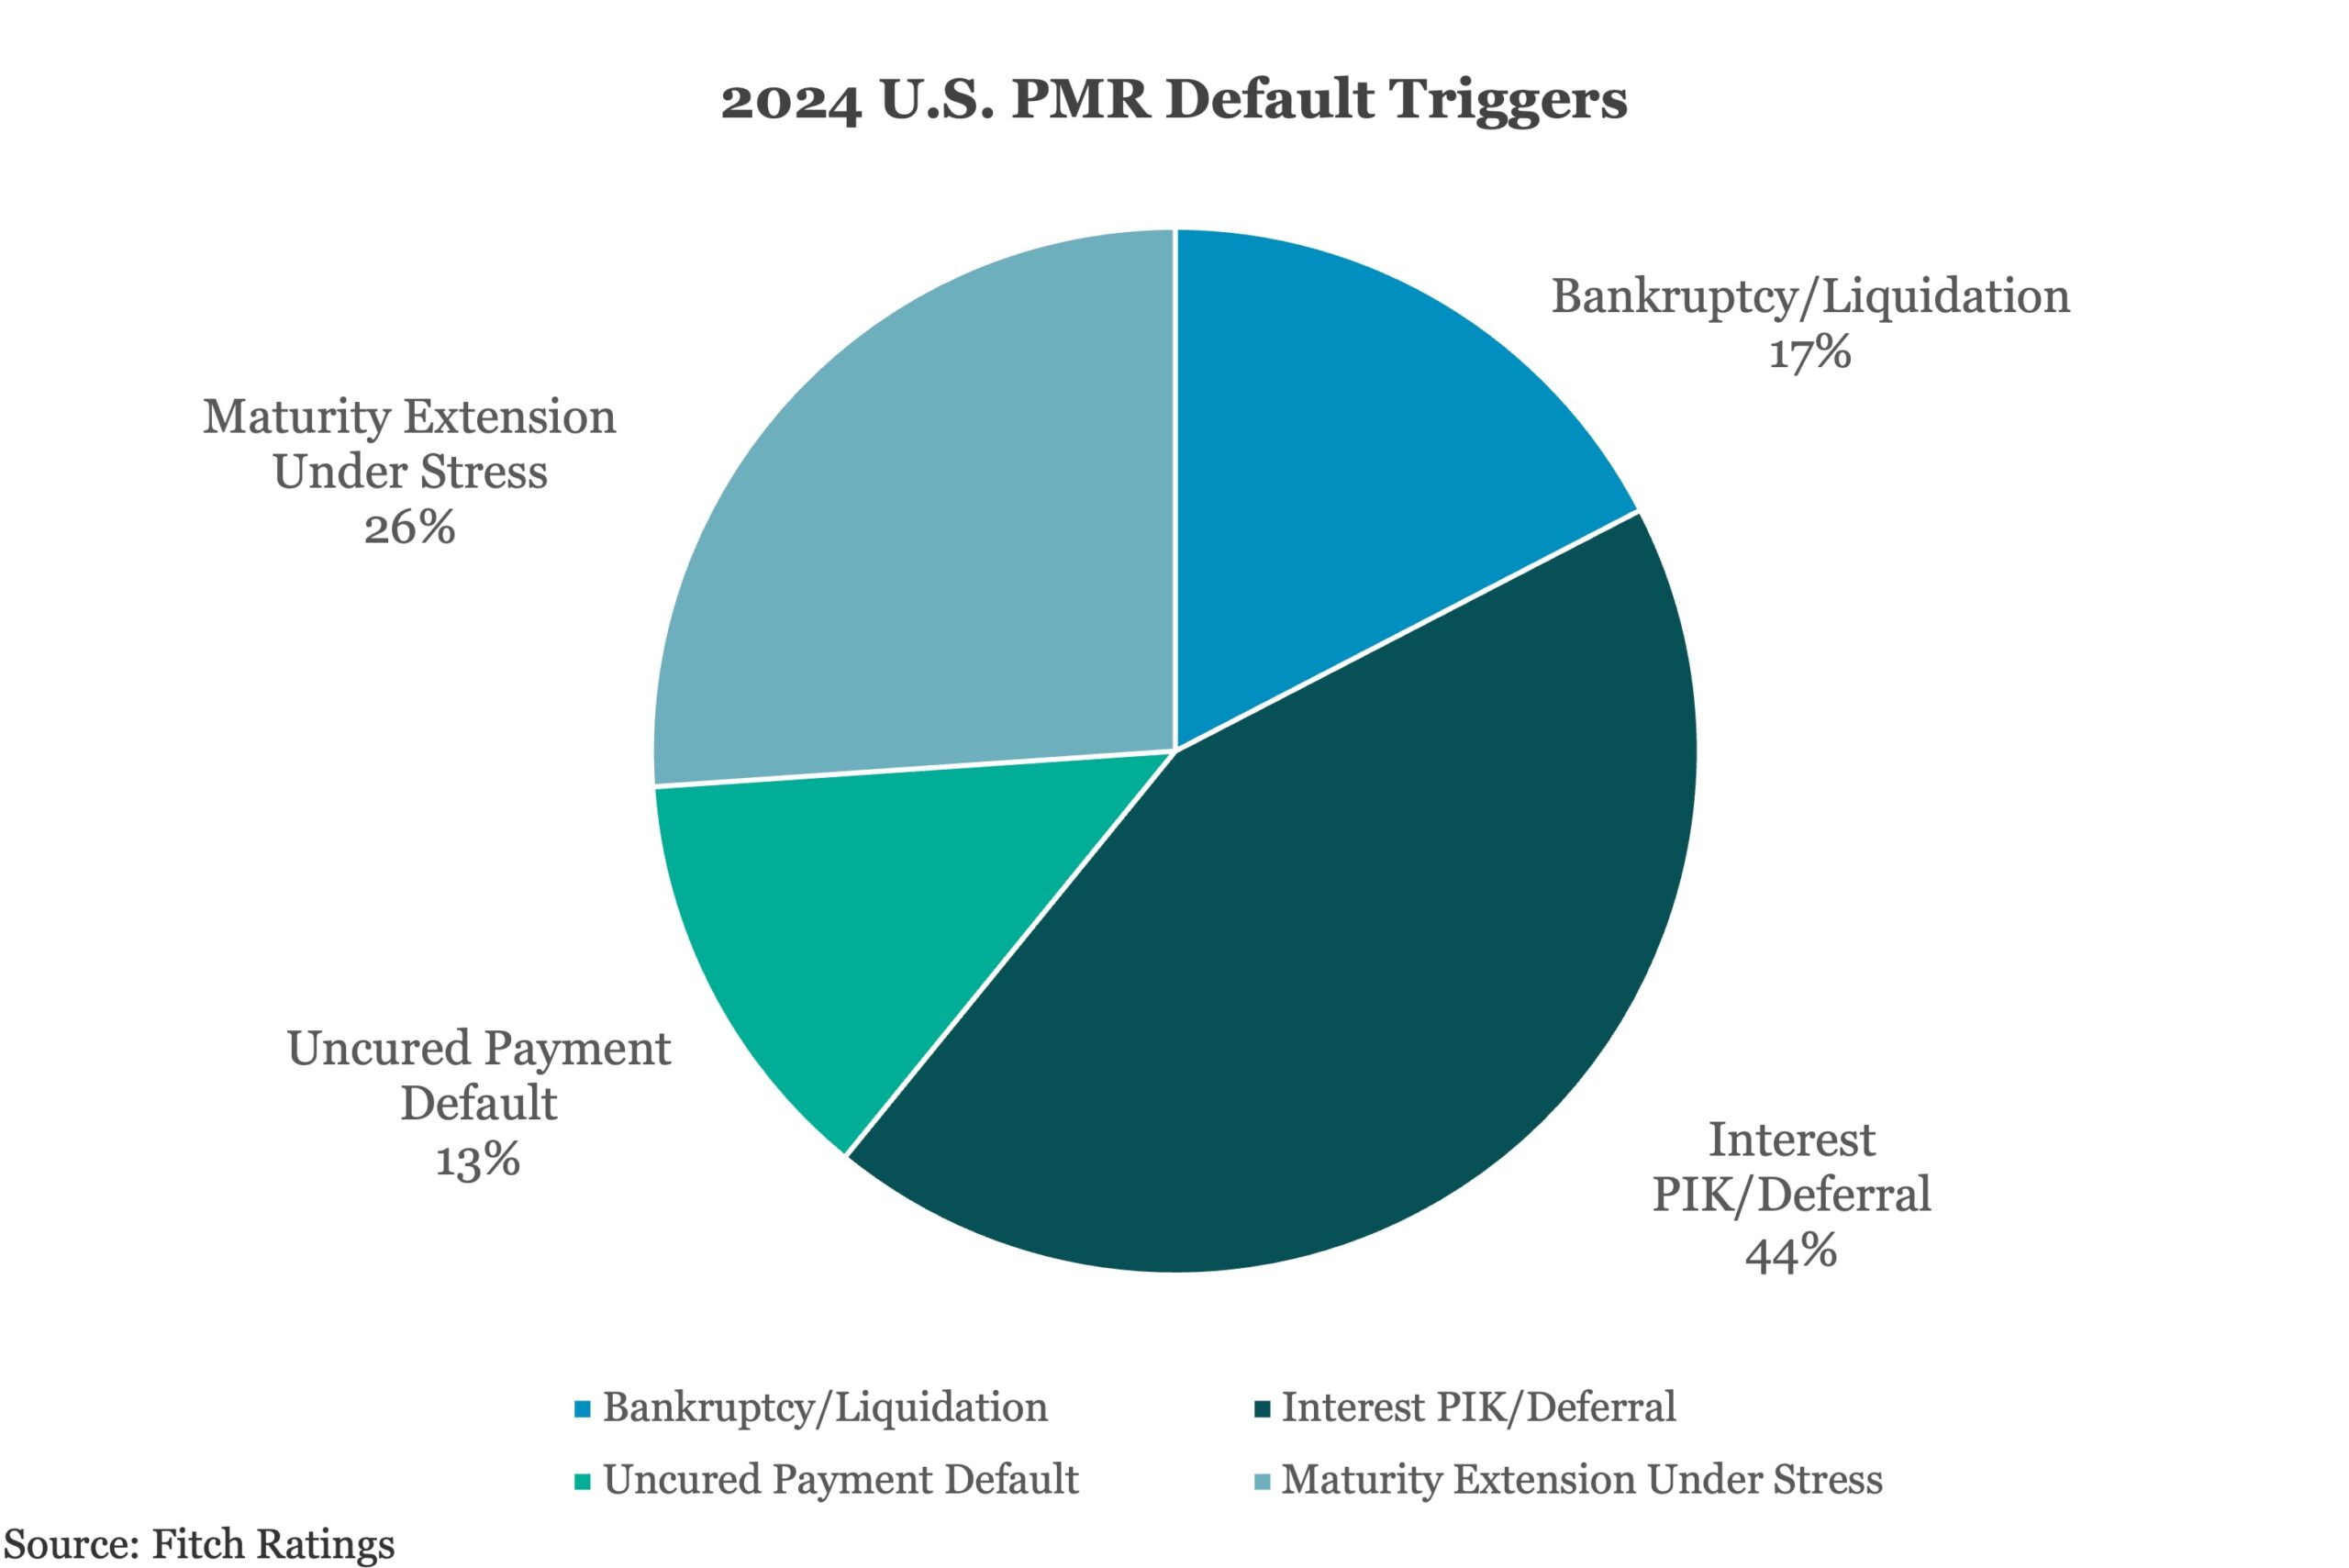
While distressed debt exchanges (DDEs) drove most defaults in 2023, over half of last year’s defaults stemmed from bankruptcy filings and maturity extensions for struggling issuers. Fitch believes much of the increase in default rates in the U.S. PMR portfolio is attributable to the impact of elevated base rates on cash flow and liquidity.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
