


Click here to learn more.
At 9.2%, the default rate within Fitch’s privately monitored ratings (PMR) portfolio exceeded the default rate recorded for Fitch’s broadly syndicated loan (BSL) universe which reached 4.5% for the year. Fitch continues to believe the default rate in the PMR portfolio may be structurally higher than the BSL default rate because sponsors and lenders more often engage in what Fitch considers to be “collaborative defaults,” and because repeat defaulters are more prevalent in private credit.
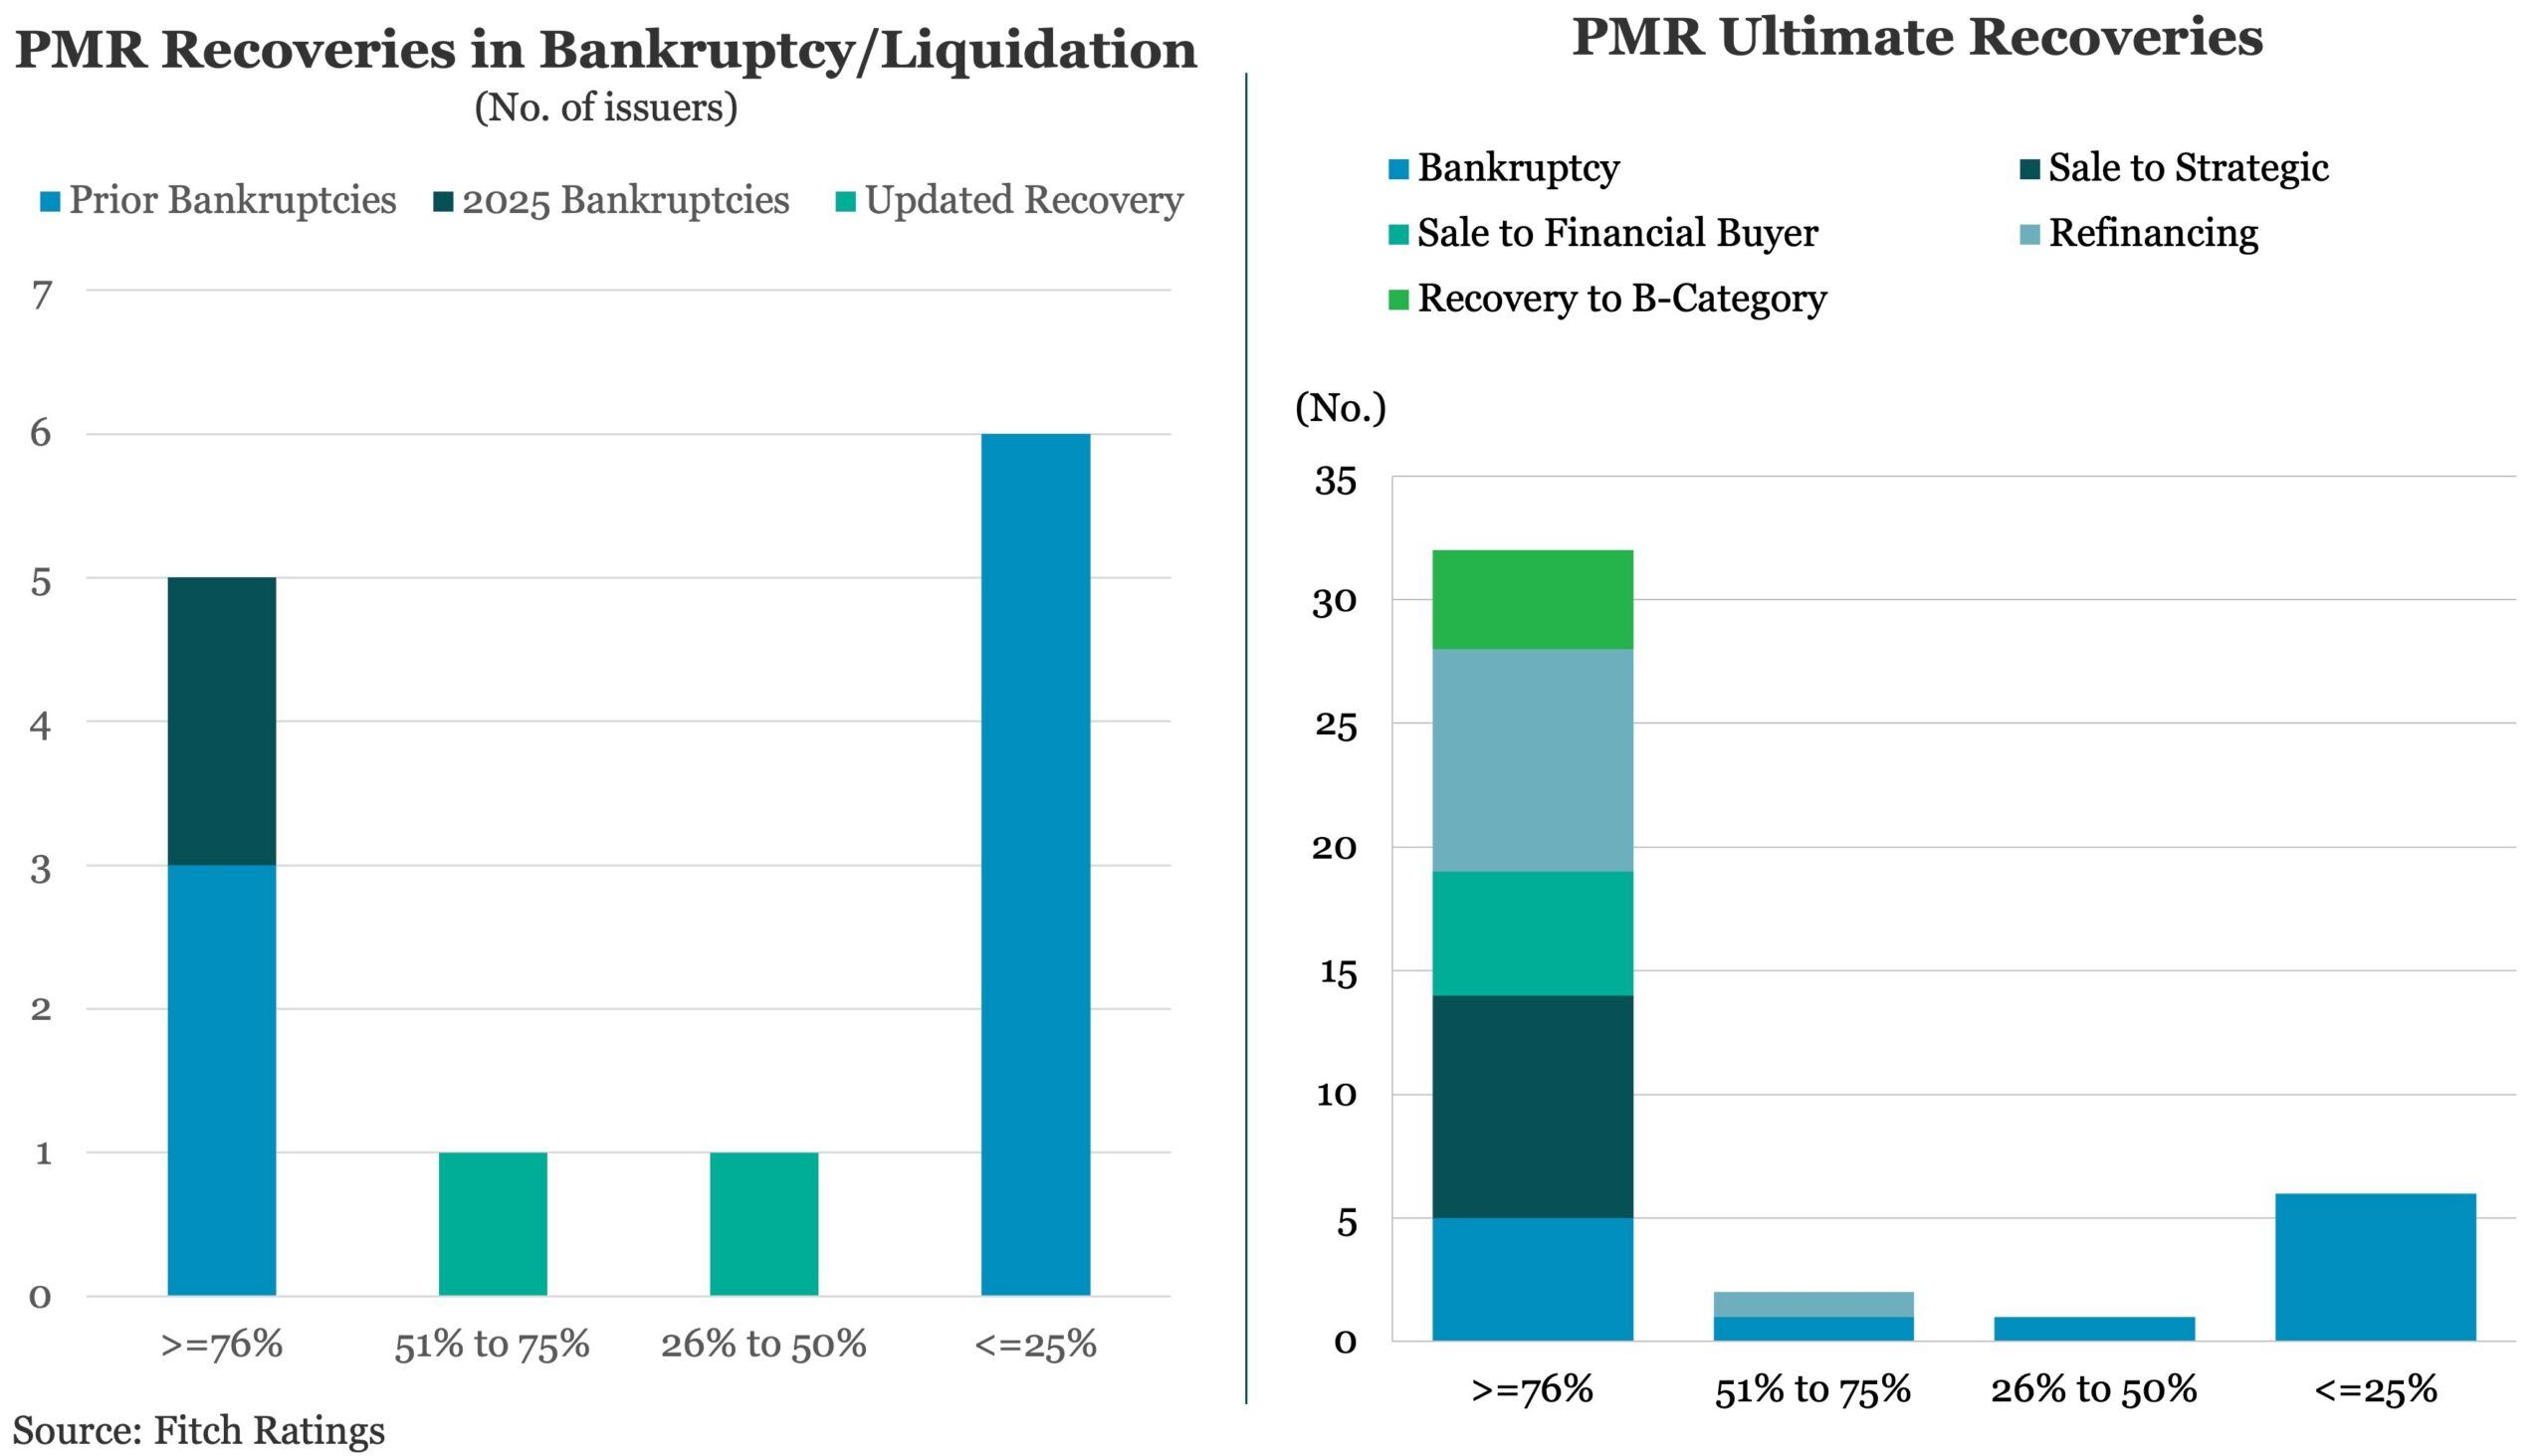
The range of realized recoveries in the 2025 bankruptcies/restructurings and paydowns was high compared to prior years. Entering 2025, of the eleven bankruptcies and restructurings Fitch had observed in the PMR portfolio, just three recovered above 75% while Fitch had expected eight to fall in the 25% or less bucket. Based on developments over the past year, Fitch has reallocated one to the 51% to 75% bucket and another to the 26% to 50% bucket.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
