


AI Disruption Puts Alt-Investment Manager Software Exposures in Focus
Click here to learn more.
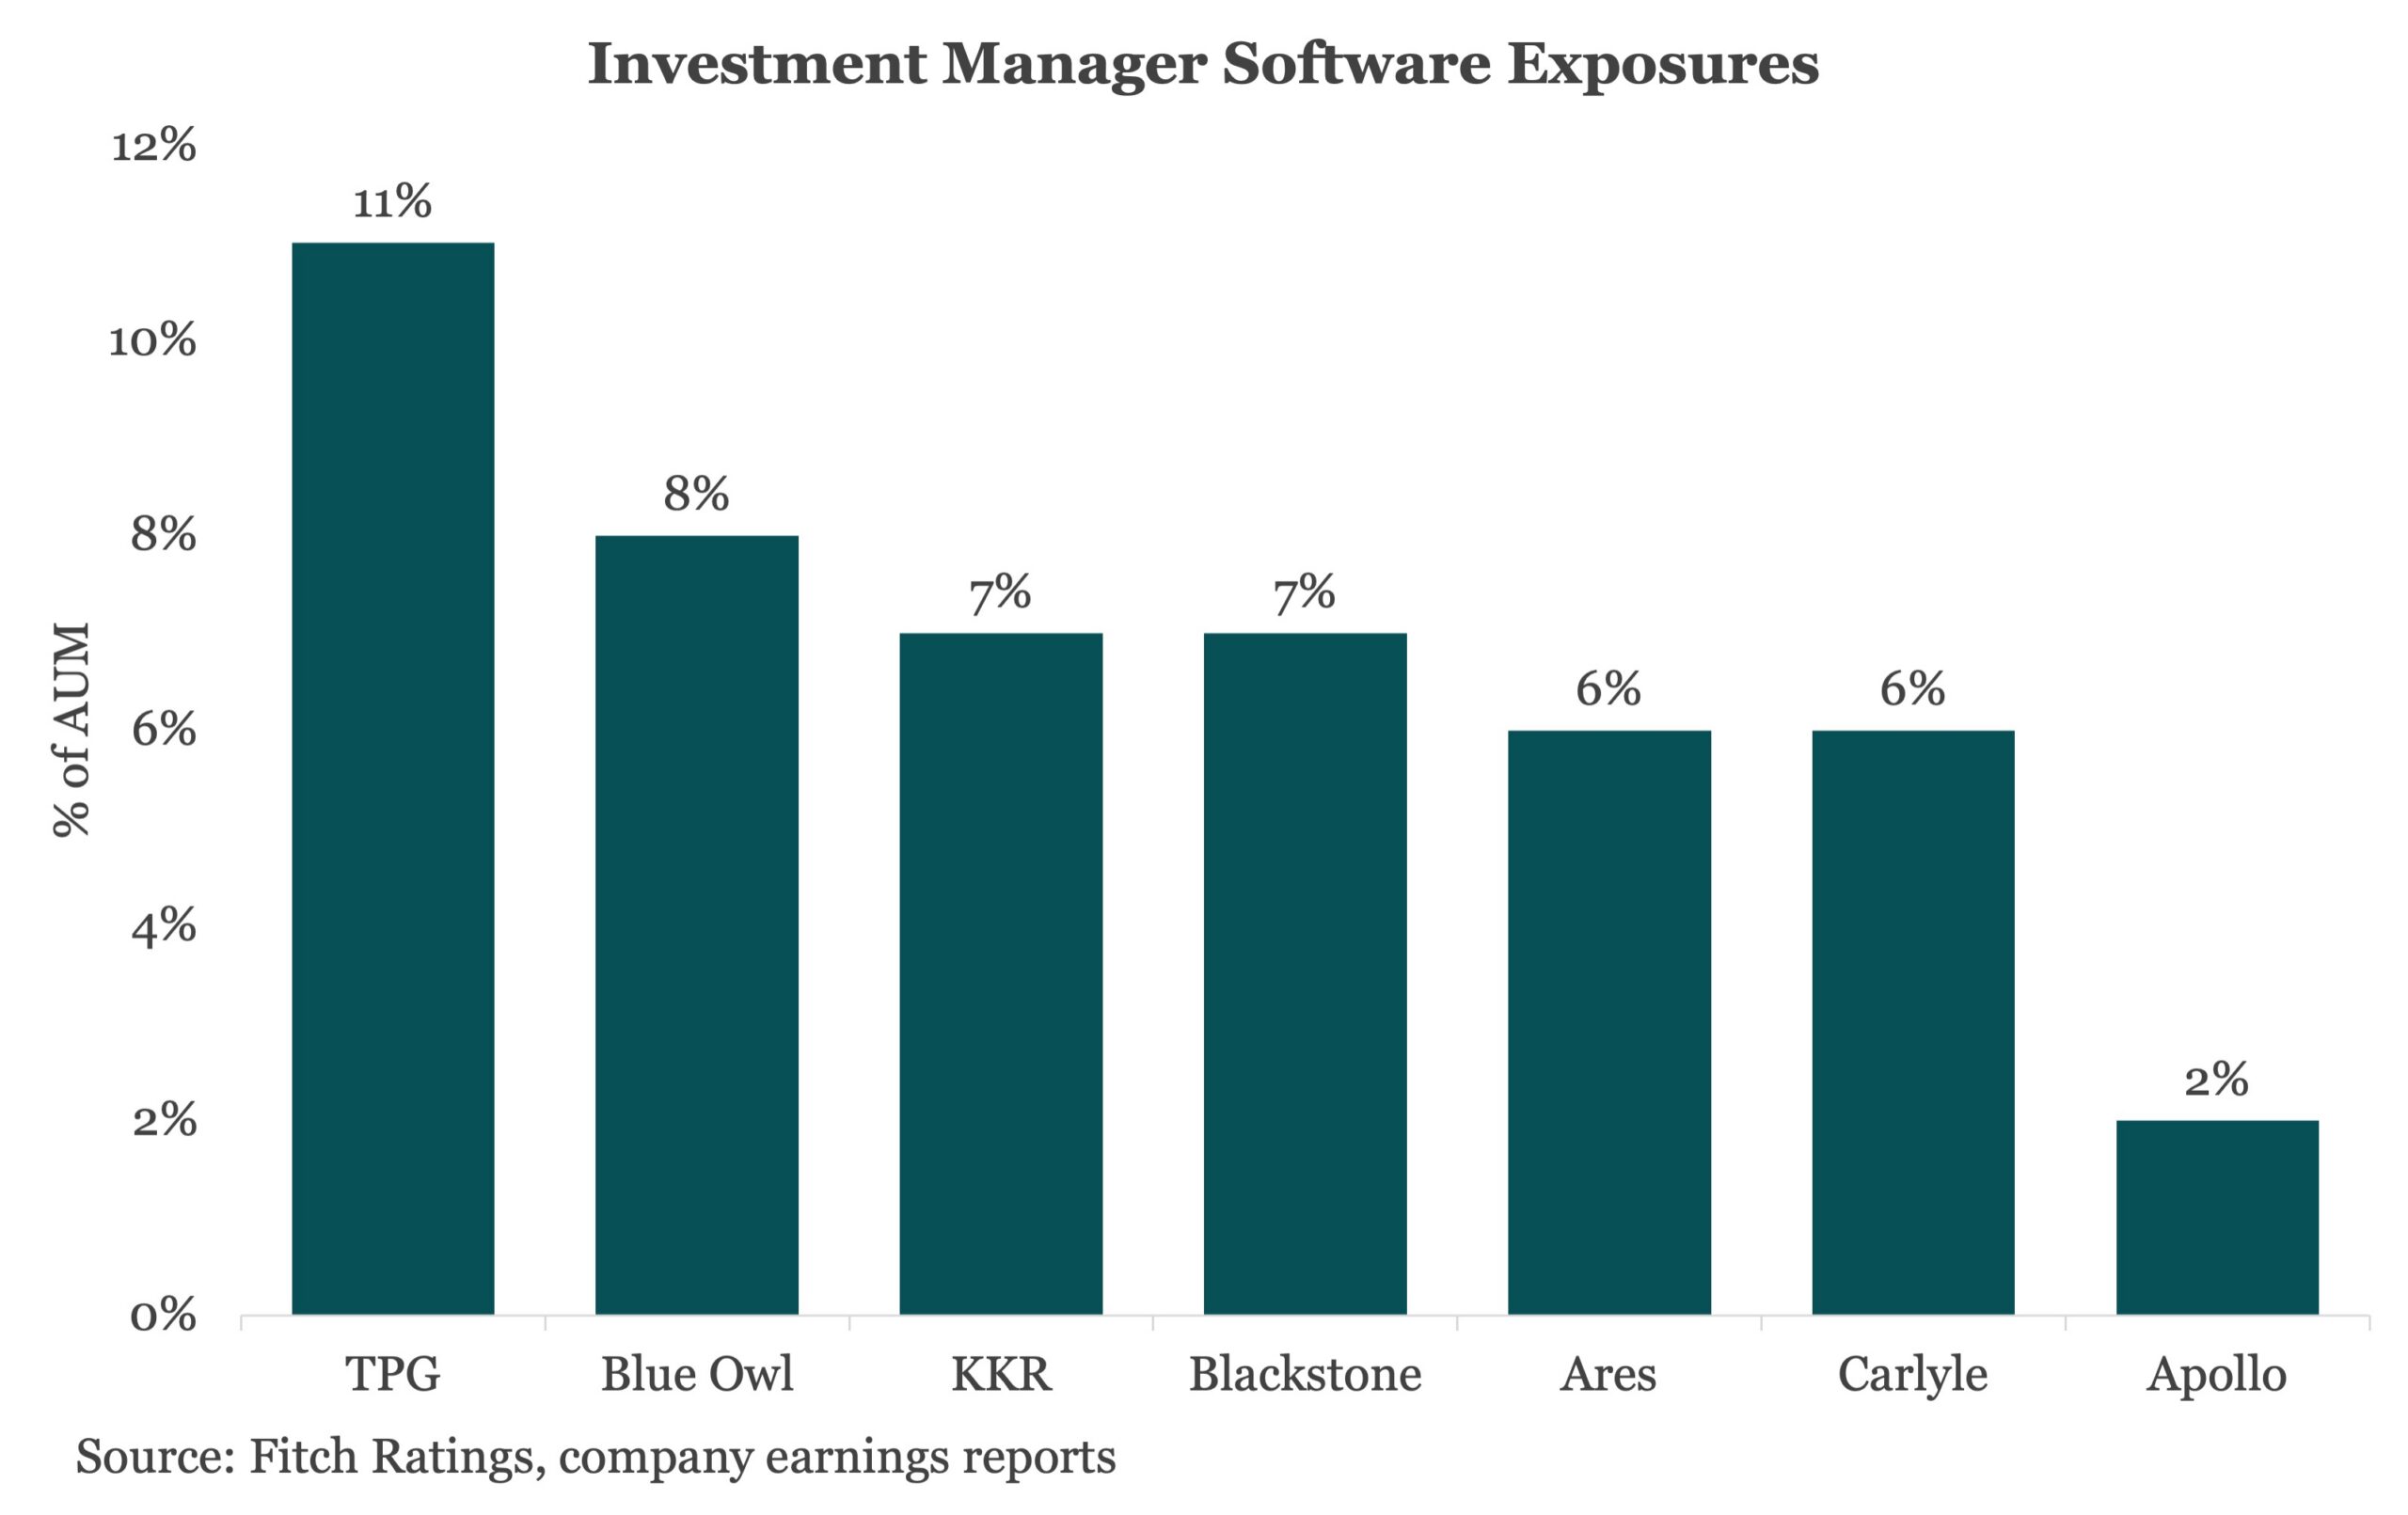
Sharp declines in major software company valuations amid rising investor concerns about AI-driven disruption have raised questions about lenders’ and asset managers’ sector exposure. While direct lenders, including business development companies (BDCs), typically have sizable software exposures, Fitch-rated alternative investment managers (alt IMs) are generally more diversified, with software representing roughly 2% to 11% of assets under management (AUM) as of Dec. 31, 2025.
Most alt IM software exposure sits in credit portfolios with substantial equity cushions. Average loan-to-value ratios (LTV) were under 40% at origination. Alt IMs also report strong cash yields on software loans and minimal exposure to annual recurring revenue (ARR)-based lending. Therefore, Fitch views refinancing risk as the key concern, as opposed to near-term defaults. Weaker valuations and negative sentiment could pressure takeouts, with remaining maturities generally in the three- to four-year range.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.