


Click here to learn more.
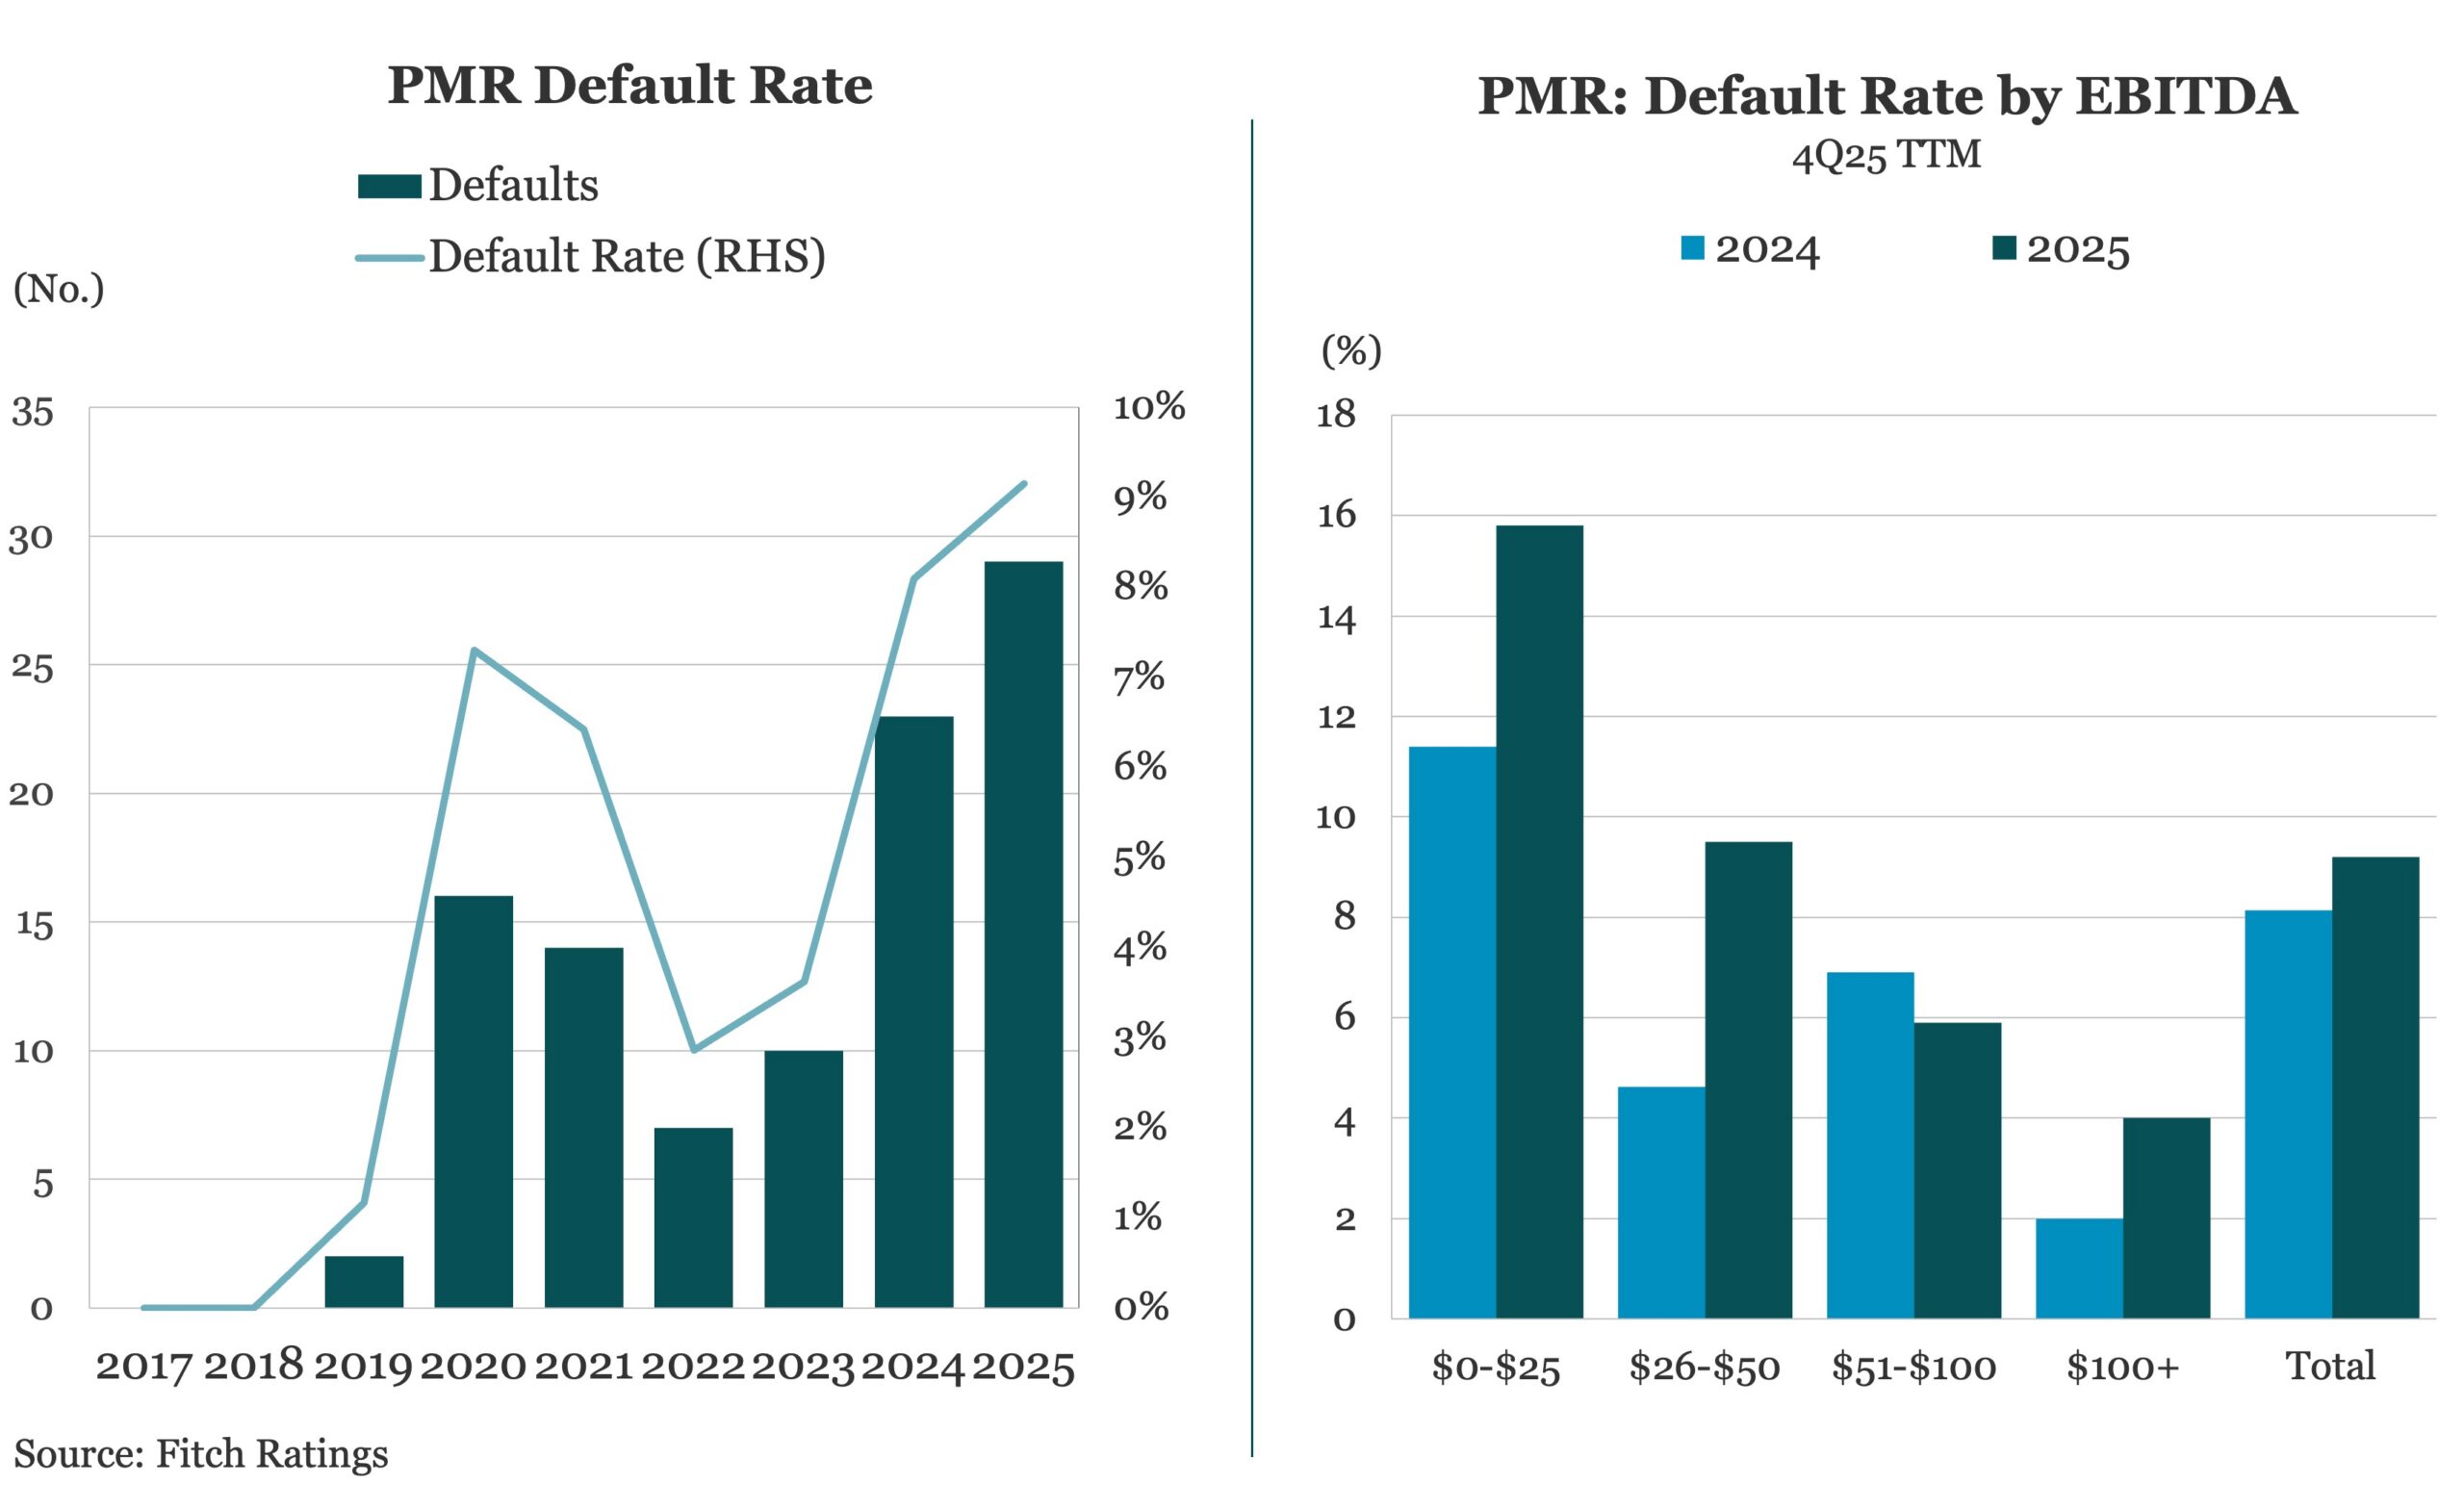
The default rate in Fitch Ratings’ privately monitored ratings (PMR) portfolio hit 9.2% in 2025, a new high, up significantly from 8.1% in 2024. Defaults were not concentrated in any particular sector, though Fitch recorded four defaults in the consumer products sector and three defaults among healthcare roll-ups. The PMR default rate is issuer-weighted and includes only unique defaulters.
Smaller issuers defaulted at a higher rate than larger issuers for the second year that Fitch has been tracking the data. Issuers with $25 million or less of EBITDA defaulted at a rate of 15.8% in 2025, while issuers with more than $100 million of EBITDA had a default rate of only 4%.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
