


Click here to learn more.
U.S. technology software sector issuers in Fitch Ratings’ model-based, point-in-time credit opinion (MCO) portfolio are more vulnerable to credit deterioration under a severe earnings stress scenario compared with the portfolio excluding the technology software sector.
As detailed in its recent report, Fitch assessed the sensitivity of its MCO portfolio by modeling a 20% EBITDA decline in the corporate credit opinion model (CCOM). More technology software issuers received a lower CCOM output after the stress than issuers in the rest of the portfolio at 59% and 44%, respectively. Large technology software issuers with EBITDA above $100 million showed the greatest negative migration under the stress.
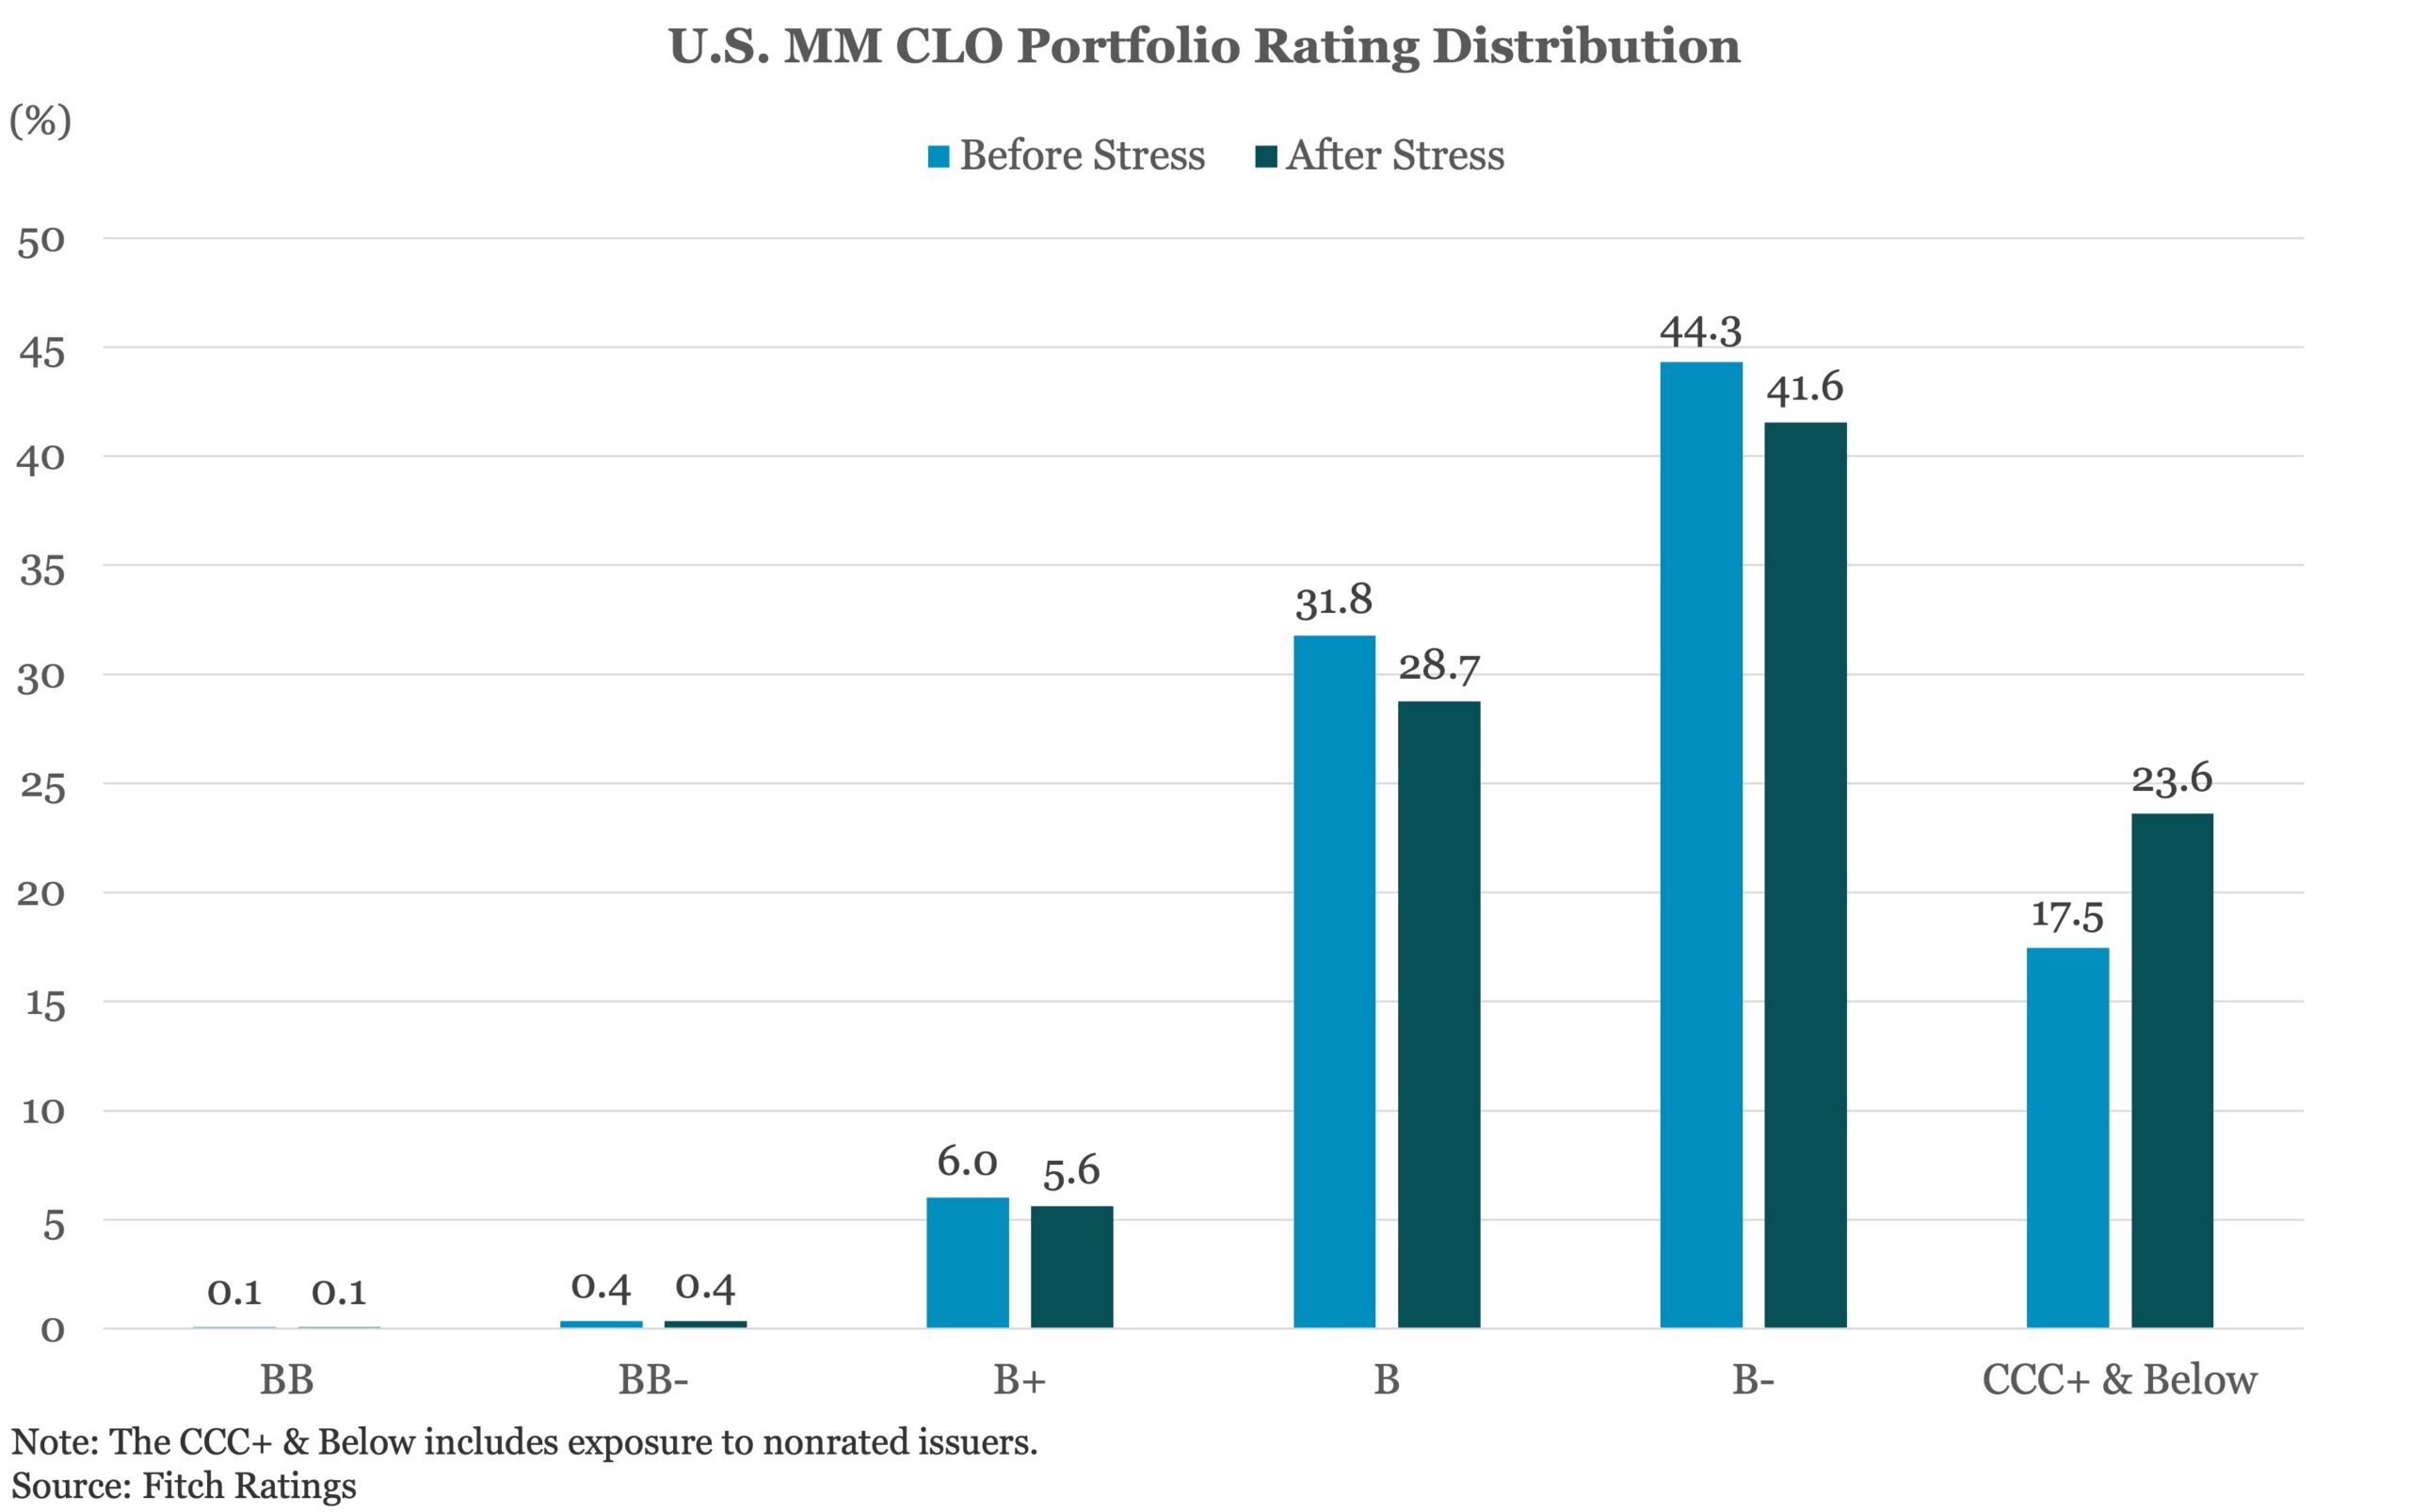
Fitch separately stressed its middle market (MM) U.S. CLO portfolio, incorporating the stressed CCOM outputs for technology software exposures and stresses that modeled lower ratings for the sector if a rating was on a negative outlook. The stressed CLO portfolio credit distribution shifted slightly toward the deeper sub-investment-grade buckets from the B category. Most MM U.S. CLO notes maintained ample downgrade cushions. Cushion compression was generally small and affected only a handful of transactions, with lower-rated notes seeing the greatest impact.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.