


Click here to learn more.
Private Credit Default Rates
- The PMR default rate based solely on bankruptcies, liquidations, and out-of-court restructurings was 1.9%.
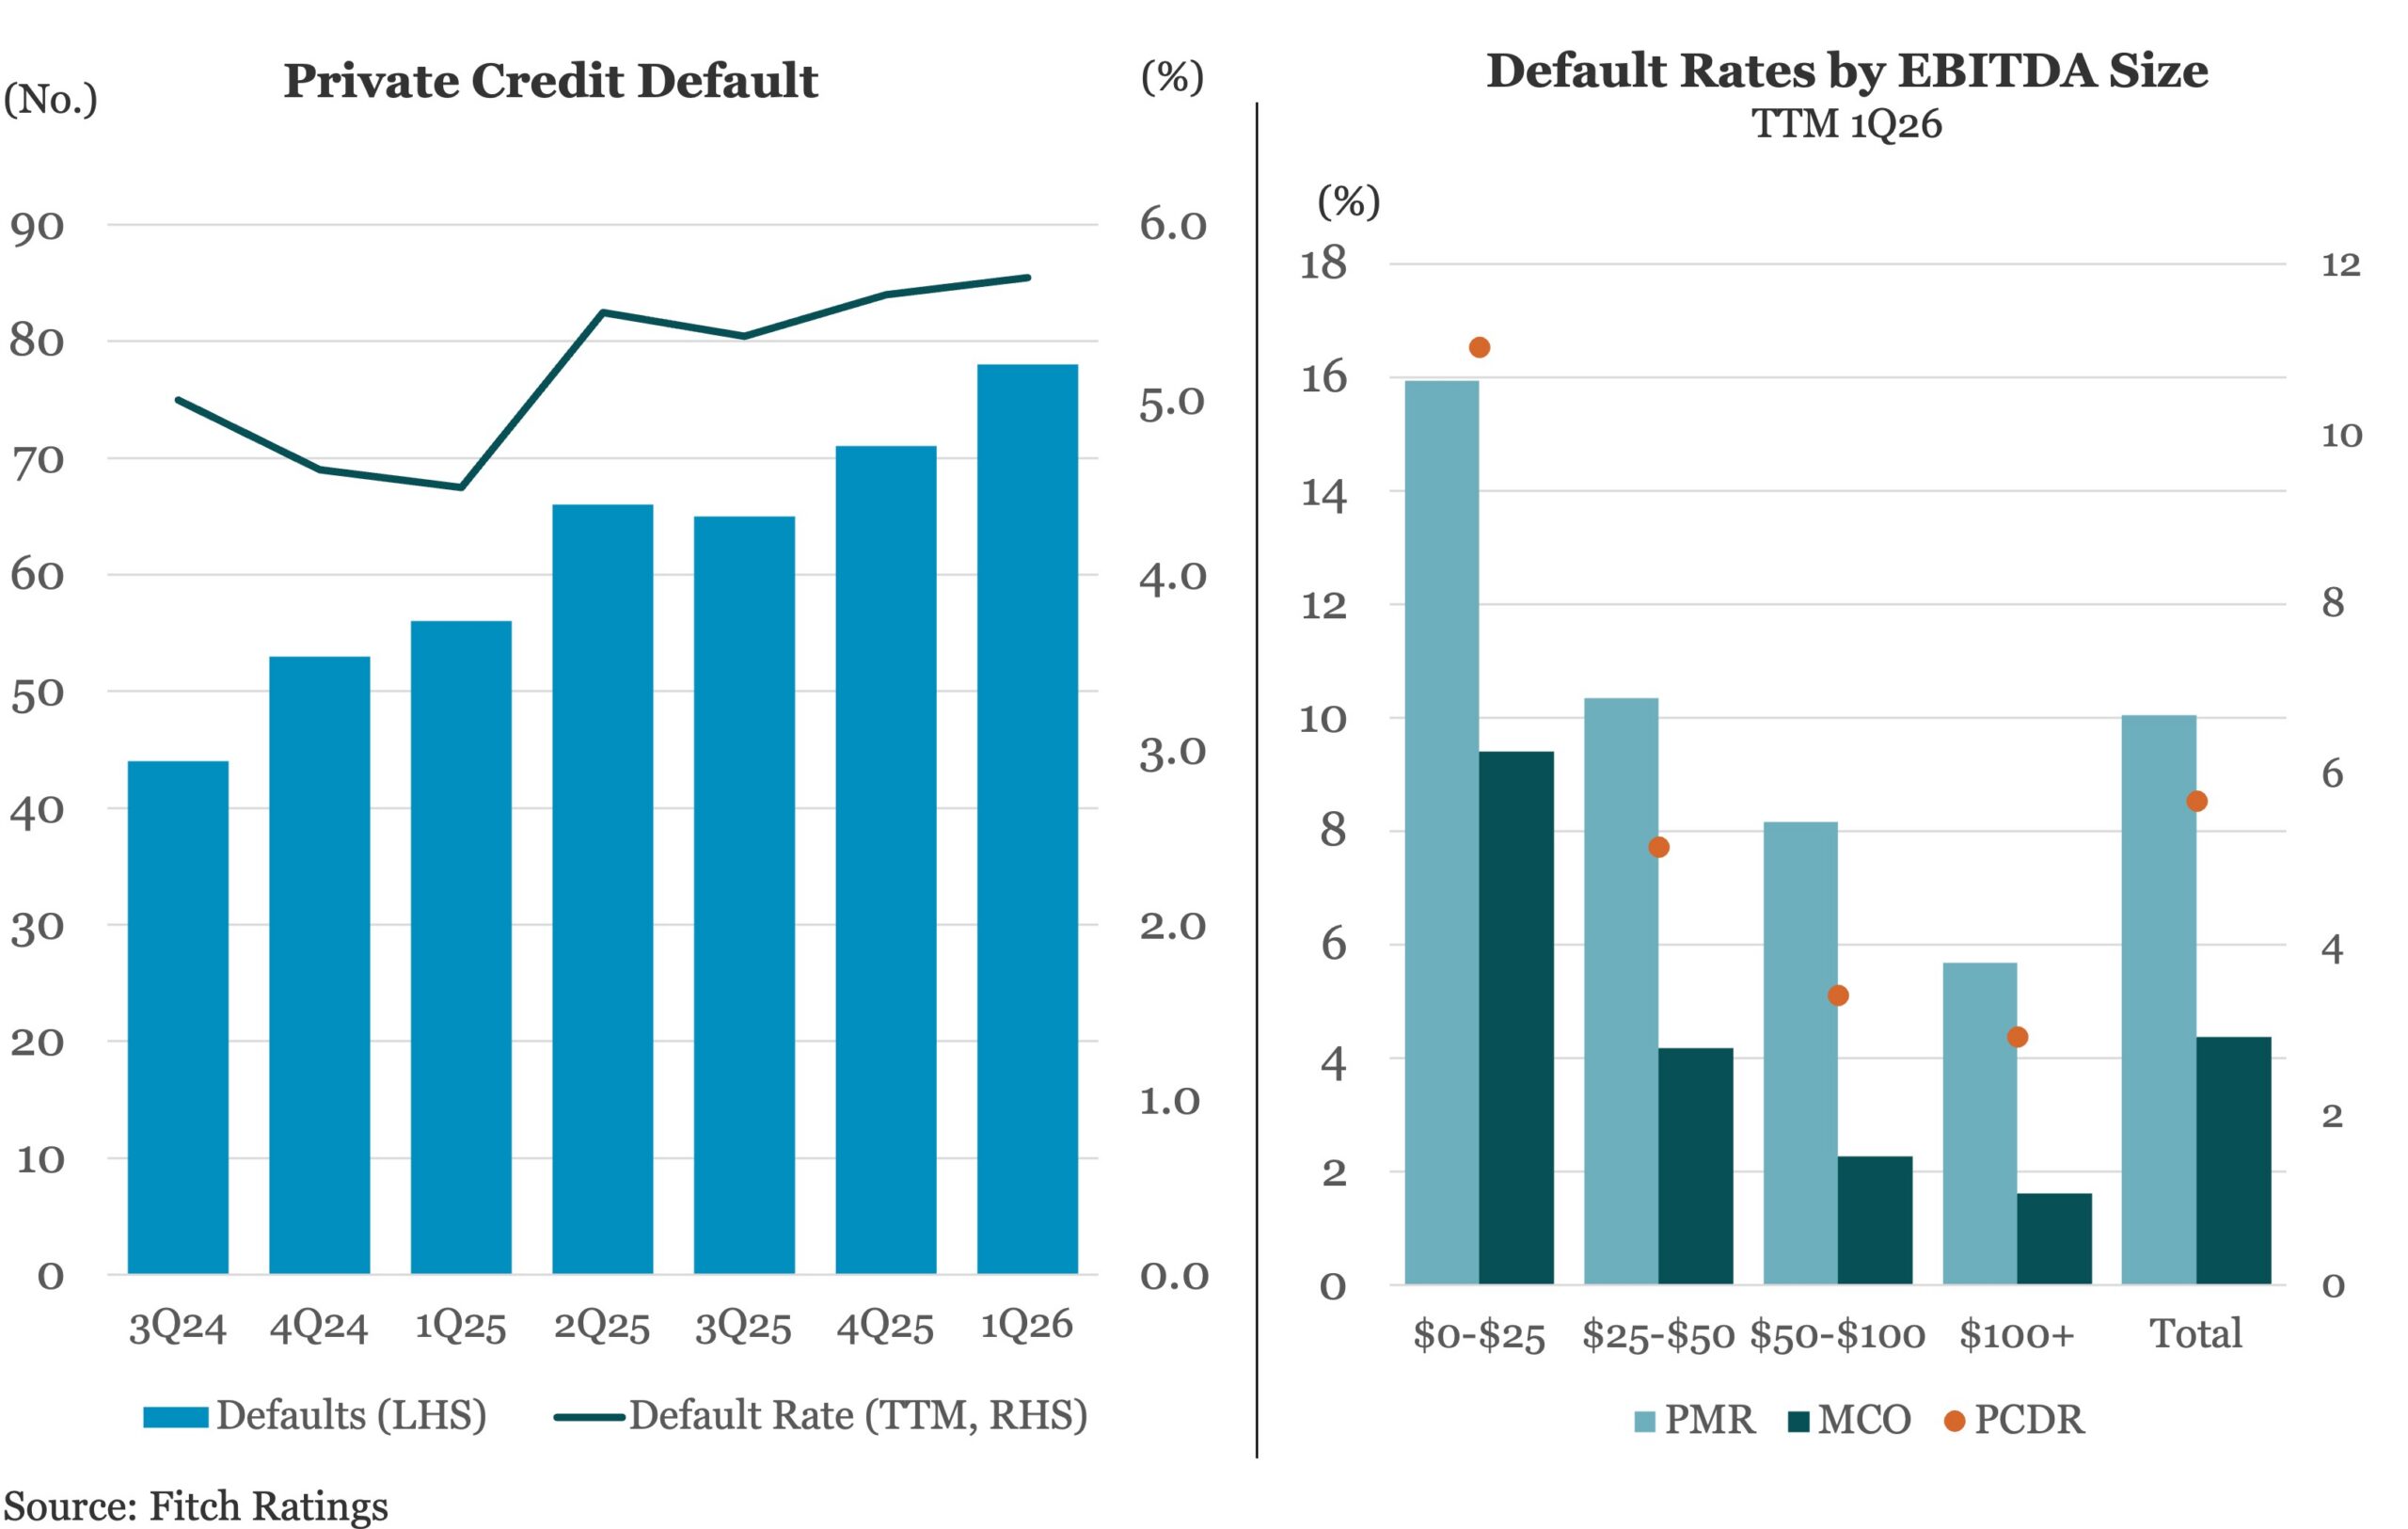
- The U.S. PCDR increased to 5.7% in the TTM ending 1Q26, up from 5.6% in 4Q25. The rate remains just below the recent high of 5.8% set in January 2026.
- The PCDR comprises two components: the Model-based Credit Opinion (MCO) default rate and the PMR default rate. In 1Q26, the MCO default rate improved slightly to 4.4% from 4.5% in 4Q25, while the PMR default rate rose to a record 10.0% in 1Q26, up from 9.2% in 4Q25. Fitch recorded 29 private credit default events from 24 new unique defaulters in 1Q26, pushing the TTM total to 78 unique defaulters, up from 71 in 4Q25.
- Including repeat defaults by the same issuer, Fitch recorded 94 default events within the PCDR universe over the TTM ending 1Q26. Interest payment deferrals and introduction of PIK drove 56% of the default events; stressed maturity extensions accounted for 30%; uncured payment defaults made up 5%; and bankruptcies, liquidations, and out-of-court restructurings represented 9%.
Contact Brad Hamner



Latest news

Open Tab
October 14, 2026
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.


Information technology topped nonaccruals on a cost basis
October 14, 2026
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.