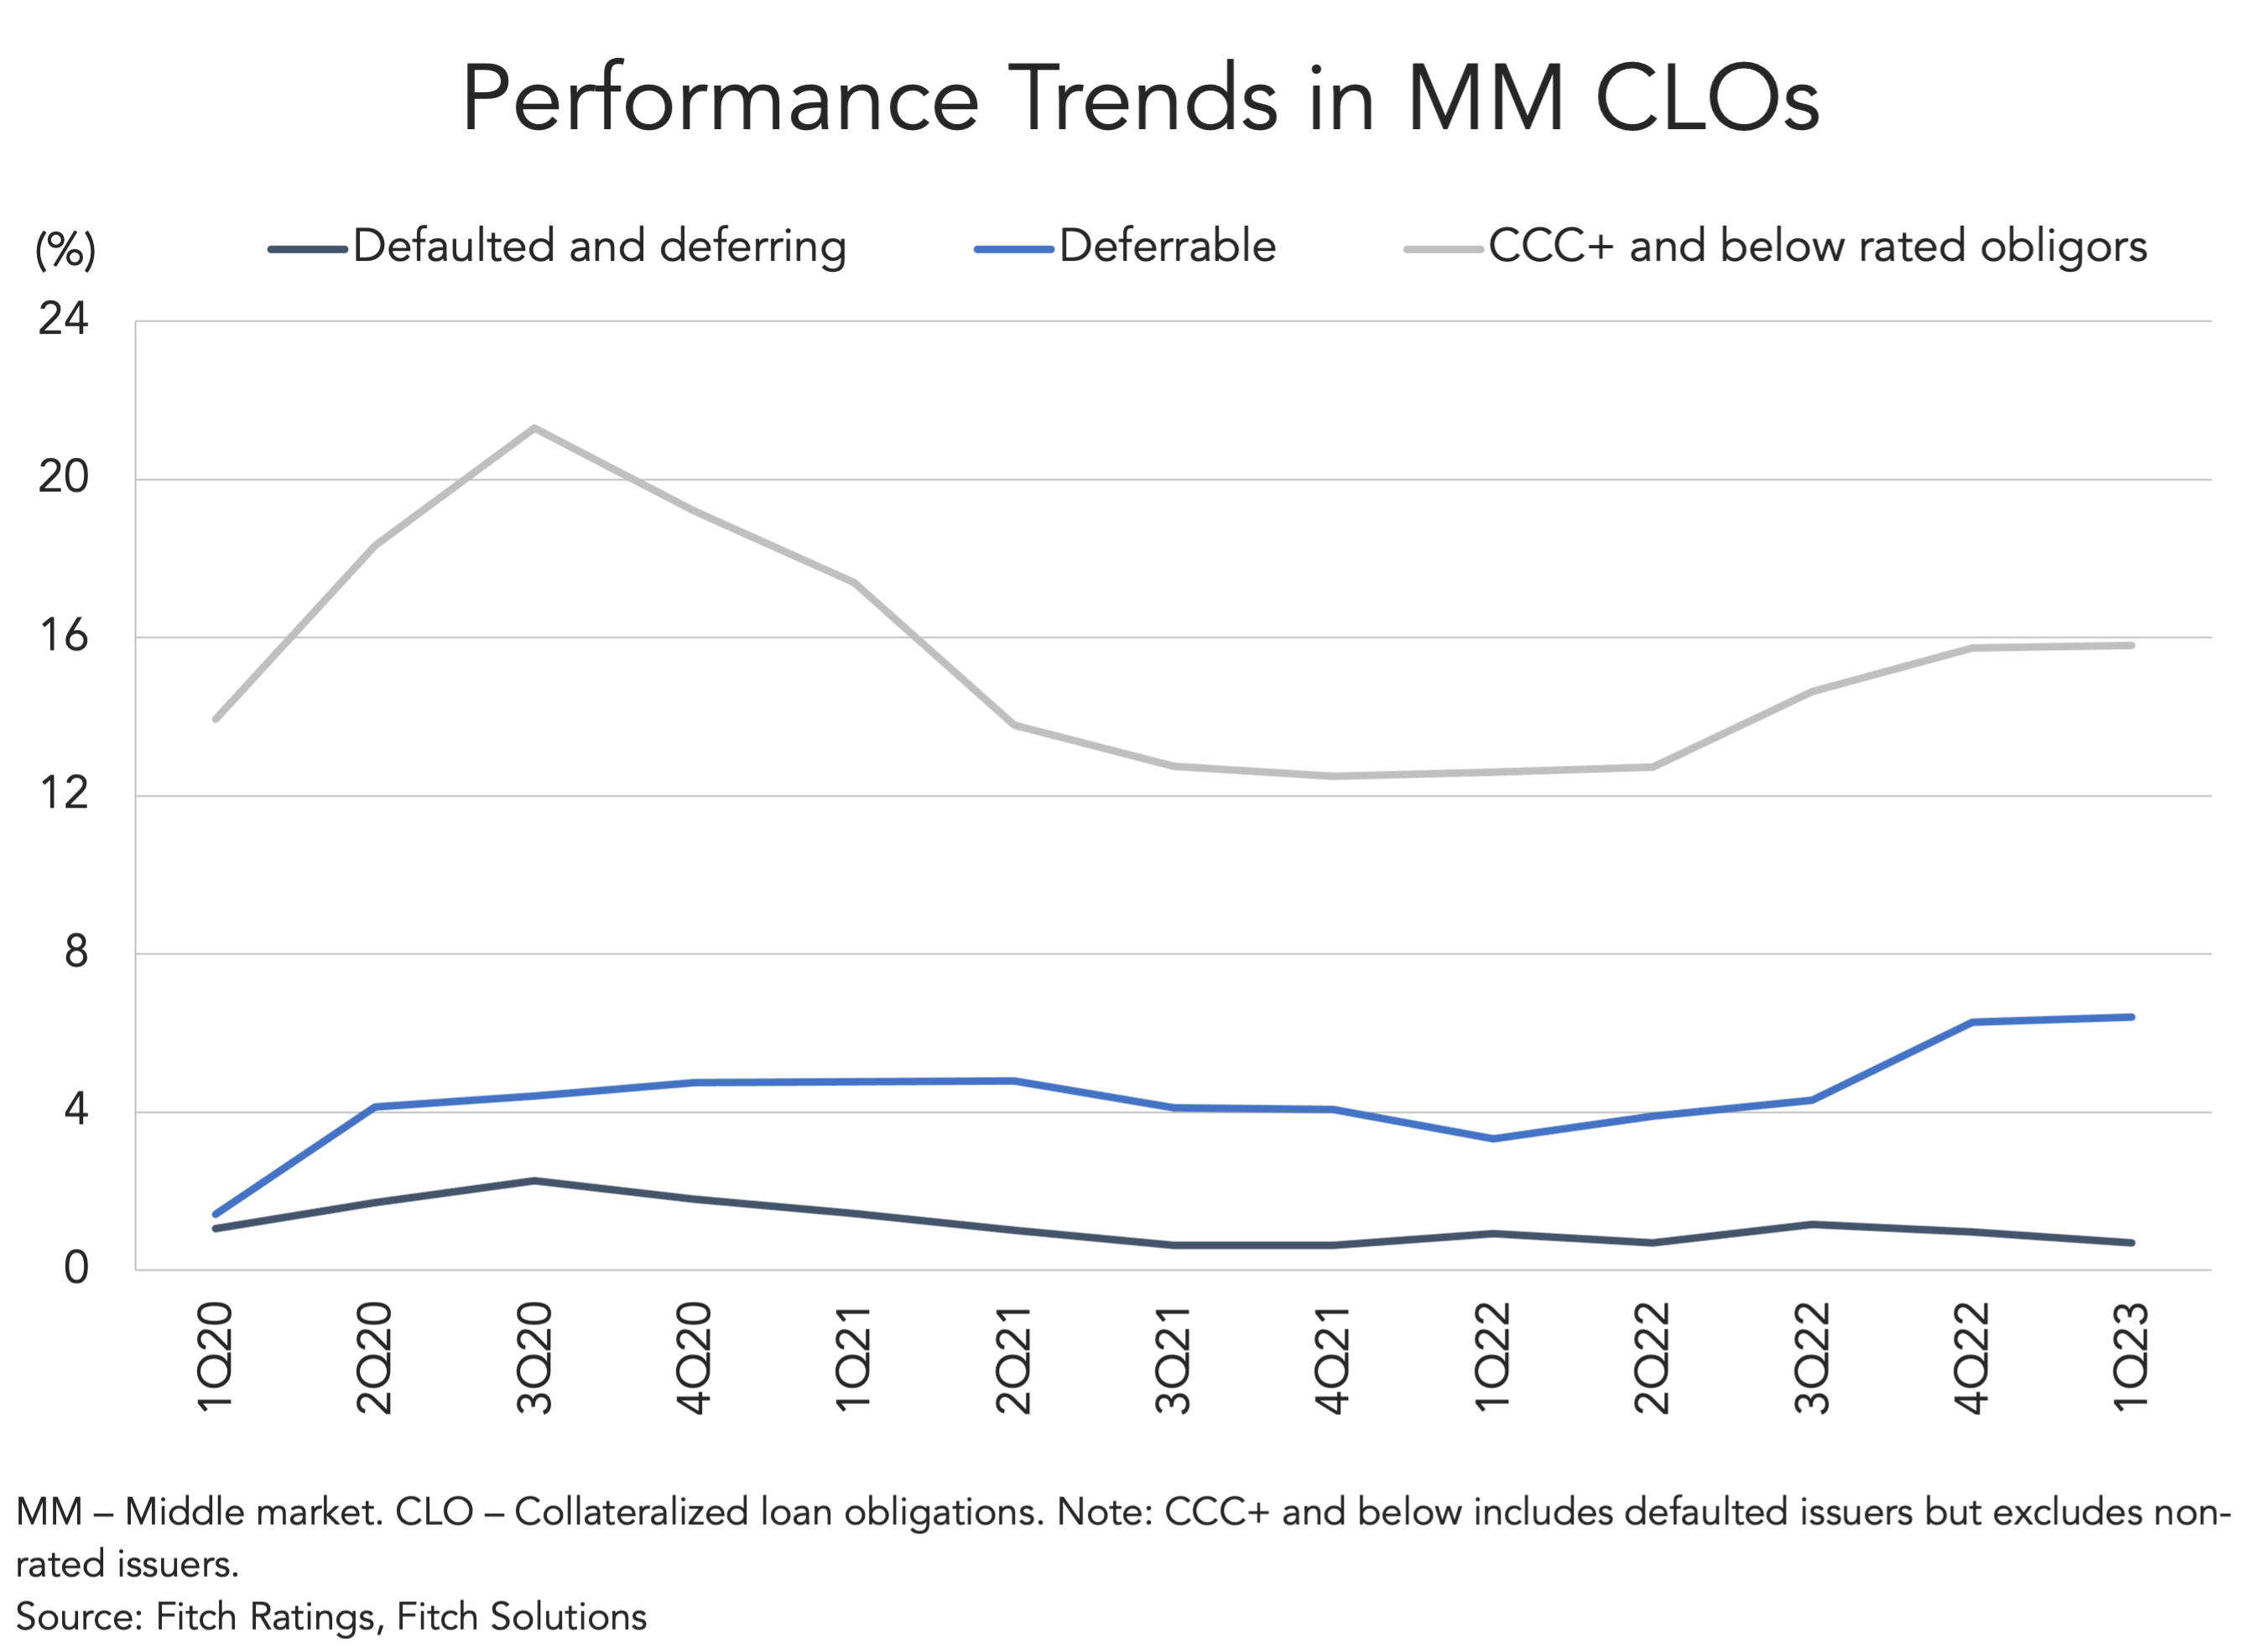
Defaulted and deferring exposure across MM CLOs remained low at 0.7% in 1Q23, while deferrables stood at 6.4%. Exposure to assets rated ‘CCC+’ or below by Fitch Issuer Default Rate Equivalency Rating, as described in Appendix 5 of Fitch’s CLOs and Corporate CDO Rating Criteria, registered at 15.8%.
CTA button: Download Report
(Past performance is no guarantee of future results.)
Contact Brad Hamner


Latest news
US leveraged loan issuance stalls in October amid secondary market rout
October 28, 2026
US leveraged loan issuance took a significant hit in October amid deteriorating secondary market conditions. Approximately $41.3b of loans have…