


Click here to learn more.
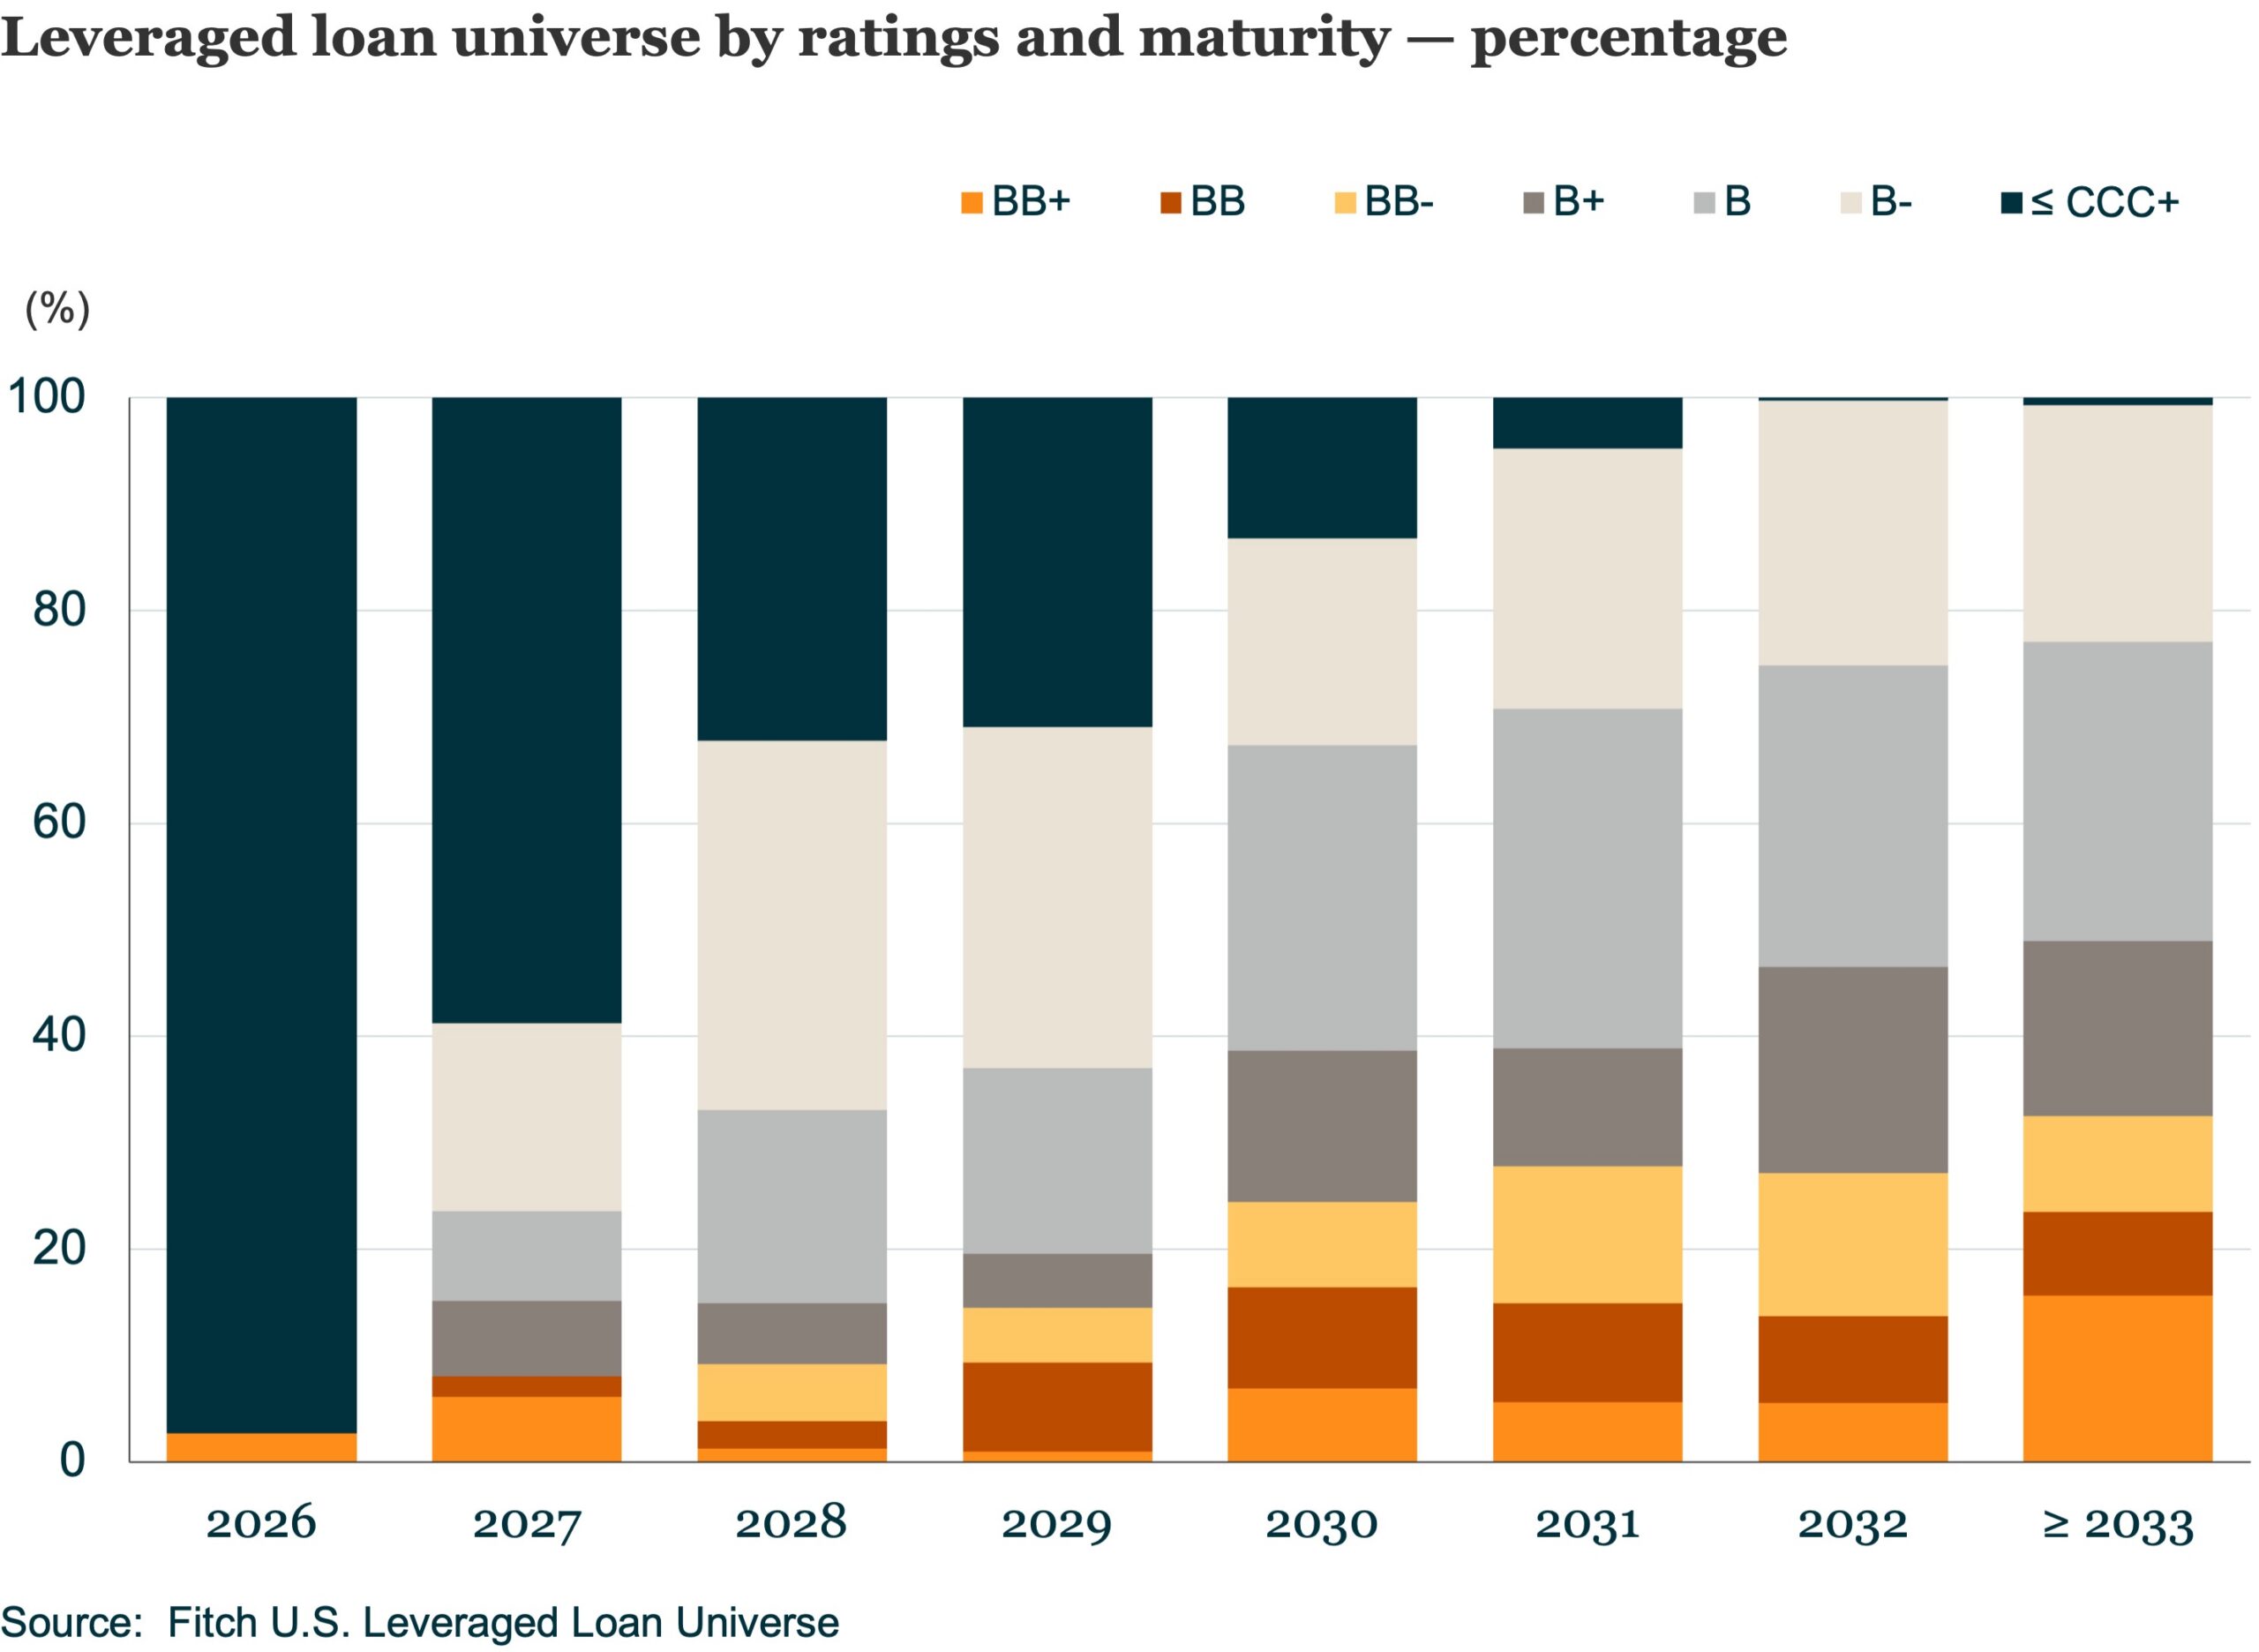
North American leveraged finance markets remained active in 2Q26, but performance gaps across credit tiers widened, according to a new Fitch Ratings report. Leveraged loan issuance held steady at about $220 billion, more than double a year earlier. Refinancing, repricing, and amend-and-extend activity rose to 75% of volume as issuers addressed the 2028 maturity wall. By contrast, M&A/LBO issuance slowed, dividend recap activity declined, and LBO leverage moderated, signaling a more cautious approach to risk-taking. New issue loan spreads tightened, especially for ‘B’ credits.
Secondary markets improved for loans and bonds, and investor demand recovered. Loan and HY fund flows turned positive after Q1 outflows, although loan prices remained weak and distressed technology/software names dominated the lowest-priced cohort. CLO formation slowed sharply to its lowest quarterly total since 3Q23, partially offsetting stronger demand in the broader loan market.


Latest news
US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
