


Click here to learn more.
Fitch’s Privately Monitored Ratings Portfolio, Rating Activity
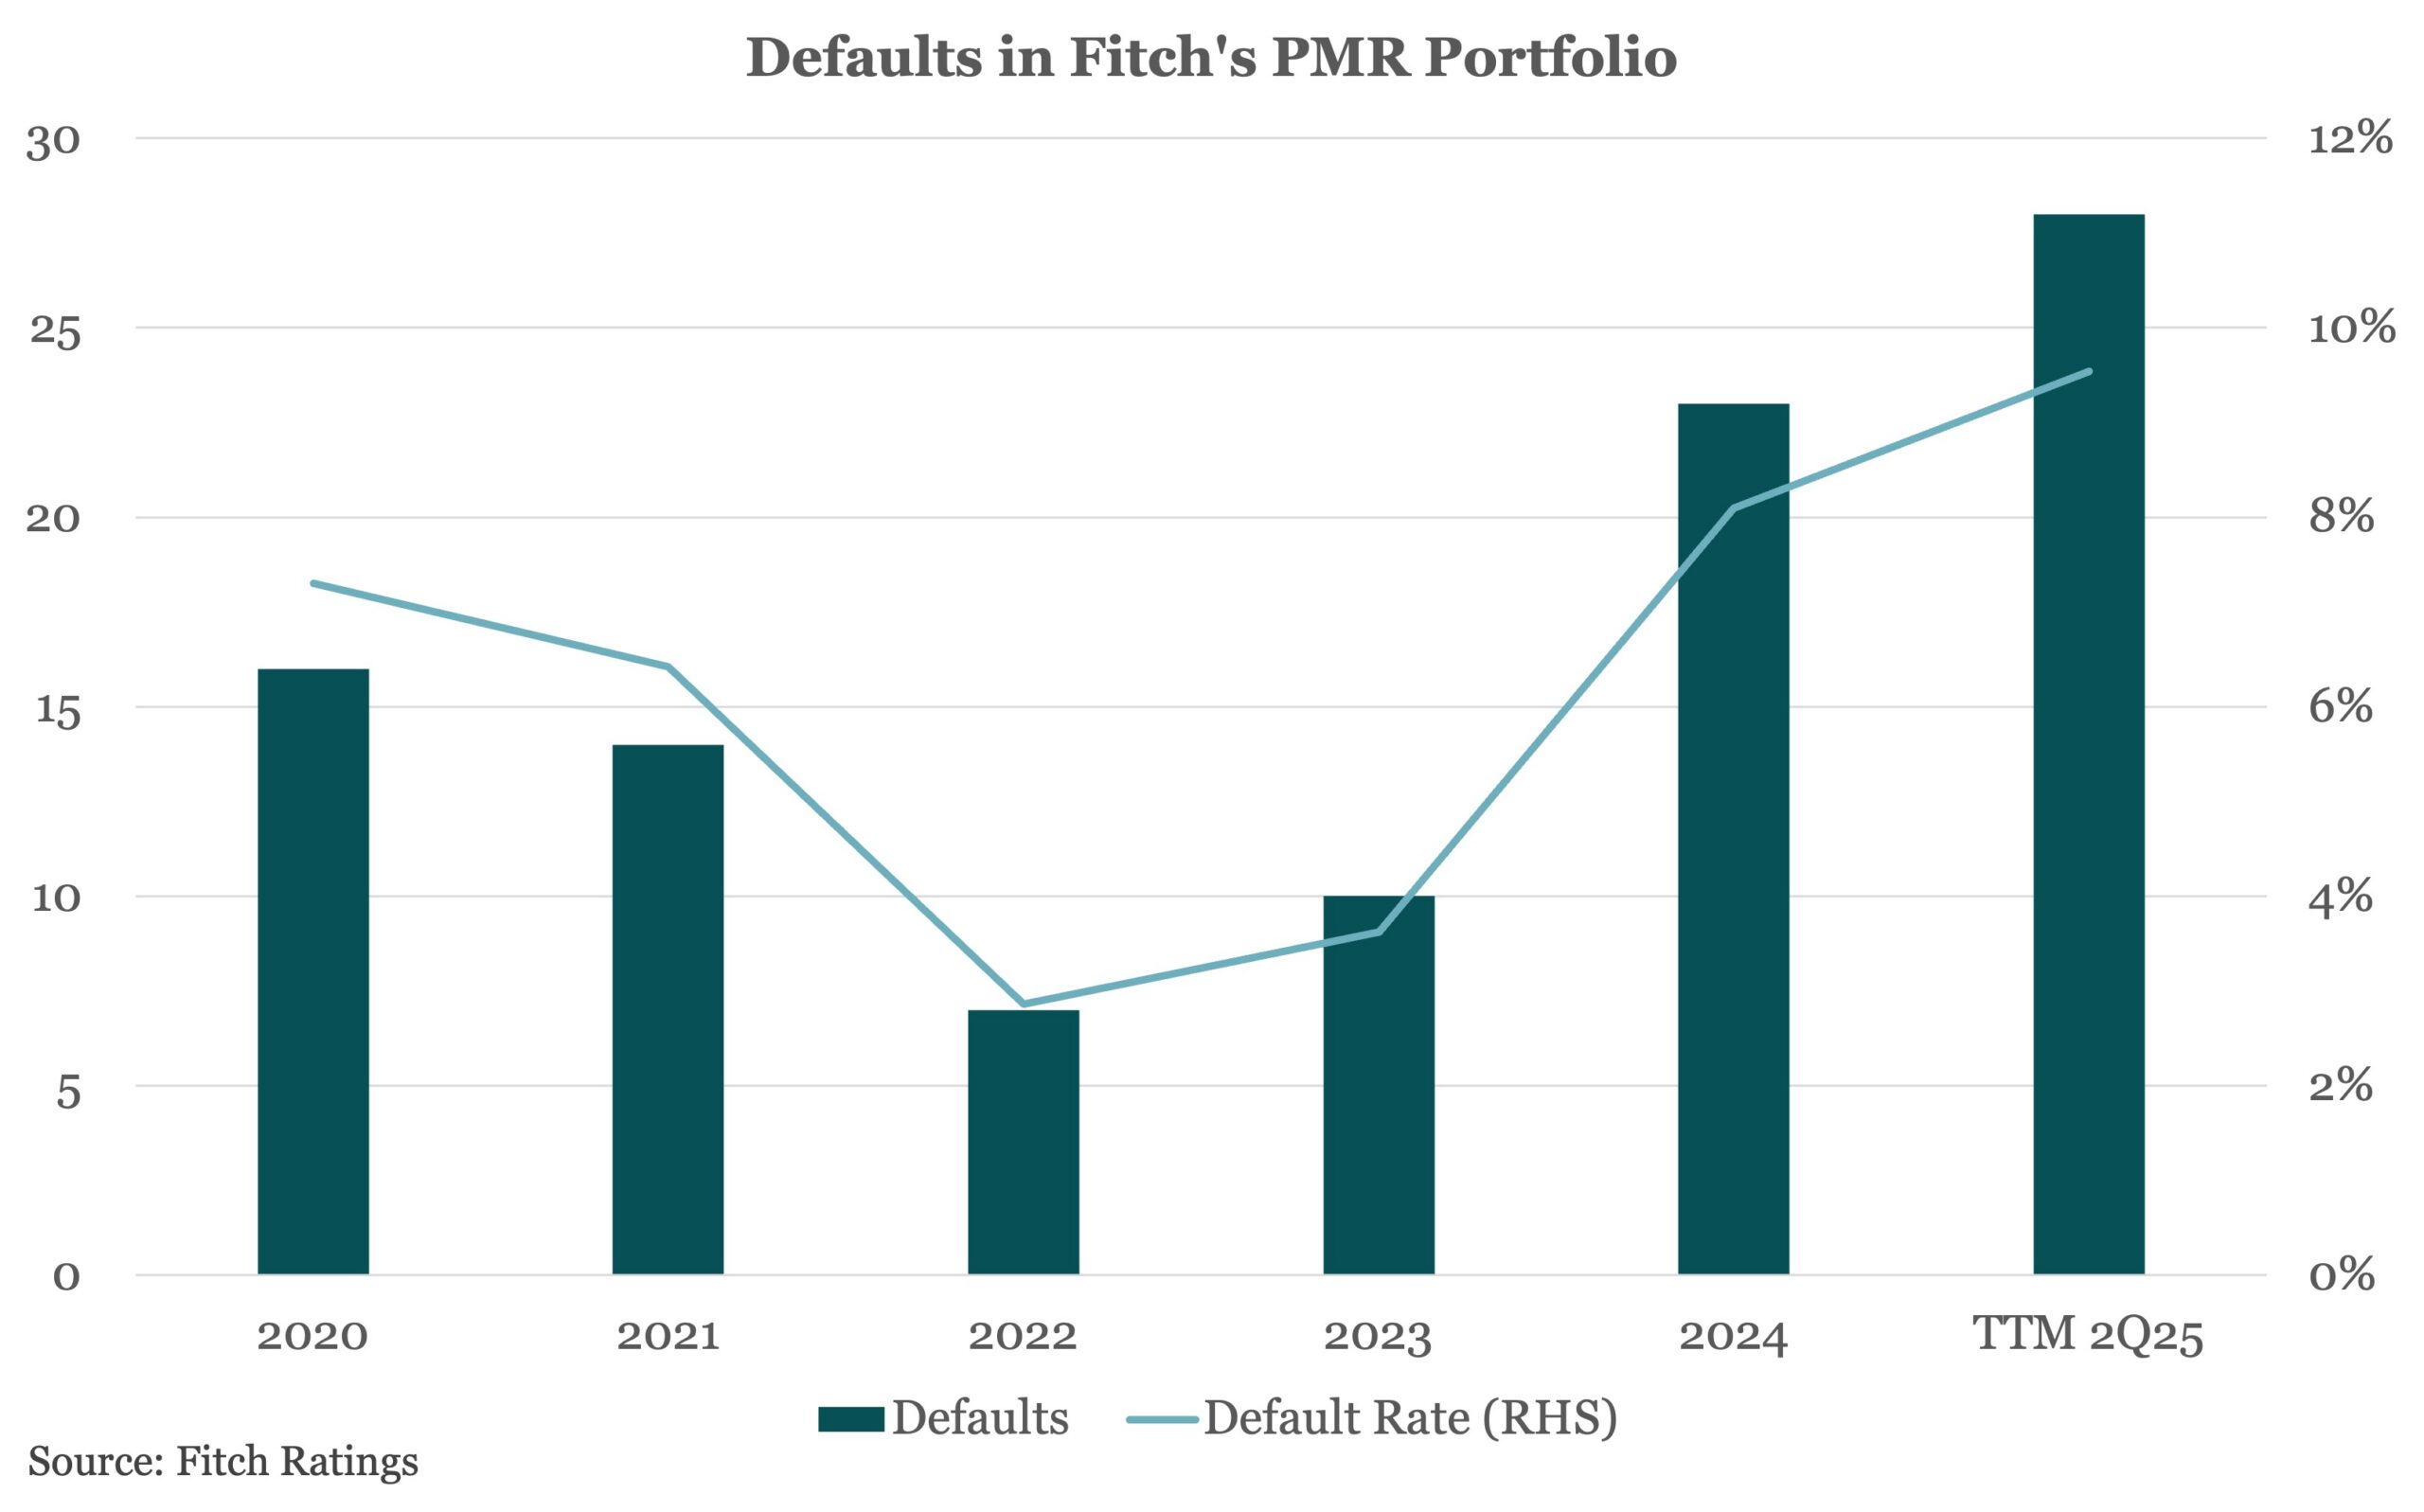
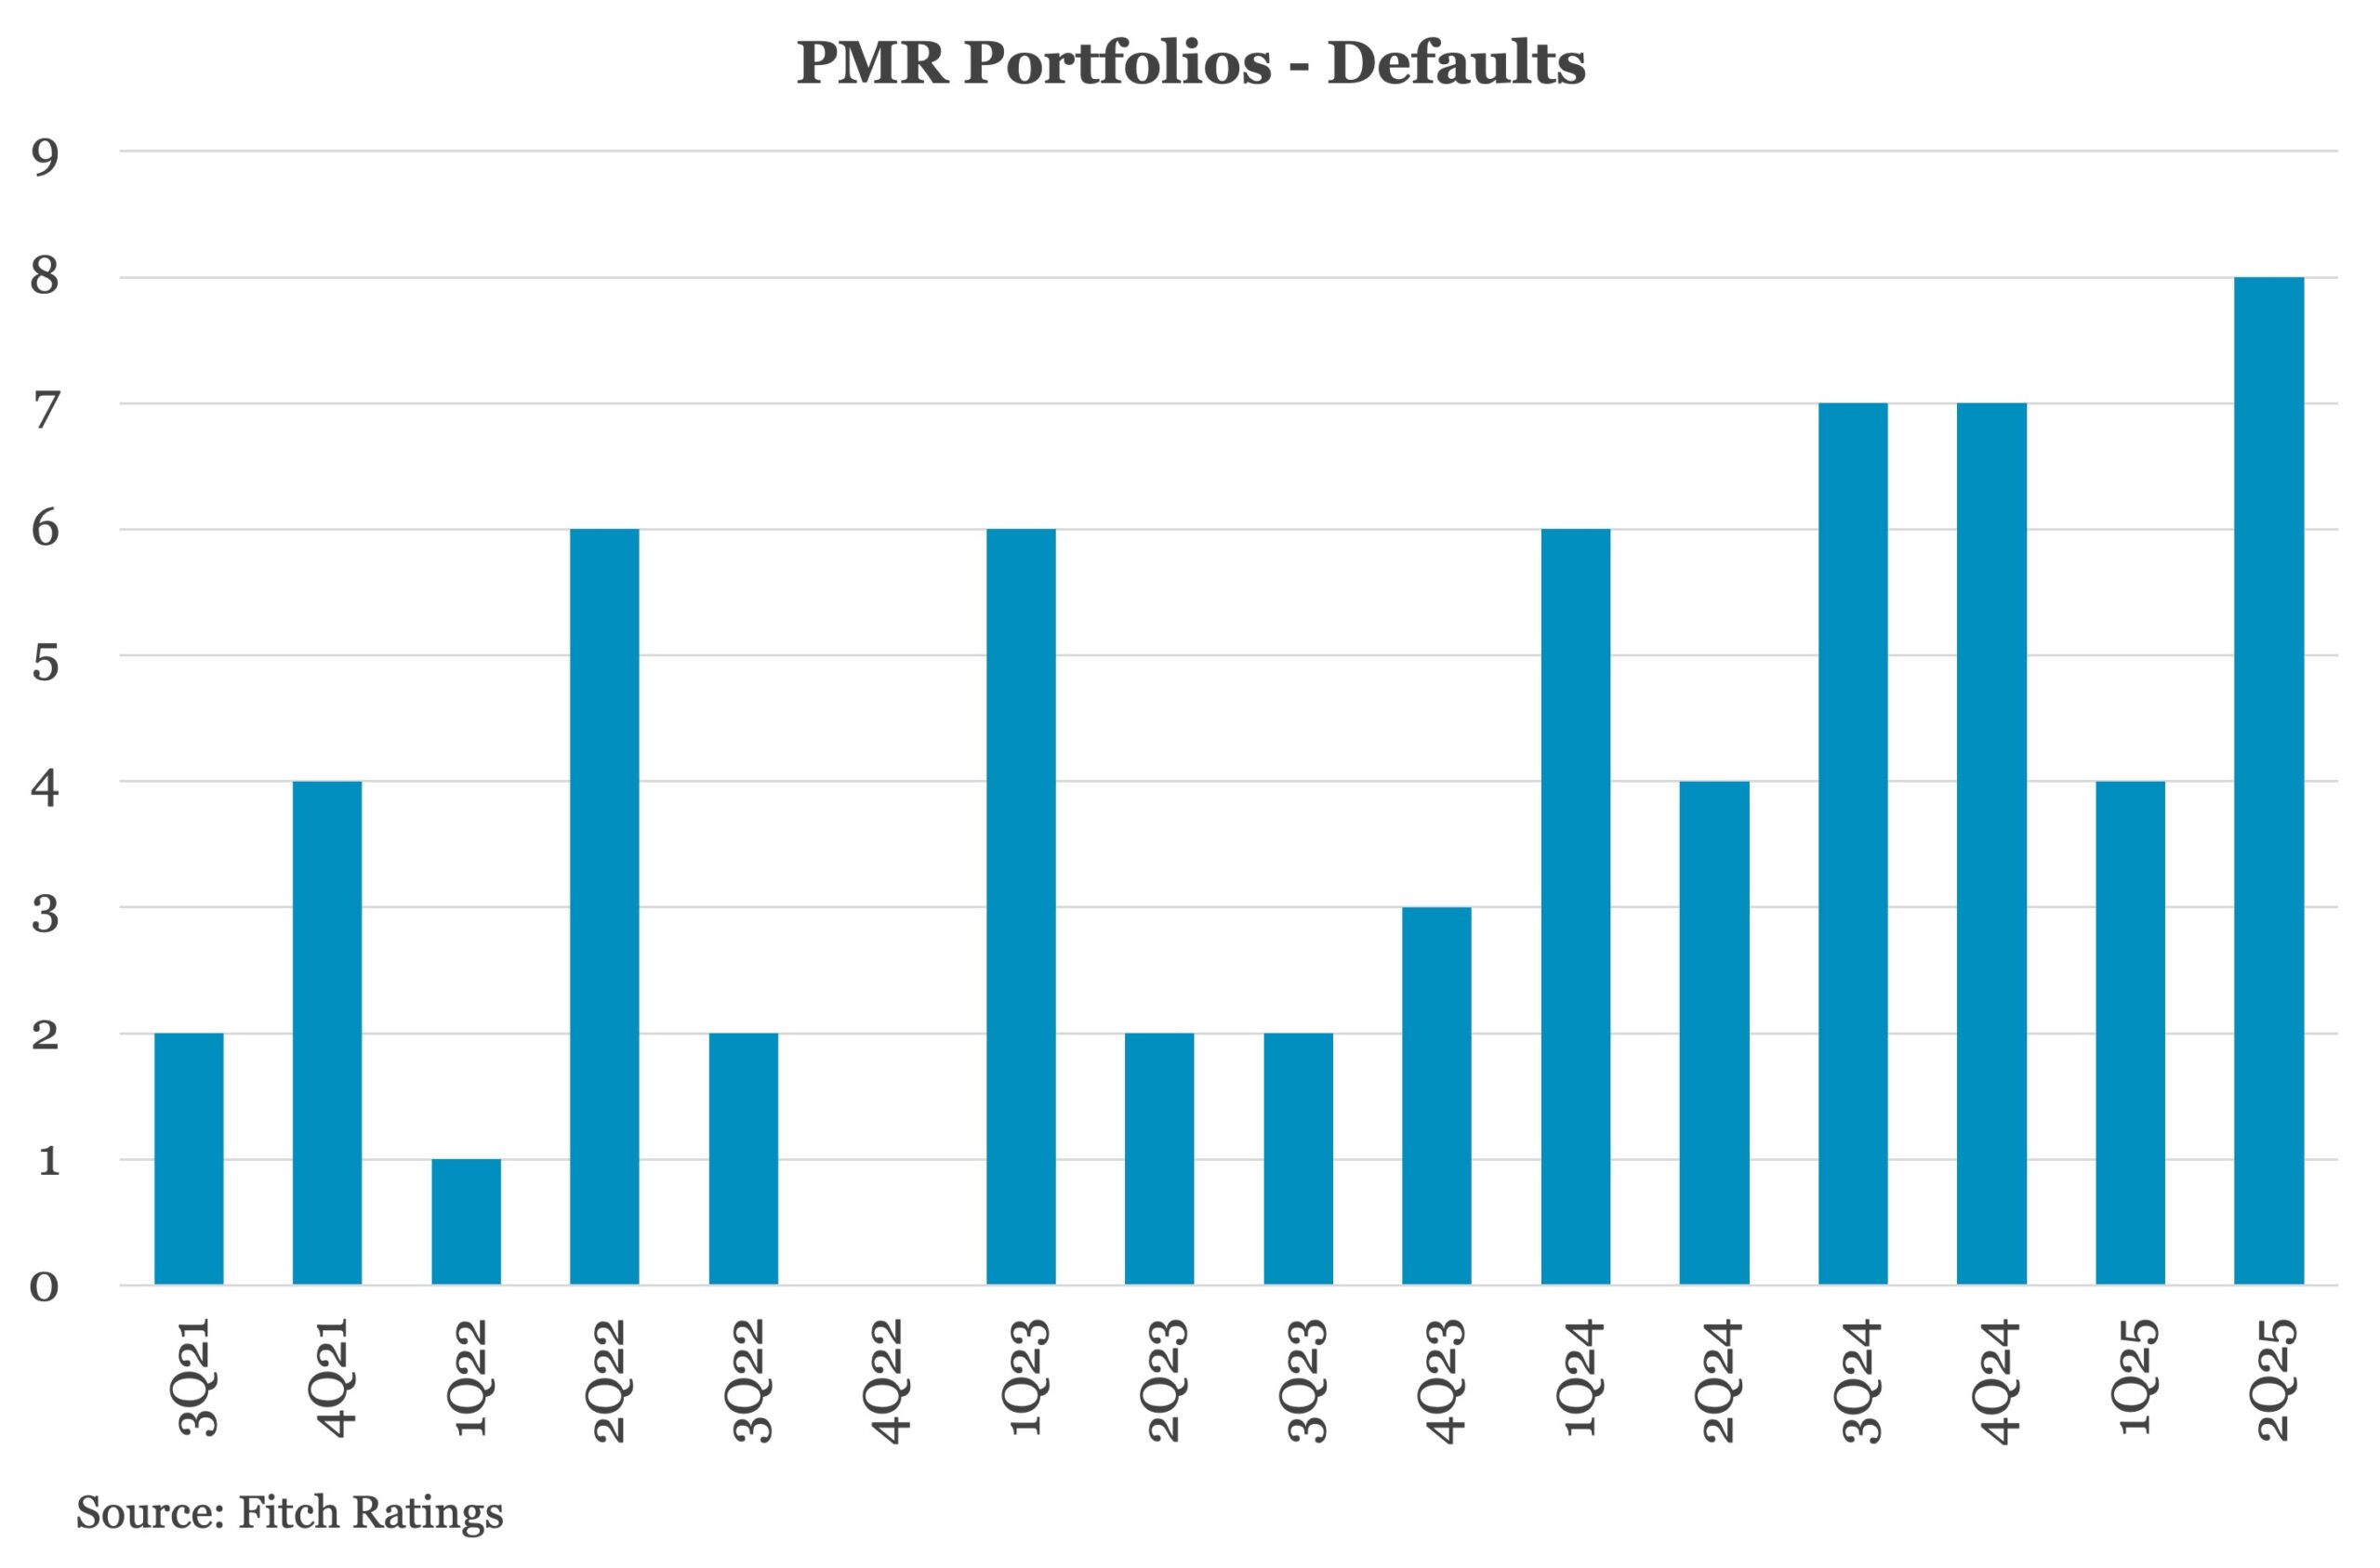
The issuer-weighted TTM default rate for PMRs rose to 9.5% in 2Q25 from 7.8% in 1Q25. Fitch recorded 28 unique defaults for the TTM period, up from 23 in 1Q25. This is the highest default rate since tracking began in 2017. Smaller, private issuers are more vulnerable than larger peers to economic swings, GDP slowdowns, and persistent elevated rates. Their floating-rate structures increase this risk.
Including repeat defaults by the same issuer, Fitch recorded 36 defaults in the TTM period ending 2Q25. Four defaults involved Chapter 11 bankruptcy or liquidation. Half of the cases involved interest deferrals or conversions of cash interest to payment-in-kind. Eight defaults were maturity extensions under stress.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.