


Click here to learn more.
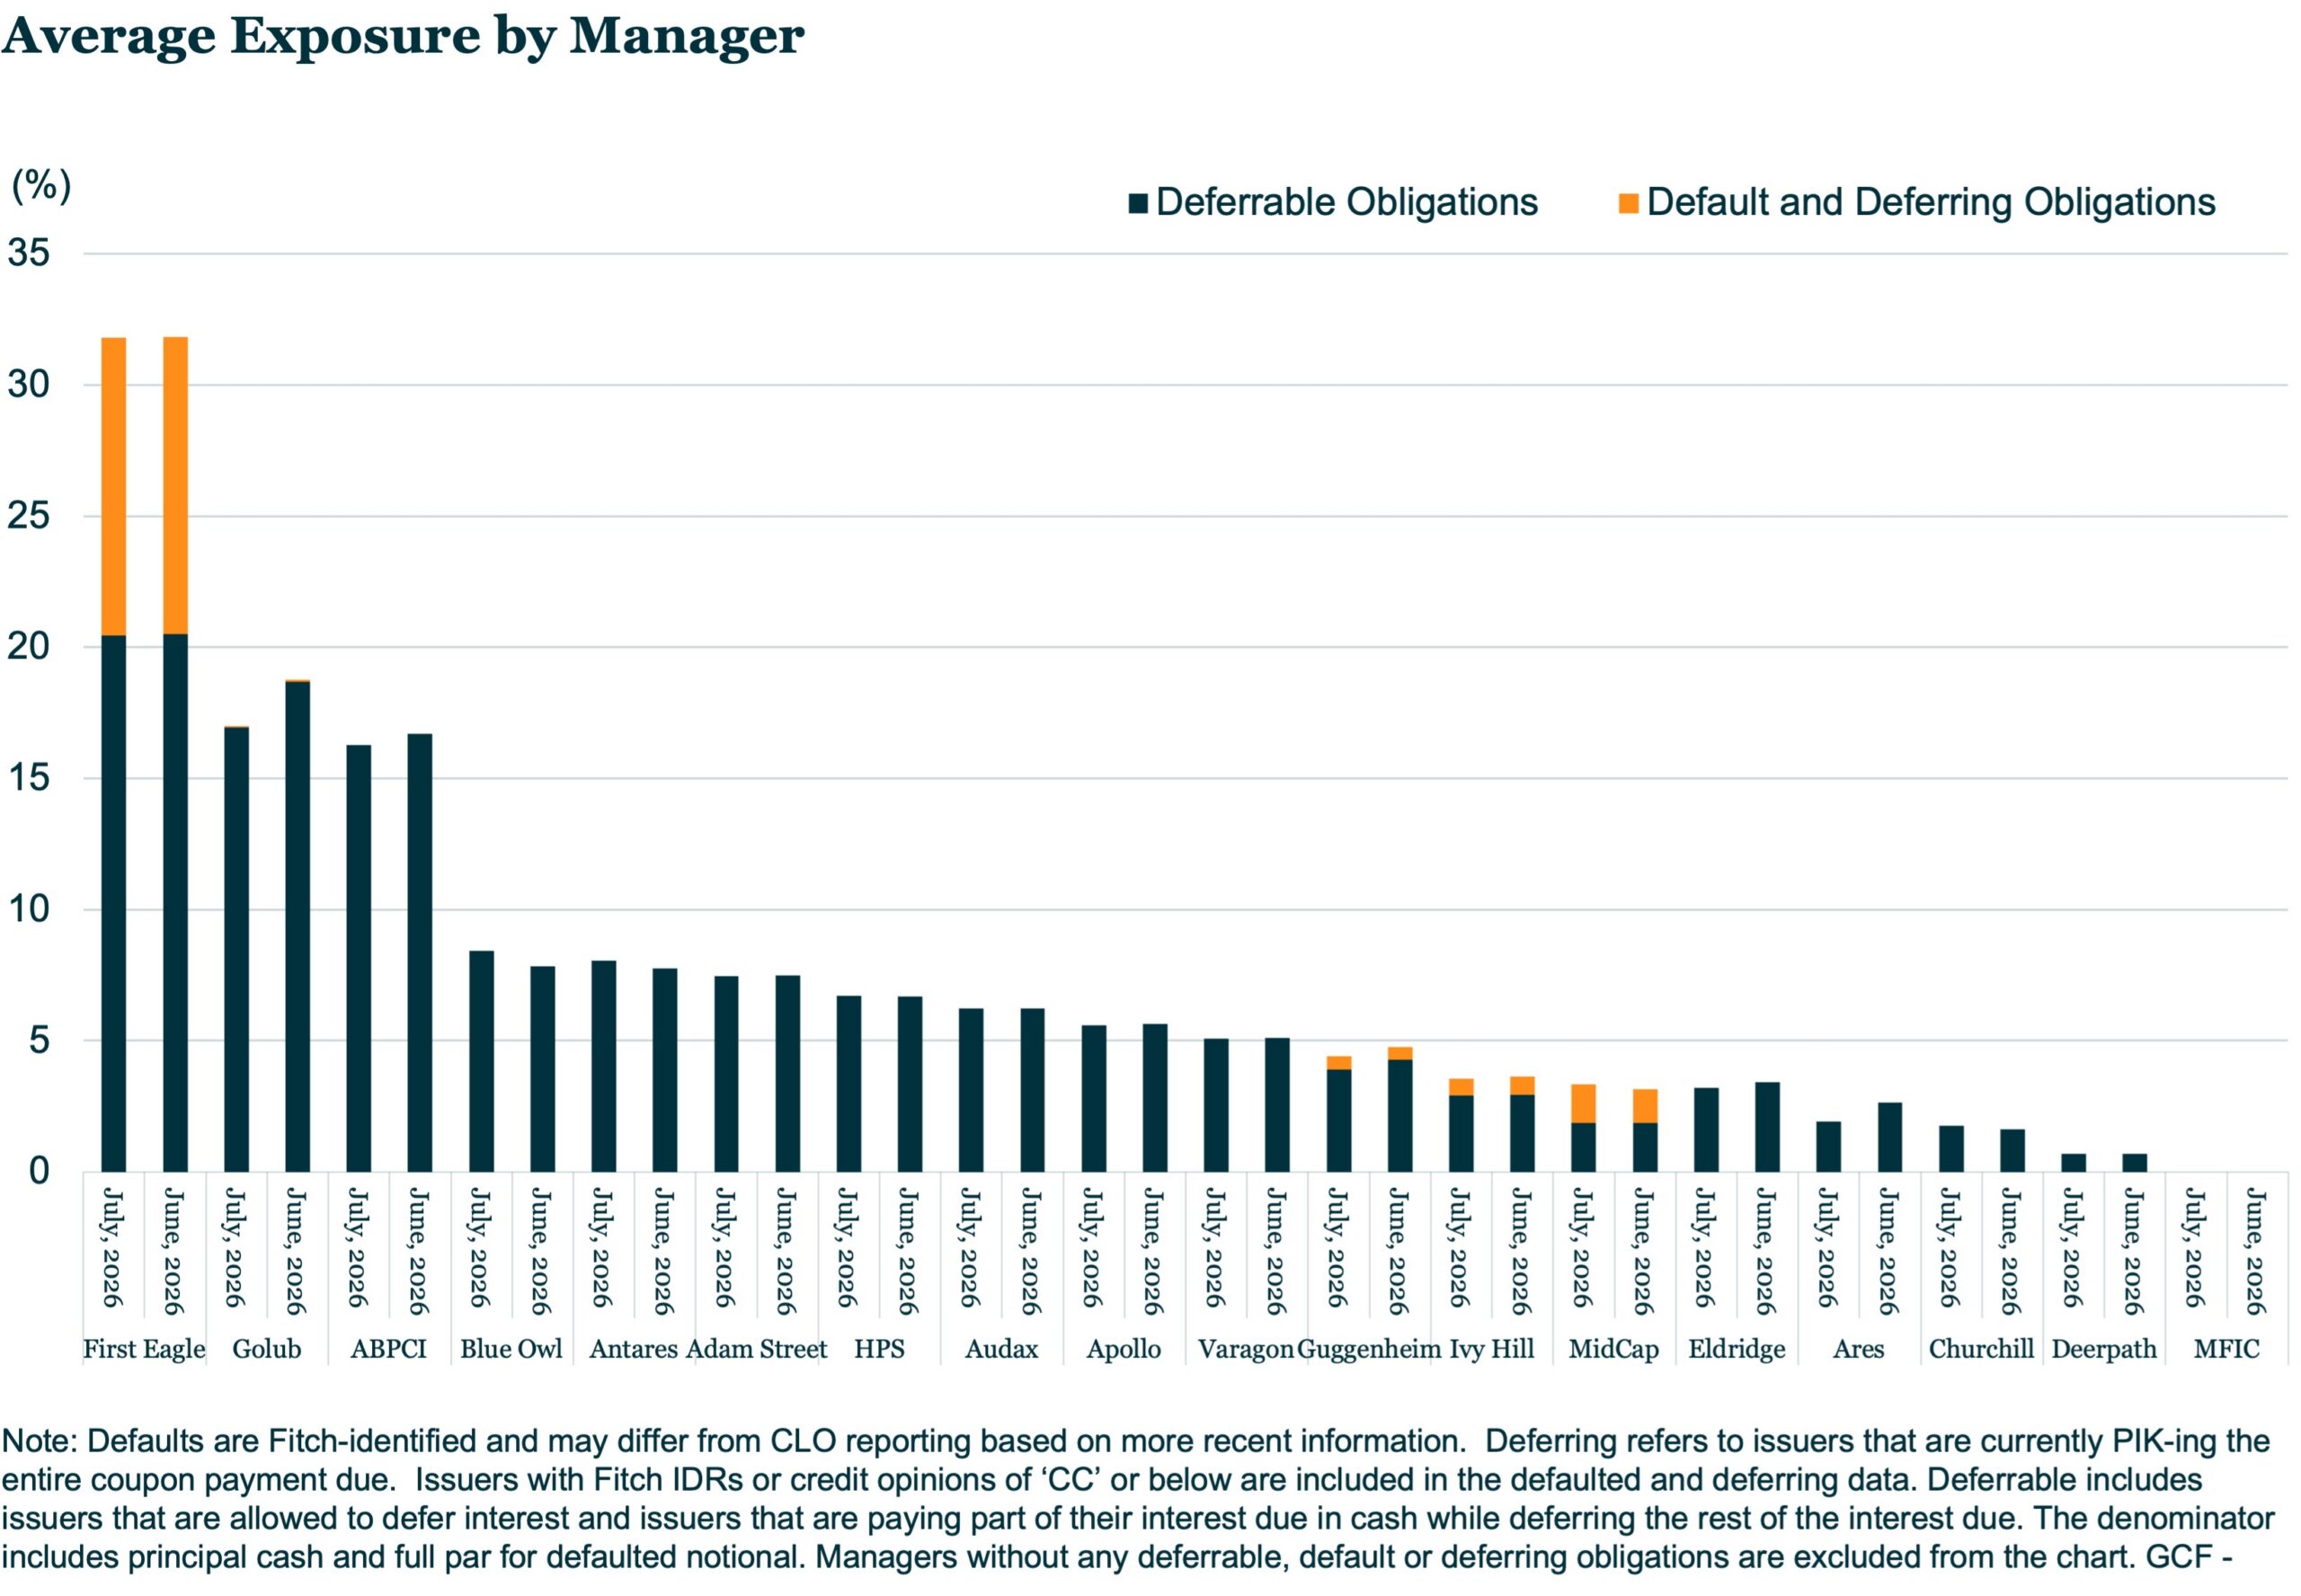
In July 2026, portfolio credit quality in reinvesting Fitch-rated U.S. BSL CLOs remained broadly stable from June. Net portfolio losses held at 0.5%. The Fitch weighted average rating factor also held at 23.1. The Fitch weighted average recovery rate declined slightly by 0.1%, while the weighted average spread fell by 0.01%.
Performance in the U.S. MM CLO sector was similar. Net portfolio losses held at 0.3%. The Fitch weighted average rating factor remained at 30.5, and the Fitch weighted average recovery rate stayed at 74.9%. The weighted average spread declined by 0.01%. Fitch recorded one obligor default in Fitch-rated MM CLOs in July.
Contact Brad Hamner




Private Credit Defaults 101: Back to School
As Labor Day approaches, the unofficial end of summer is upon us. But, before we get too sad, there is also the familiar back-to-school energy.