


Click here to learn more.
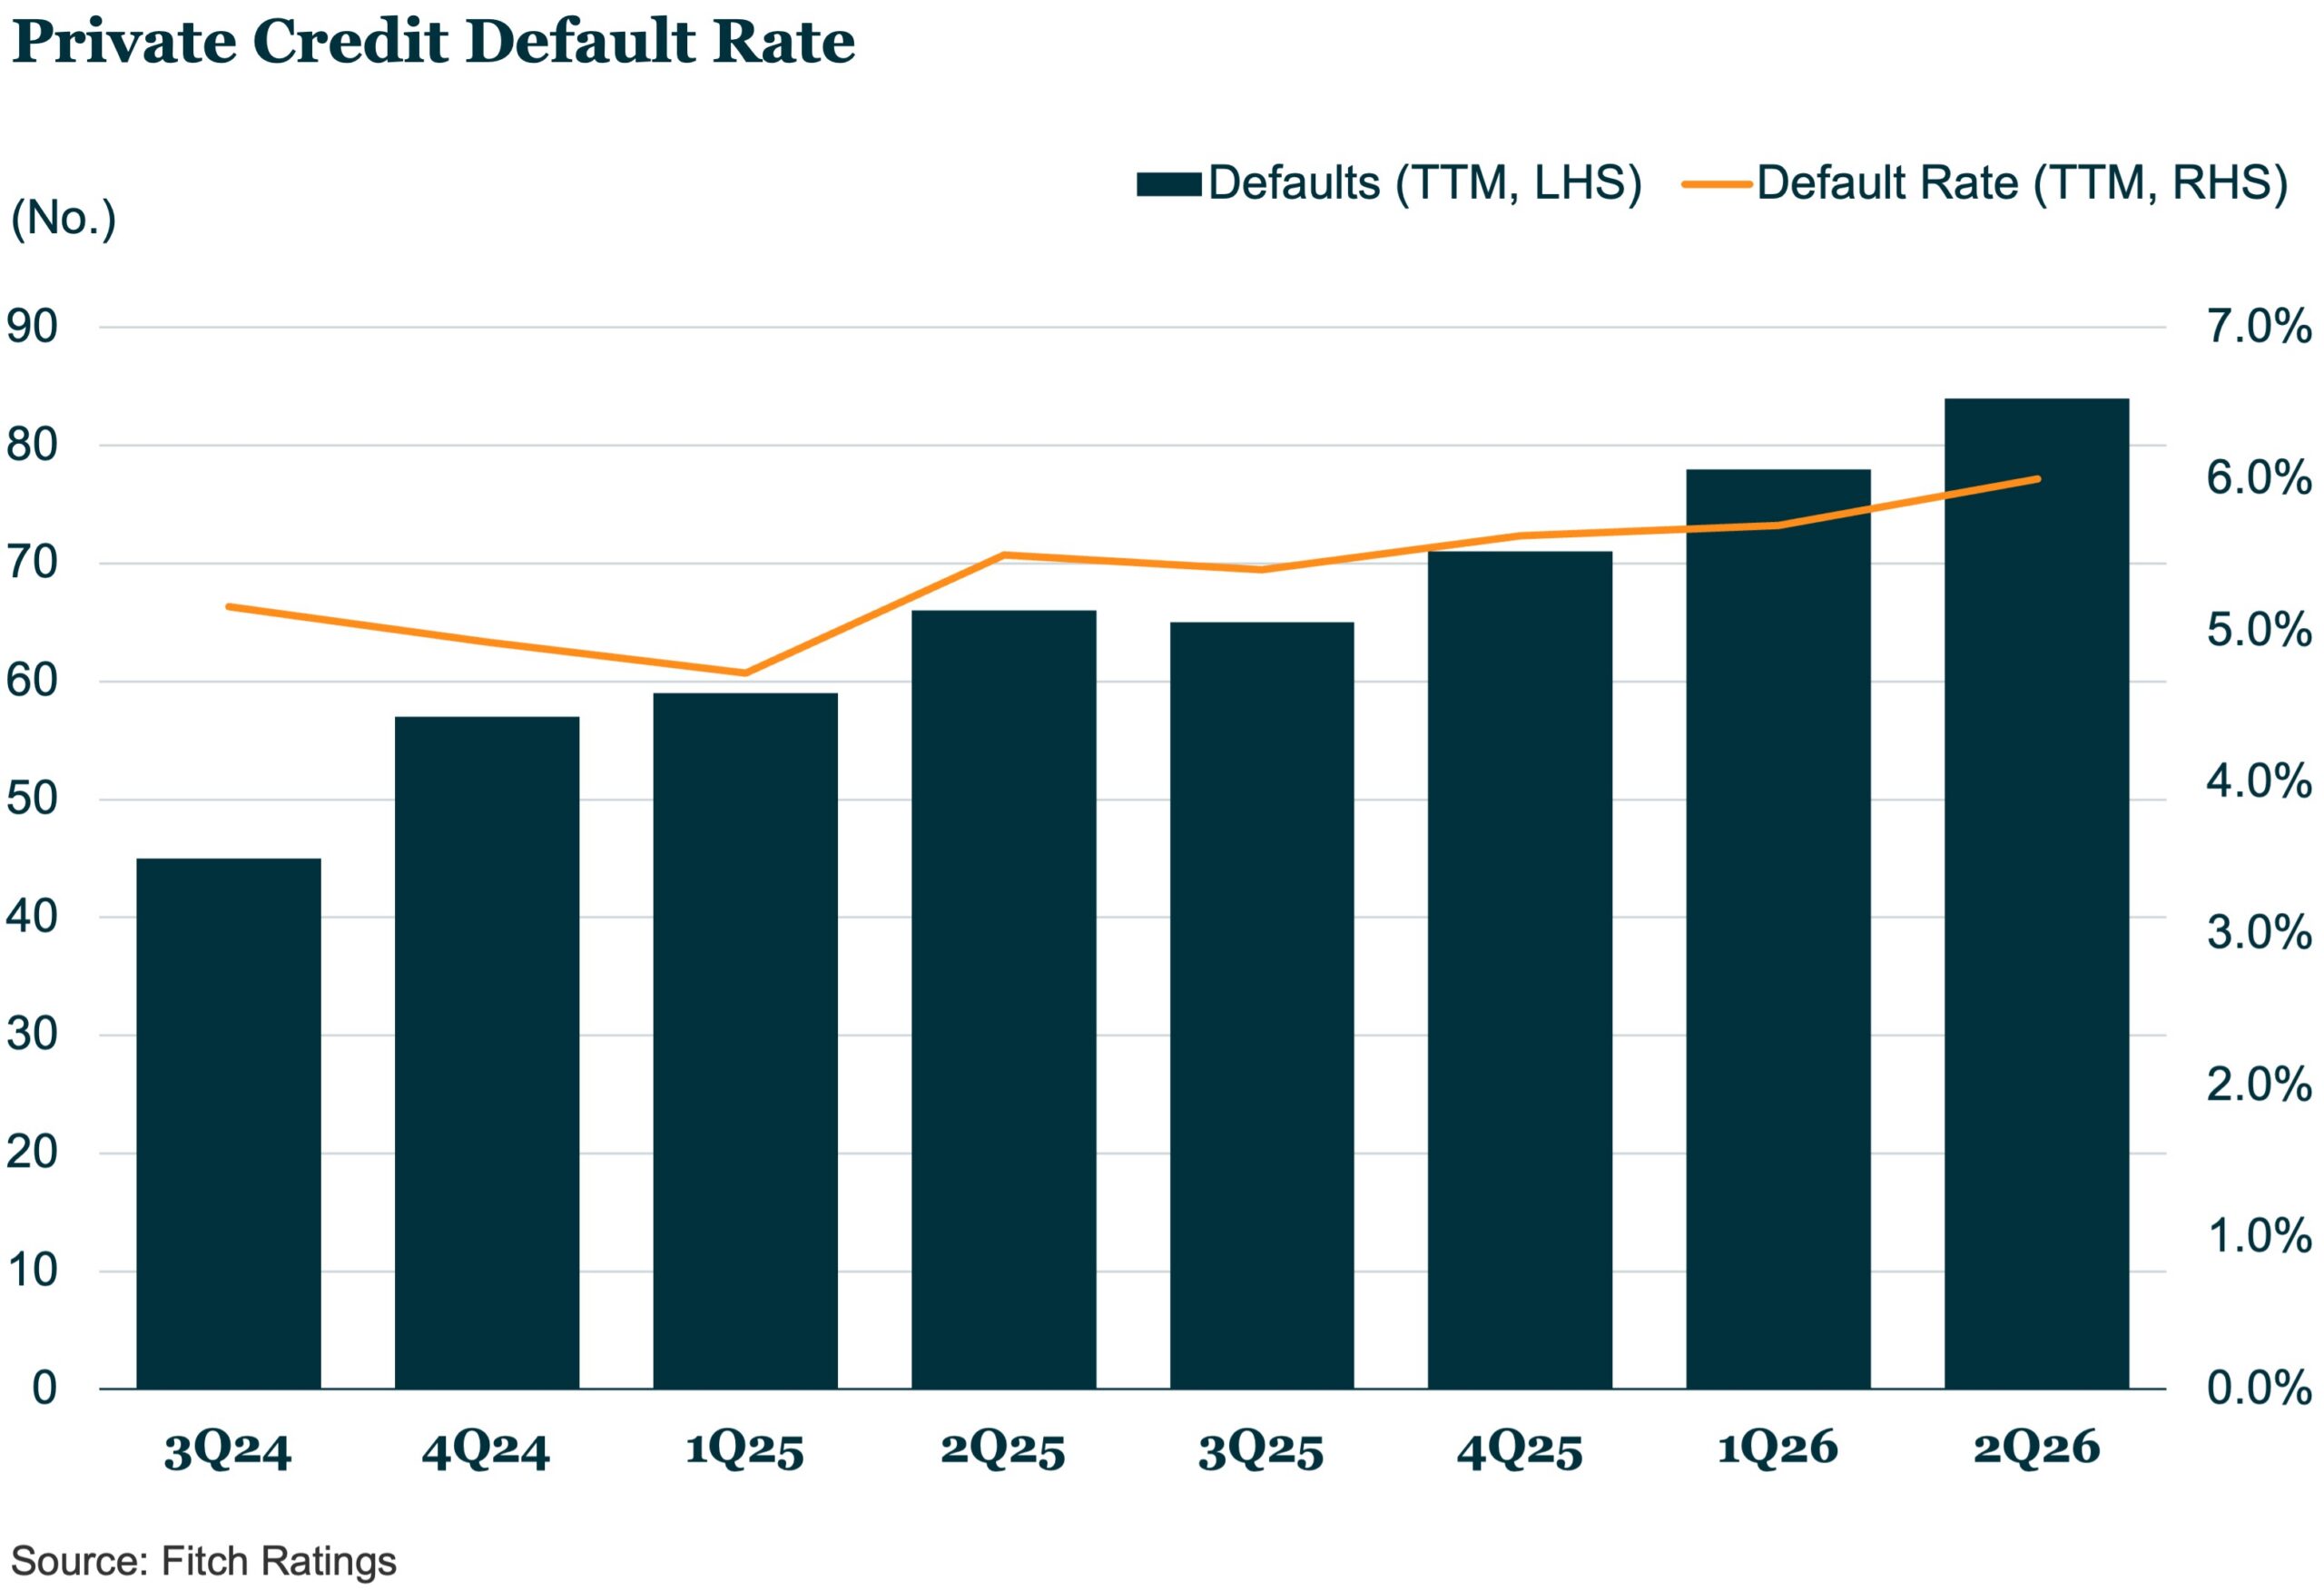
Fitch Ratings’ U.S. Private Credit Default Rate (PCDR) rose to a new high in 2Q26, according to a new report. The increase was driven by higher defaults in Fitch’s Model-Based Credit Opinion (MCO) portfolio despite modest improvement in the privately monitored ratings (PMR) portfolio. PMRs are ratings typically used by insurance companies, which need ratings on the loans for regulatory capital purposes. MCOs are credit opinions that feed ratings for pooled assets like middle market CLOs.
The PCDR increased to 6.0% for the trailing 12 months (TTM) ended 2Q26, up from the prior record of 5.7% in 1Q26. Fitch recorded 32 private credit default events from 20 new unique defaulters during the quarter, bringing the TTM total to 84 unique defaulters, up from 78 in 1Q26.
Default activity also shifted during the quarter. Maturity extensions under stress overtook payment-in-kind and interest rate deferrals as the leading driver of quarterly defaults in 2Q26, accounting for more than half of the quarter’s 32 recorded default events.


Latest news
US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
