


Two trends have emerged from our latest fundraising data to the end of Q3.
The US is no longer the capital magnet it used to be. The April ‘Liberation Day’ tariffs were perhaps the biggest shock among the political turbulence that has been unsettling financial markets throughout the year, and investors have been reassessing their view of where money is most sensibly deployed.
“It’s important to diversify into other locations and other jurisdictions to hedge our exposure in the US,” an anonymous source at an Asia-Pacific-based insurer told us. “Certainly, the political and the tariff situation creates concerns about credit quality domestically, which has yet to materialise.”
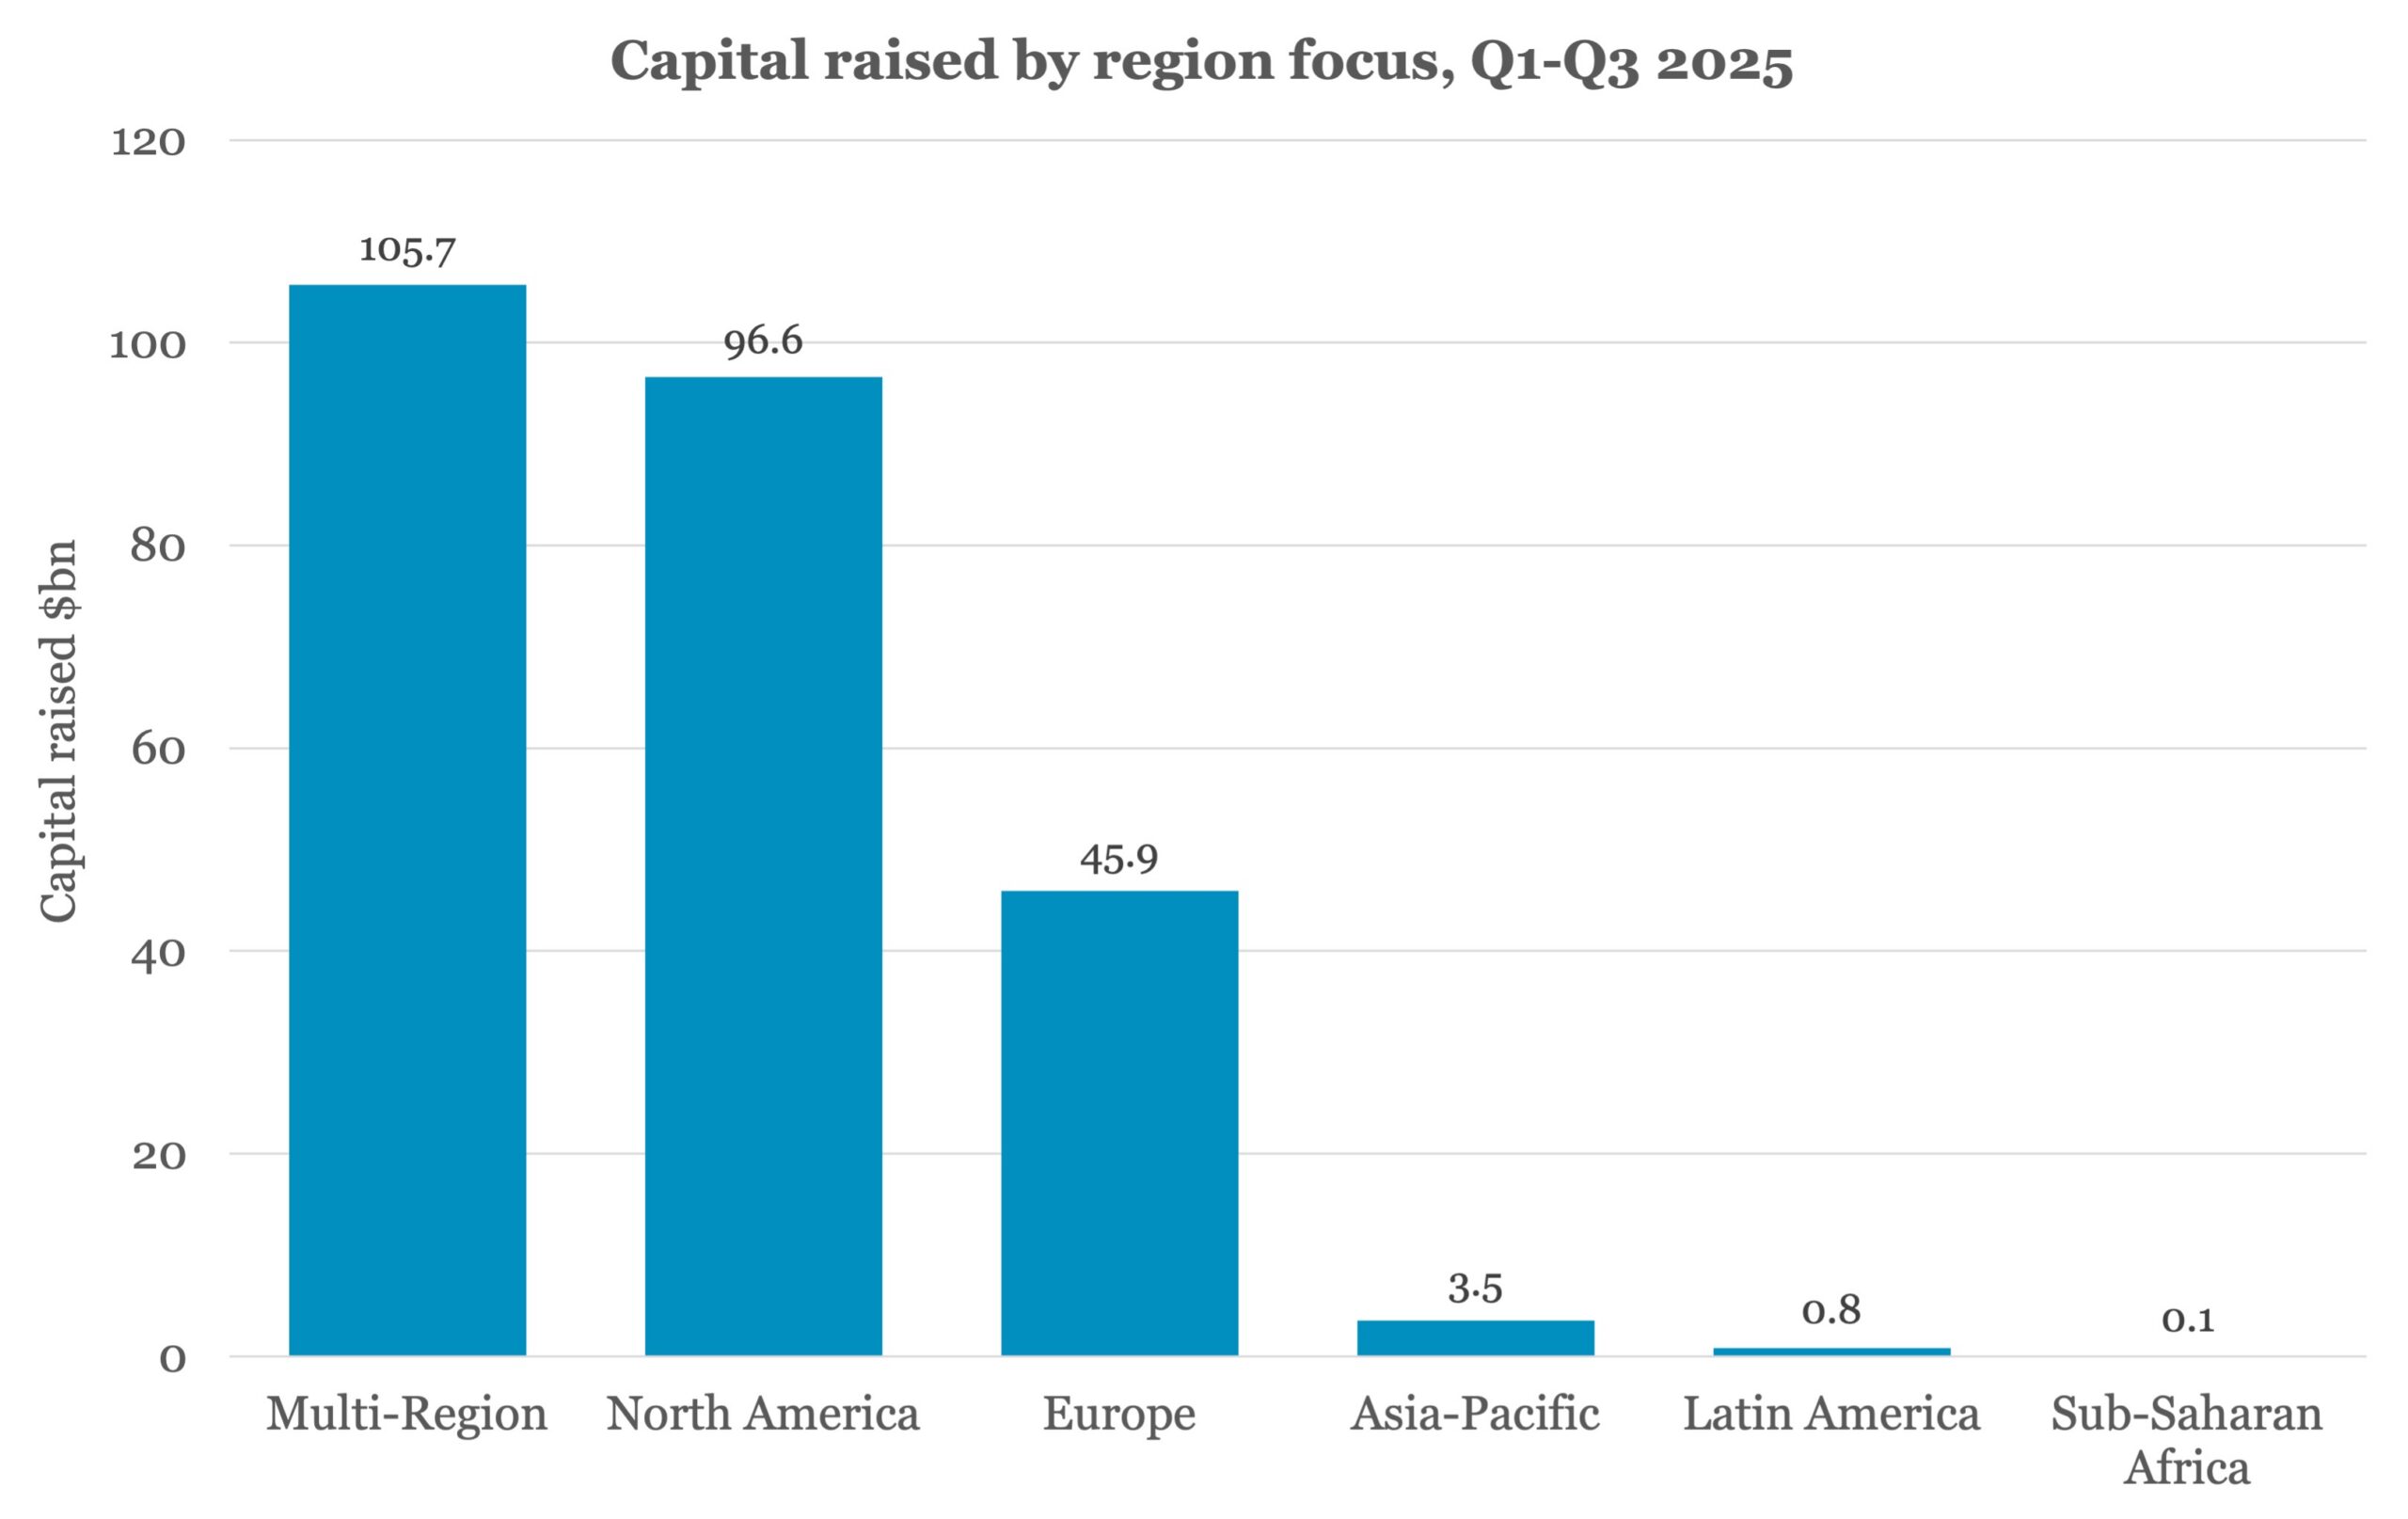
But while we have had plenty of LPs expressing this type of opinion to us, there’s nothing quite like data to back it up. In our latest fundraising data, taking us through the first three quarters of this year, we find that – for the first time – funds focused on North America are no longer the main attraction for LPs committing to private debt (see chart).
Instead, multi-regional funds (investing in more than one region, but not necessarily globally) led the way to the end of Q3 with almost $106 billion raised, ahead of North American funds on nearly $97 billion. This suggests that LPs are seeking geographical diversification, while not yet embracing European funds (almost $46 billion) to the extent that some may have predicted –at least not yet.
Our data also confirms that another predicted trend has materialised. On the back of large fundraisings from the likes of Dawson Partners ($8.2 billion), Coller Capital ($6.8 billion), 17Capital ($5.5 billion) and Pantheon ($5.2 billion), private debt secondaries appear to have come of age.
In the year to the end of Q3, secondaries accounted for 16 percent of total private debt fundraising globally. This represents a major advance considering it was a mere speck on the fundraising landscape for the previous five years – accounting for between 1 and 4 percent of the total each year.
It’s clear that geographic diversification and the rise of secondaries are no longer mere talk. There is a caveat, however, which naturally cautious debt investors will appreciate: only future surveys will tell us whether these are trends that outlast the present and become established.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
