


Investor allocations to private credit climbed by nearly a quarter year-on-year as positive sentiment shows no sign of weakening.
The latest version of PEI Private Credit’s annual Global Investor 75 ranking measured the biggest investors in private credit globally. Here are our top six takeaways from this year’s ranking:
1) Going strong: Private credit allocations among the world’s largest institutional investors continue to climb. Combined private debt allocations across this year’s top 75 reached $1.12 trillion, up roughly 23 percent year-on-year, a clear signal that private credit remains one of the fastest-growing allocations among the world’s biggest LPs.
2) Steady leadership at the top: Allianz Group, MetLife Investment Management, Prudential Financial, and TIAA/Nuveen retained the top four positions for a second consecutive year, underscoring the durability of the largest insurance-driven private credit books.
3) Broadening participation: Nine institutions entered the ranking for the first time (including re-additions) this year: Pensioenfonds Zorg en Welzijn, AXA Group, Voya Financial, and Aware Super, reflecting both growing allocations to the asset class and improved transparency from LPs willing to share primary data.
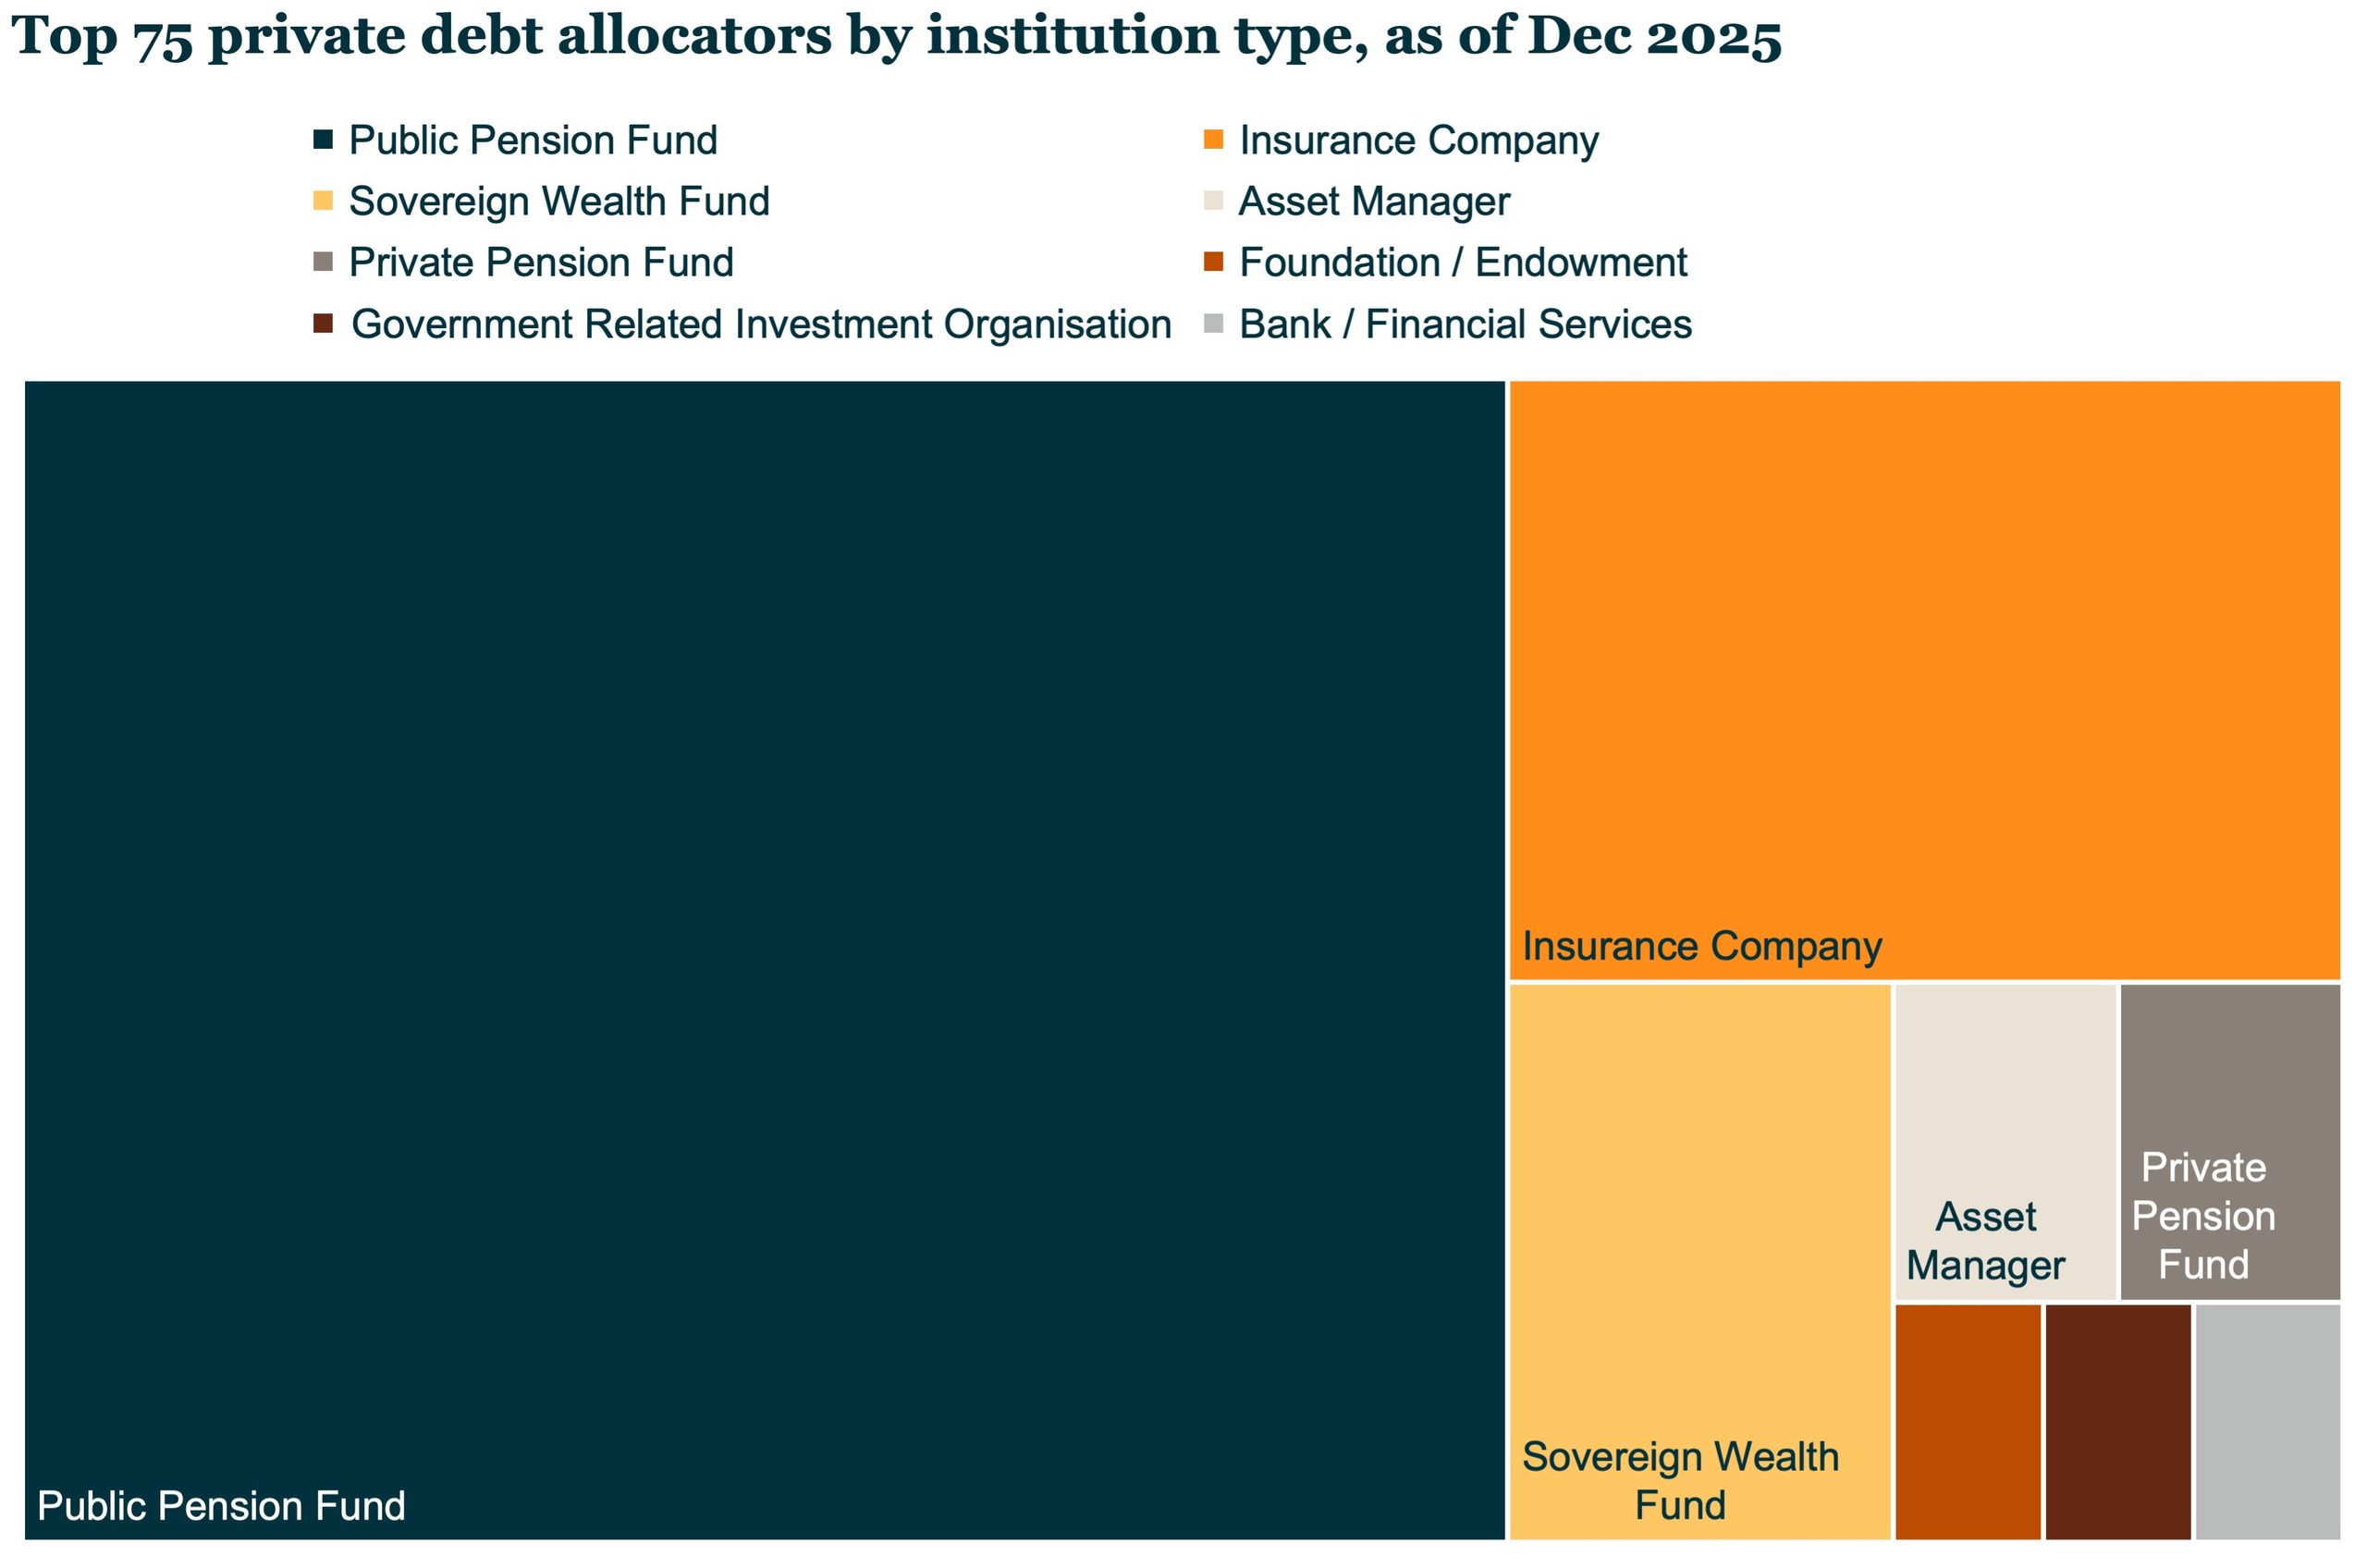
4) Public pensions lead by number: Public pension funds make up the largest share of the ranking (48 of 75 entrants), followed by insurance companies (14) and sovereign wealth funds (6), reflecting how central private credit has become to long-duration investors (see chart).
5) Geographic reach: North America continues to anchor the ranking (44 institutions), with Western Europe (17) and Asia-Pacific (13) representing meaningful and growing pools of capital, plus continued representation from the Middle East, mainly through Mubadala.
6) Growth grounded in real portfolio activity: Where institutions shared colour on their increases, the drivers were consistent with a healthy market: strong private markets performance, continued capital deployment toward strategic target allocations, and net new contributions rather than one-off reclassifications alone.




Latest news

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.

Direct lending volume fell 3% q-o-q to US$61bn in 3Q26
US direct lending issuance weakened in 3Q26, marking its third consecutive quarterly decline. Volume fell 3% quarter-over-quarter to US$61bn, 30%…