
Despite subpar returns from many such funds, the strategy continues to attract LP dollars.
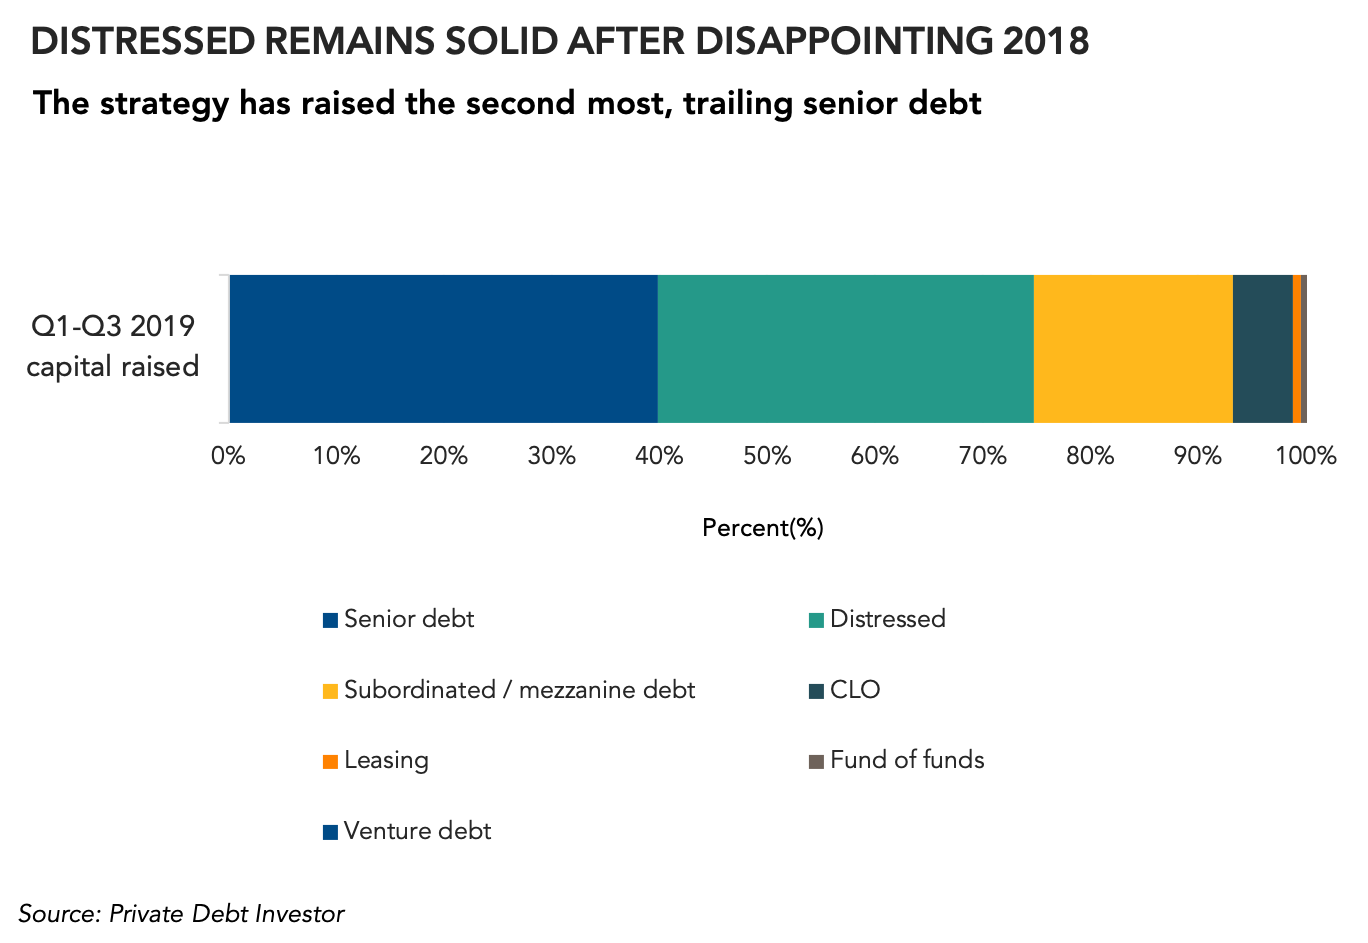
Distressed debt has continued its strong fundraising, with a total of $39.44 billion, or 35 percent, of the $112.69 billion that private credit funds have raised through the first three quarters of the year, according to PDI data.
The strategy is continuing its strong fundraising numbers after a disappointing 16.35 percent of all capital raised last year, some $25.26 billion of $154.44 billion. And this is despite lacklustre returns across even some of the industry’s biggest names and at a time of relative famine for these managers.
Distressed debt will probably post strong numbers for the rest of the year too.
JP Morgan Asset Management announced a $1.06 billion special situations global fund close earlier this week, and Bain Capital is seeking $3 billion for its Bain Distressed and Special Situations 2019 fund. In addition, Fortress Investment Group is seeking money for its next flagship Credit Opportunities Fund, which is likely to be a large raise if the almost $5 billion size of Fund IV is any guide.
There is a good chance that distressed will have a comeback in 2019; now if only there’d be dealflow to match the fundraising numbers.
Latest news
Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.
Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.
Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…