


For investors in private credit wanting to build up their allocations, criticism of the asset class is a sideshow – for now at least.
“LPs shutting out the noise” was the theme of a recently published Private Debt Investor feature, which reflected on the positive sentiments of limited partners towards the asset class, despite the fact that recent headlines in the mainstream press have been less than flattering.
The distinction which the feature drew was between those who focus on short-term concerns over the level of redemptions from semi-liquid vehicles as well as a sense that there is more stress in private credit portfolios than meets the eye, versus those with a more long-term and strategic view who believe private credit fills a vital role in their portfolios.
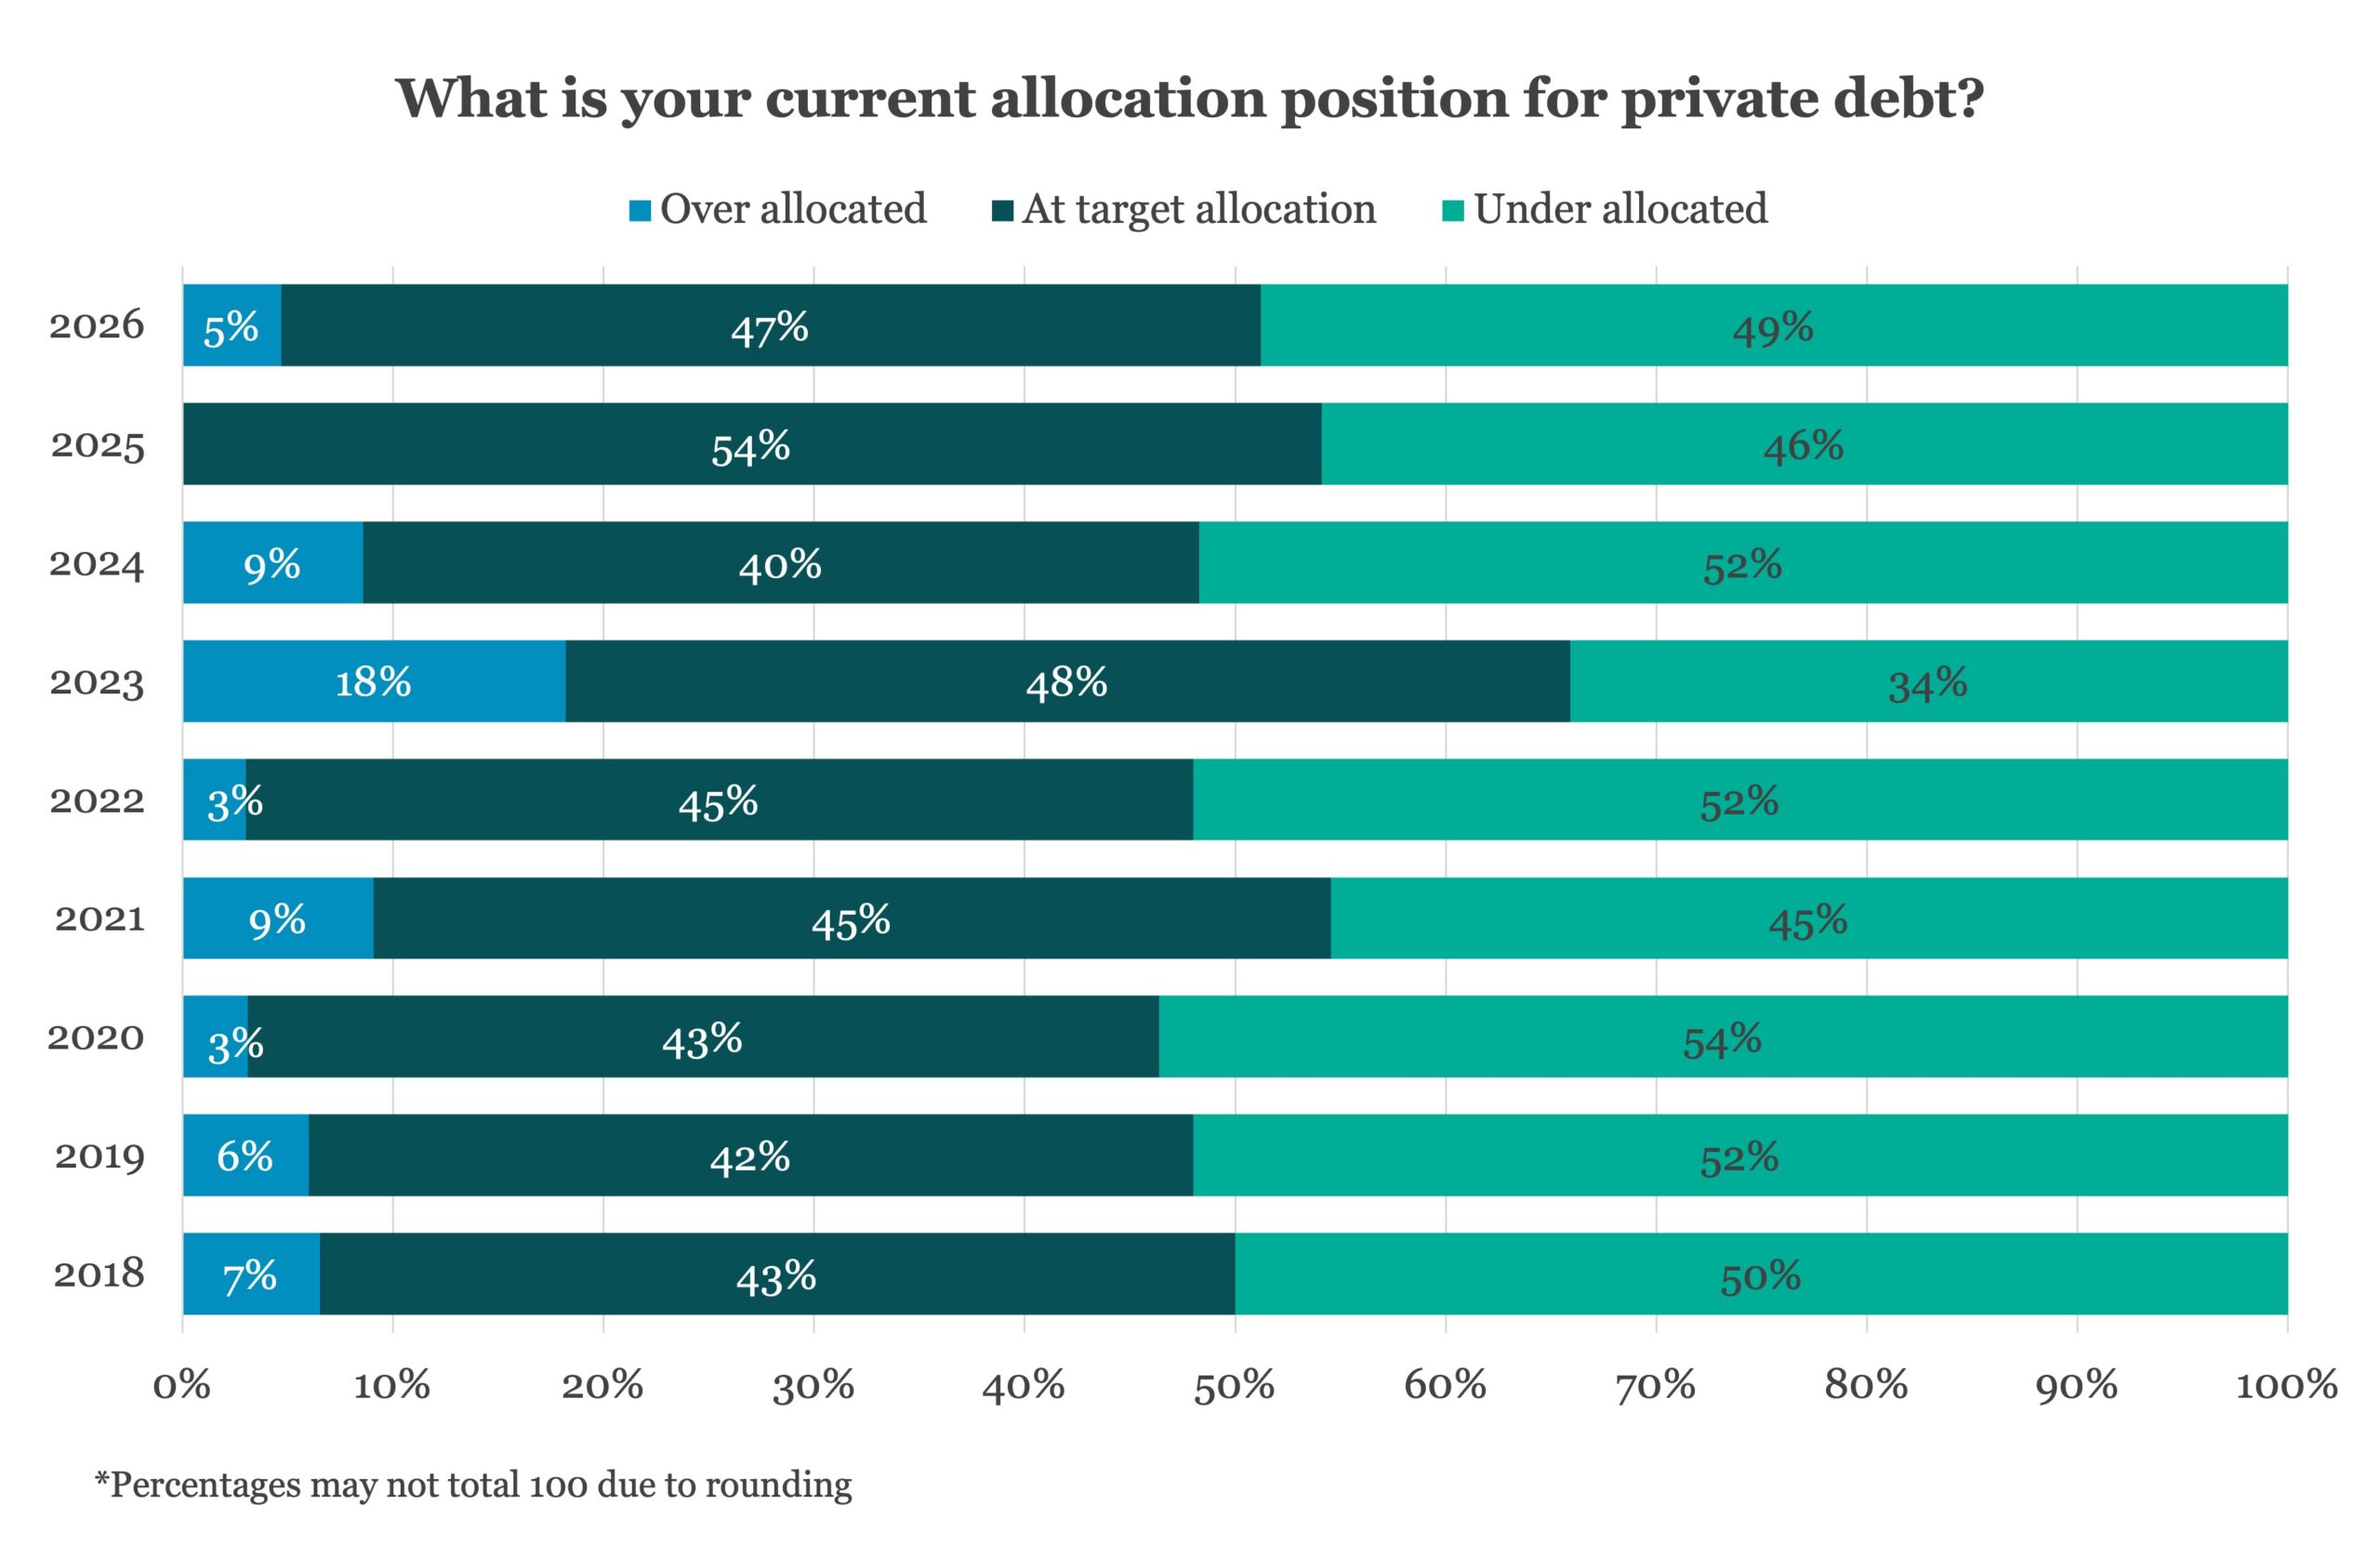
Our LP Perspectives 2026 study provided some clues as to why LPs are not inclined to respond in a knee-jerk manner to the latest negative headlines. For one thing, many of them – having decided private credit is broadly a good thing – are far short of their allocation targets. Our survey found almost half (49 percent) to be under-allocated compared with 5 percent over-allocated (see chart).
There is also very little evidence of underperformance – whether this will change in future is speculative but based on the data in front of LPs right now, there’s no obvious cause for alarm. Looking back over the last 12 months, 31 percent said private credit had outperformed benchmarks and only 7 percent said it had underperformed.
While that backward-looking performance picture is encouraging, so too is the forward-looking one. Asked how they expect private credit to perform against benchmarks over the next year, 35 percent expected outperformance and 14 percent underperformance.
If there’s a sting in the tail, the percentage expecting underperformance has doubled – indicated that the noise may be a worry for some. Amid such volatile market conditions, LPs will of course be keeping a close eye out for any material signs of trouble – contagion that goes beyond particular sectors or types of business. But, so far, there are few signs of panic in the ranks.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
