


Investor redemptions have created some negative headlines around the asset class, with concern focused on fund structuring.
Private credit’s evergreen challenges are the fault of poor design or marketing, rather than an inherent issue with the underlying asset class. That was the message for attendees at the Milken Institute Global Investors’ Symposium 2026 in Hong Kong, as reported by our colleagues on Private Equity International.
“The whole reason there’s an extra return is because it’s illiquid and locked up, so I think the cardinal sin here isn’t private credit or private markets in general, it’s trying to make them liquid,” said Aaron Costello, head of Asia at LP consultancy Cambridge Associates. “Some of these vehicles were mis-sold and mis-structured from the beginning.”
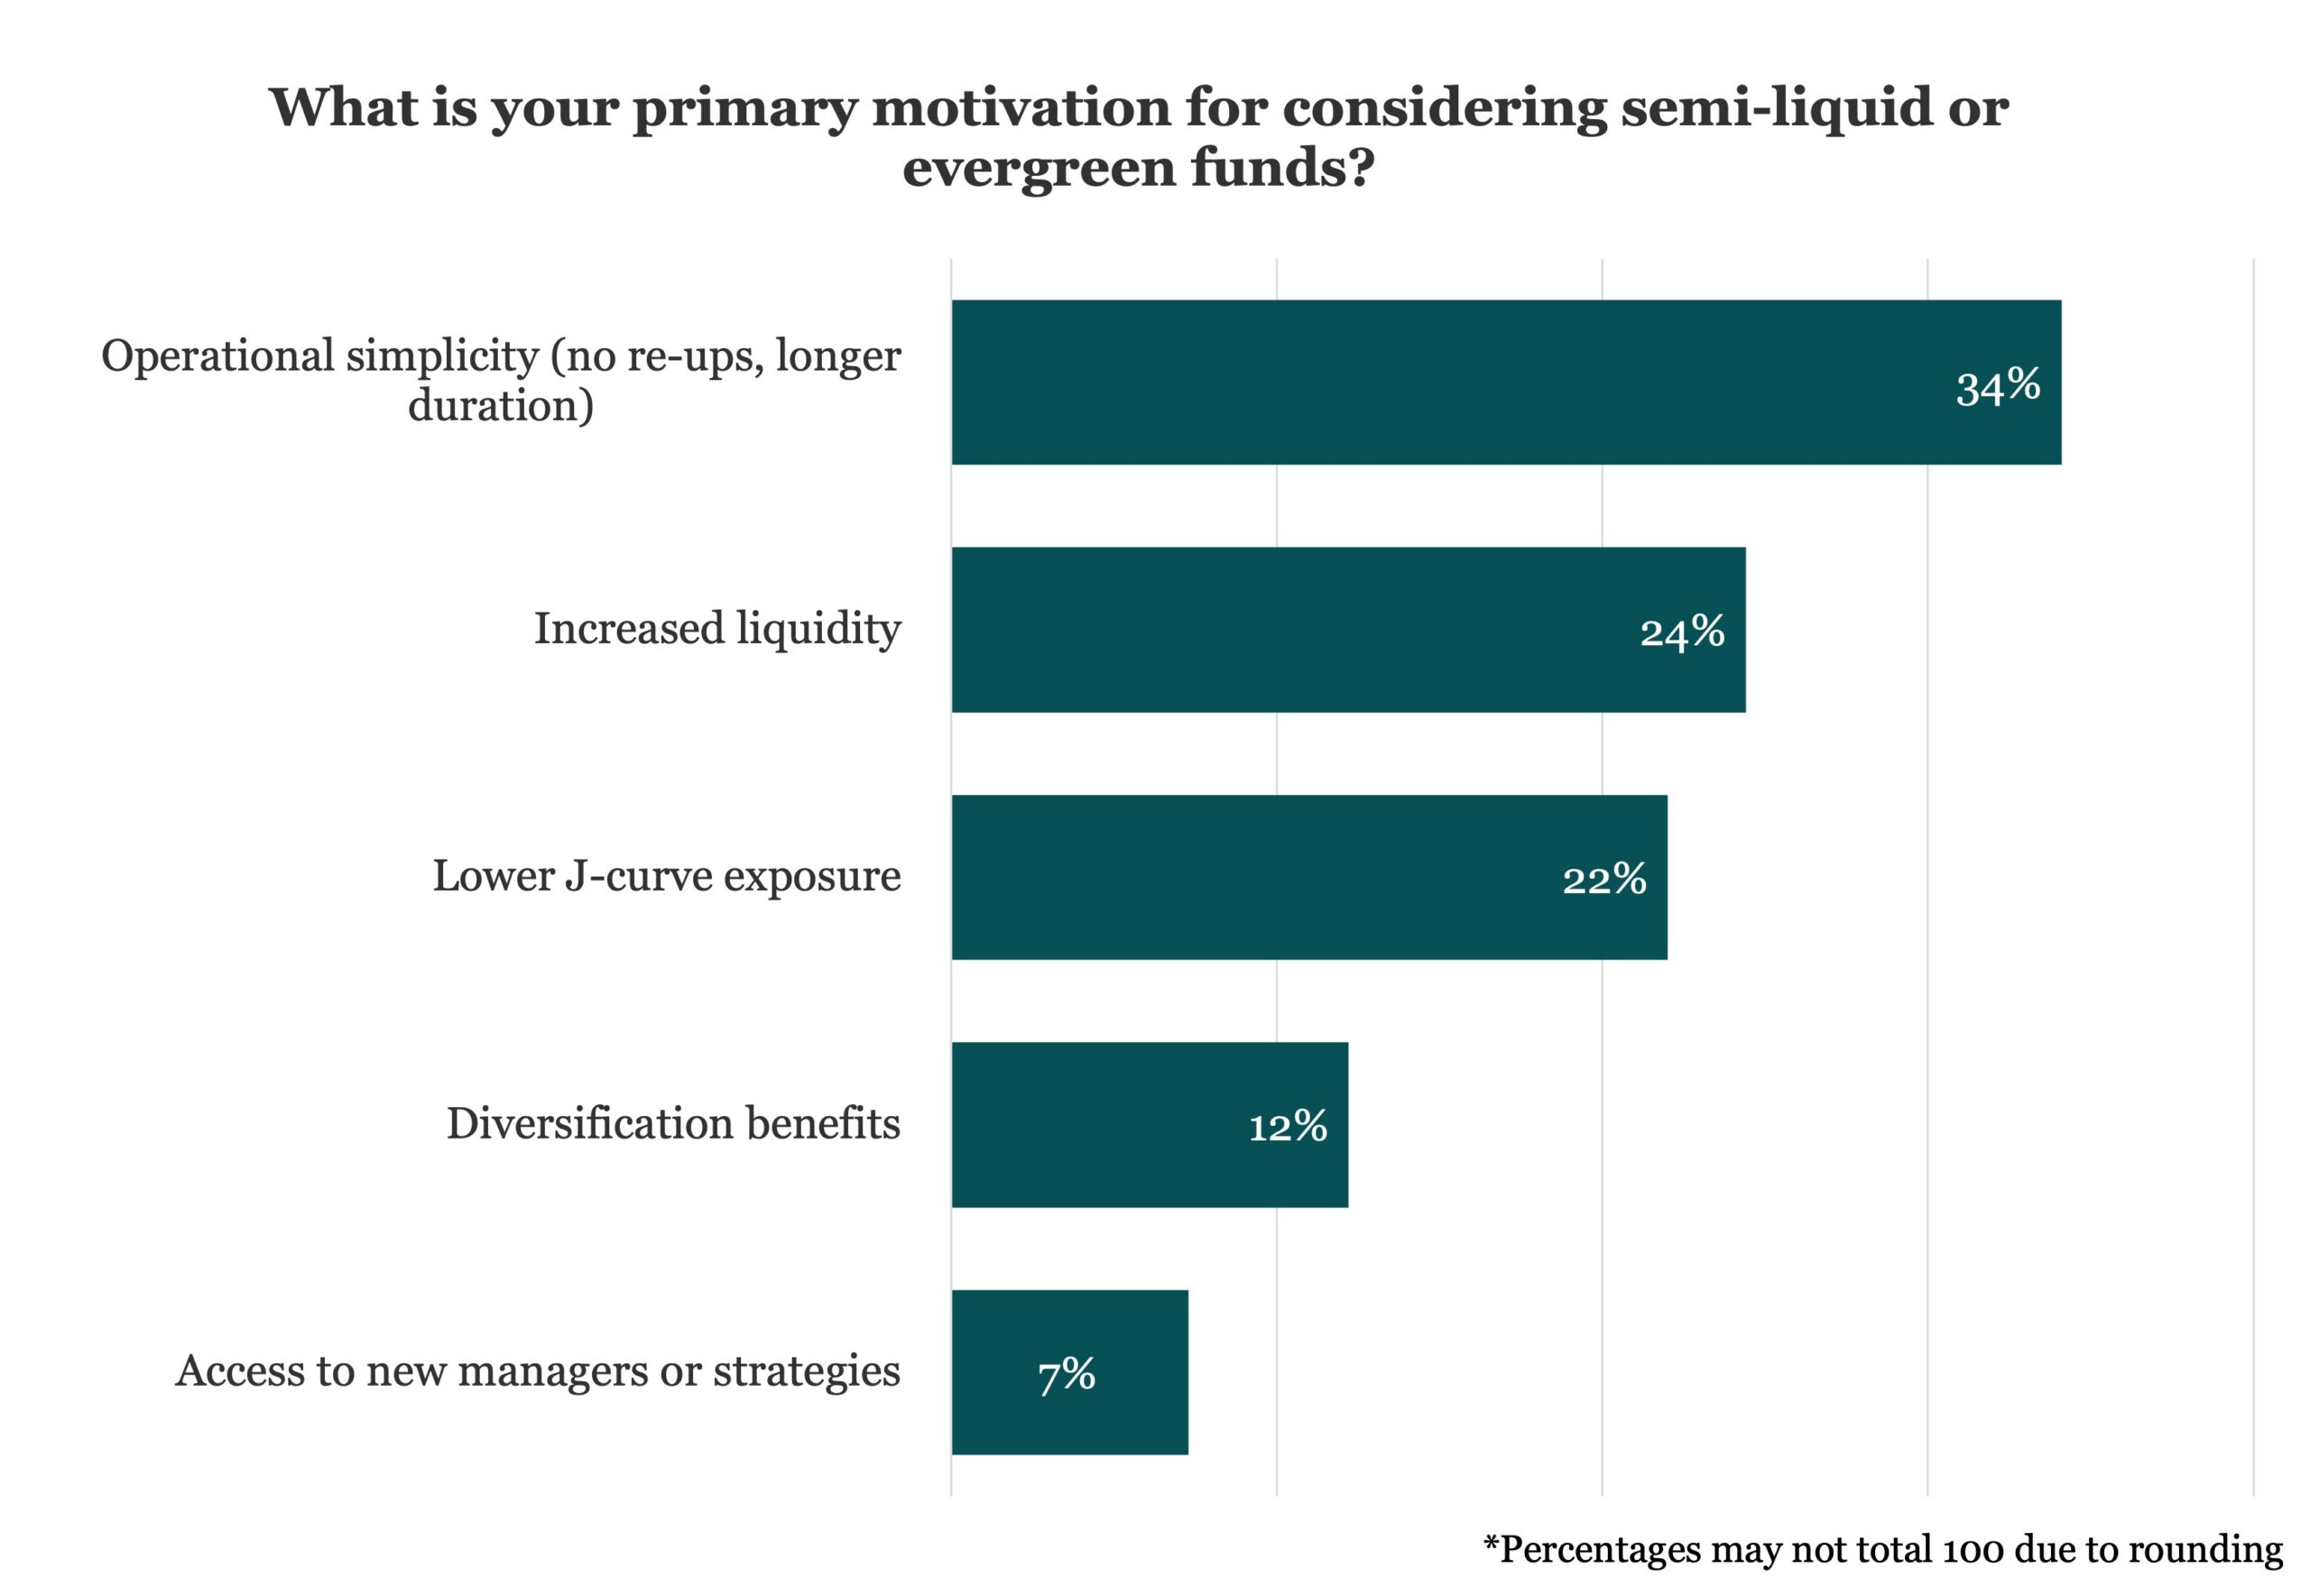
Our LP Perspectives survey found around a quarter of investors citing liquidity as their primary motivation for considering semi-liquid or evergreen funds (see chart) – behind only operational simplicity as a reason.
One positive to result from the furore is that it should accelerate investor education and underscore the importance of manager selection. Certain vehicles, Costello noted, may not be as well diversified. “There’s plenty of opportunities in private credit, and in fact, the distress in some of these [funds] is going to create opportunities for other funds that can pivot into that,” he said.
Costello was joined on stage by Kevin Lu, Asia chairman of Partners Group, who noted: “There [are] so many different forms of private lending that’s going on within this banner of private credit… people need to look specifically at which bucket of that is a problem and which is not. The majority of this space is not problematic in my view; a bigger problem is I think some of our friendly peers probably have structured in a way that is a little… too adventurous from a liquidity perspective.”
Wealth-focused credit vehicles are facing increased scrutiny in the US over valuations, allocations, redemption rights and fees and expenses. If mis-structuring and mis-selling are perceived to be to blame for private credit’s redemption issues, rather than a reflection of the underlying asset quality, it’s quite possible that evergreens in other corners of private markets will ultimately face similar issues, too.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.