


The likes of pensions and insurers are, if anything, accelerating their commitments to private credit – despite the retail redemption saga.
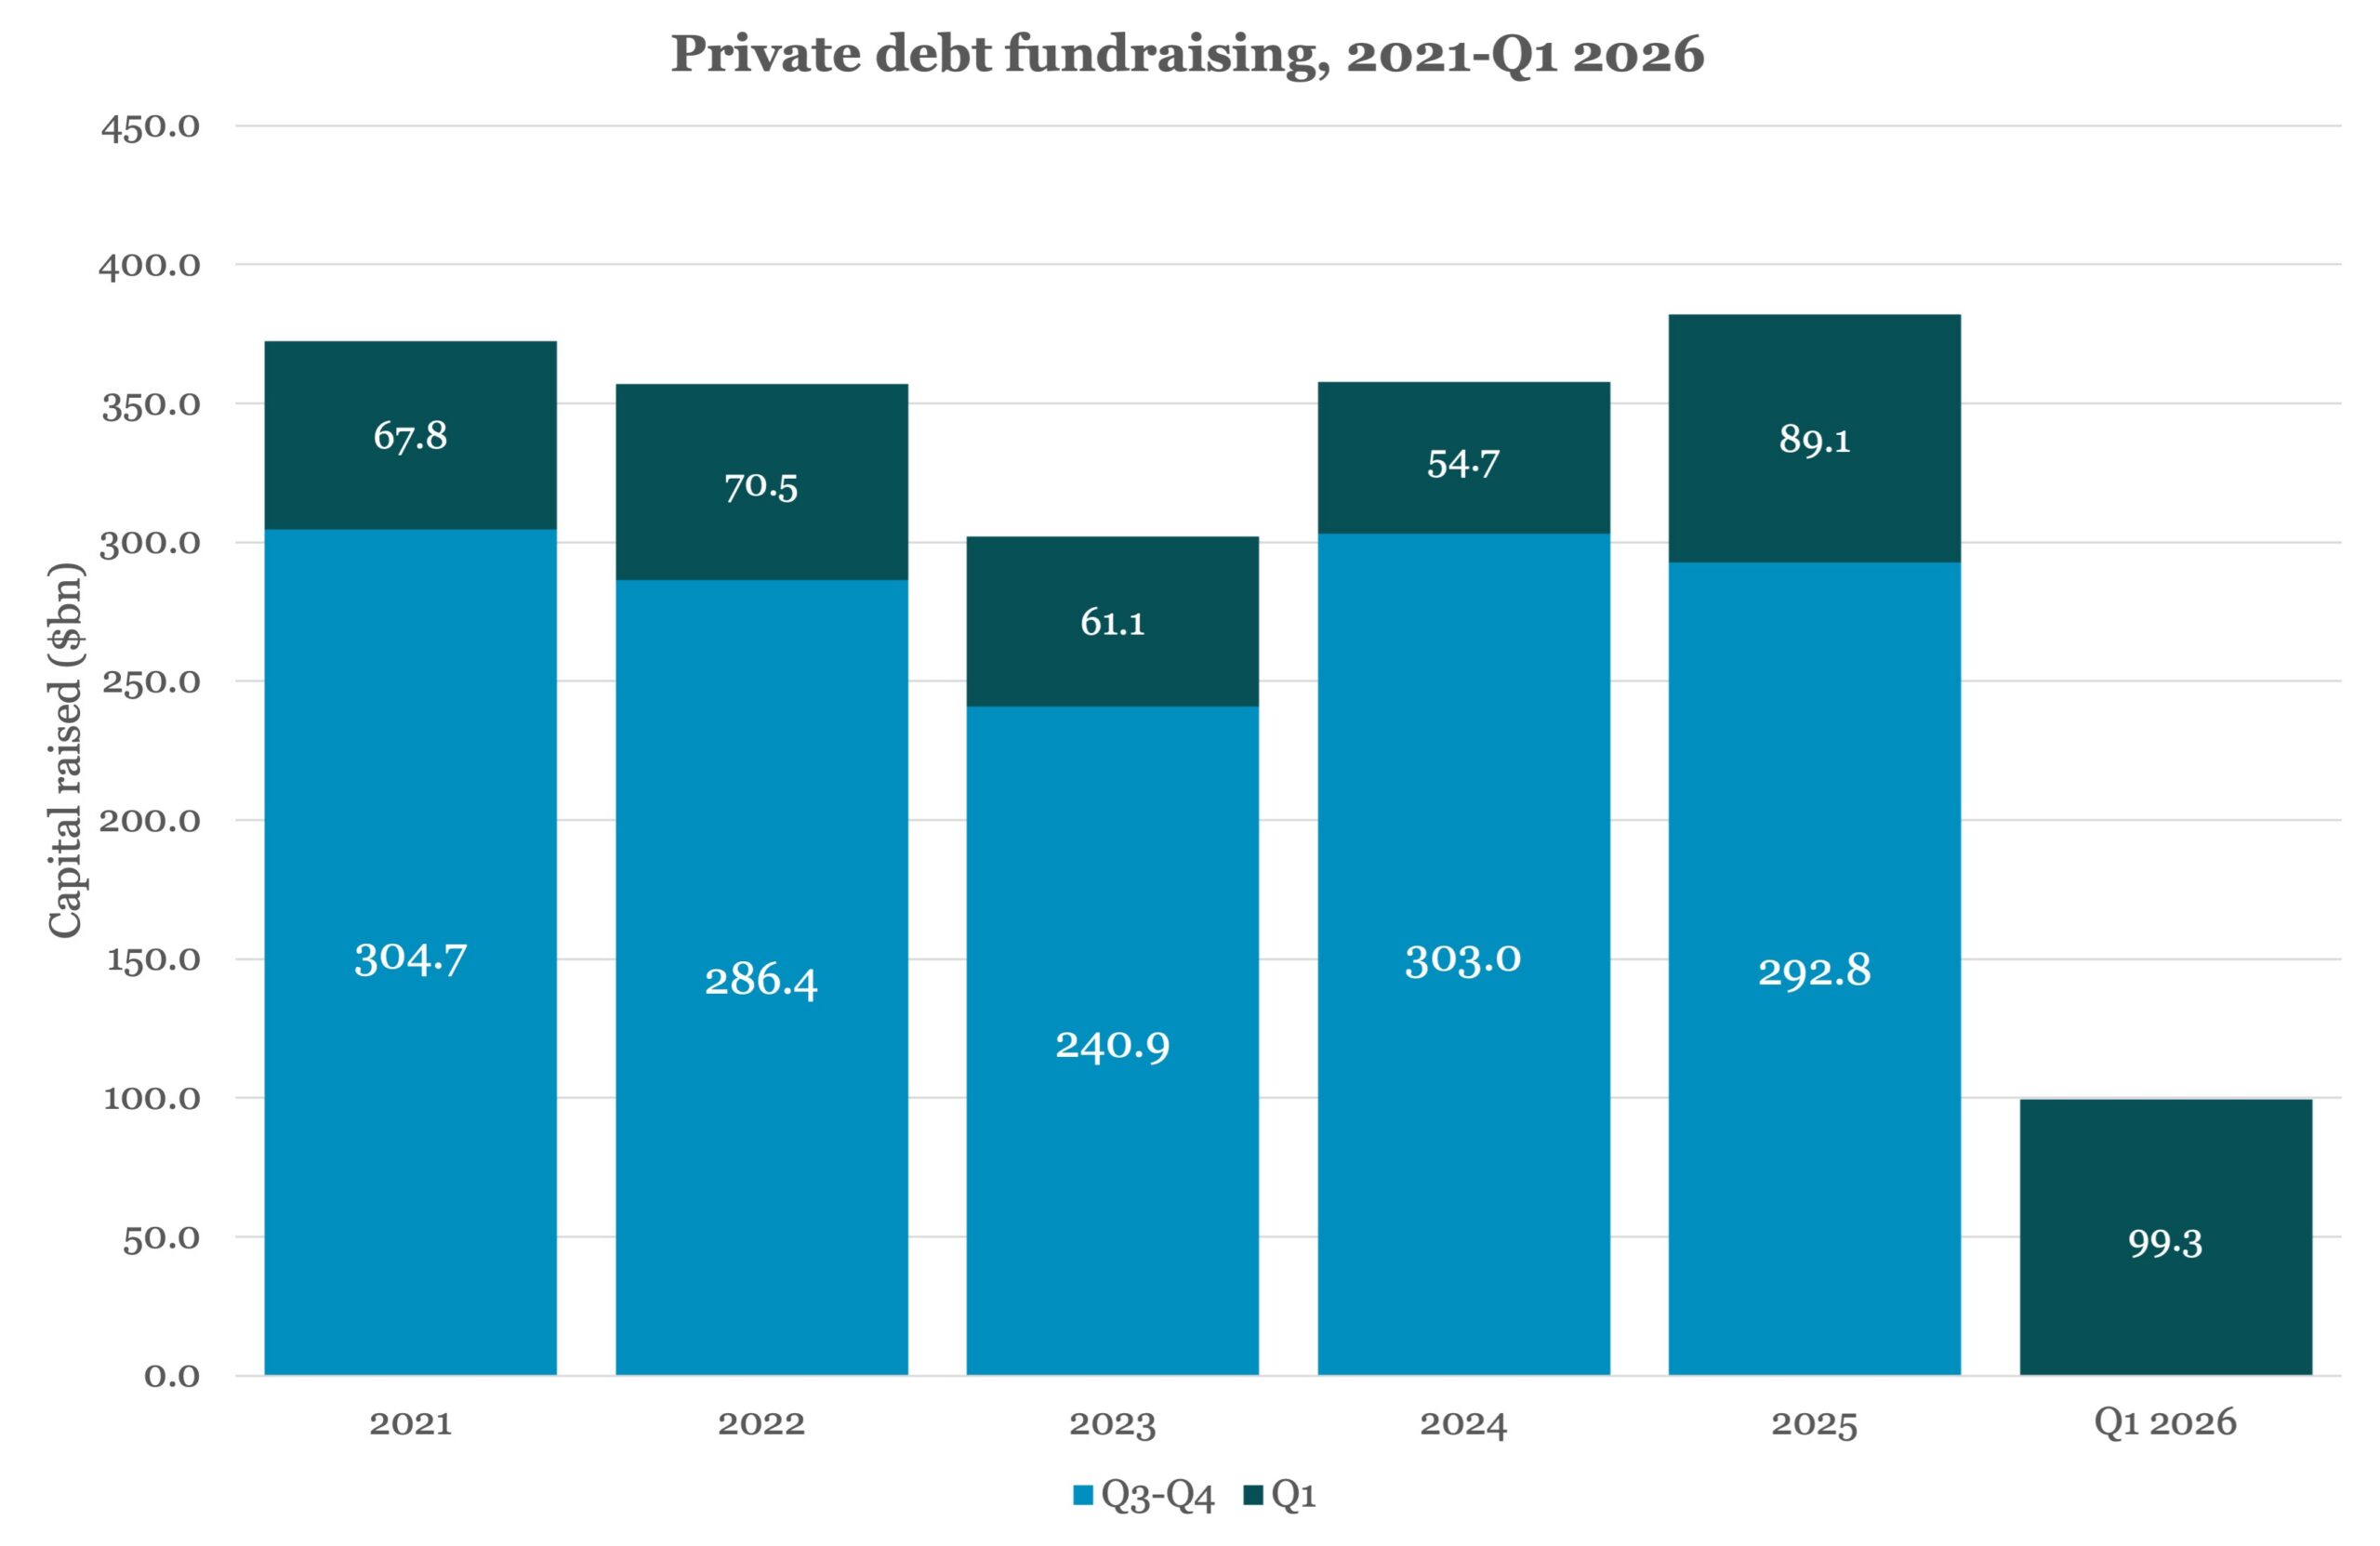
The first quarter of 2026 was the most prolific Q1 for global private credit fundraising in the last five years according to our data, setting the stage for an active year for private credit. Institutional investors’ feelings about the asset class have largely diverged from those of retail investors, which have raced for the exit from semi-liquid vehicles.
The $99.3 billion raised in Q1 (see chart) was ahead of the $89.1 billion raised in the first quarter of last year and a long way ahead of the $54.7 billon raised in Q1 2024. The asset class appears to be on course for one of its best-ever fundraising years if the momentum can be maintained.
When capital raising is broken down by targeted strategy, there appears to be little change from last year, with direct lending’s proportion edging up from 42 percent of the total for full-year 2025 to 43 percent in Q1 2026. The most significant move is made by distressed debt, up from 12 percent to 17 percent, suggesting investors anticipate troubled times ahead.
Fund sizes have continued their expansion from 2025, which saw the average fund grow to just short of an average $1 billion and which now stands at a little less than $1.3 billion. The growth in fund size speaks to the trend of consolidation in favour of the largest private credit managers, which are capable of raising and deploying over $10 billion of capital in a single vintage.
Despite much talk about the relative attractiveness of Europe, there is very little evidence from the data of a seismic shift. In Q1 2026, funds targeting North America accounted for $55.7 billion of fundraising compared with $25.9 billion for multi-regional funds and only $12.6 billion for funds operating in Europe.


Latest news

US leveraged loan launches reach five-month high in September
The US leveraged loan market recorded $93.6b of launches in September, marking the busiest month of primary market activity since…

Information technology topped nonaccruals on a cost basis
The information technology sector moved from second place in the first quarter to the top of the list in the second quarter
